
Opening a Cyprus Subsidiary or Branch | Key Differences and Requirements
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: A Cyprus subsidiary is a separate legal entity owned by its parent company, while a registered branch operates as an extension of the foreign company. A branch does not create a separate legal personality.
Table of contents
- What Is a Cyprus Subsidiary Company?
- What Is a Branch of a Foreign Company in Cyprus?
- What Is the Difference Between a Cyprus Subsidiary and a Branch?
- How Do You Register a Cyprus Subsidiary Company?
- What Documents Are Required to Incorporate a Cyprus Subsidiary?
- How Do You Register a Branch in Cyprus?
- What Documents Are Required to Register a Cyprus Branch?
- How Are Cyprus Subsidiaries and Branches Taxed?
- What Are the Annual Compliance Requirements for Each Structure?
- Which Structure Is Better for a Foreign Company Entering Cyprus?
- What Other Registrations and Approvals Are Required?
- How Can Arnifi Help With Cyprus Company Setup?
- FAQs
- Conclusion
What Is a Cyprus Subsidiary Company?
A Cyprus subsidiary company is a separate legal entity incorporated under the Cyprus Companies Law, Cap. 113. A foreign business can establish a subsidiary by owning shares in a Cyprus company, including a private limited company. This structure allows international businesses to establish a local presence while maintaining a distinct legal identity for their Cyprus operations.
A Cyprus subsidiary has its own corporate responsibilities, which include:
- Maintaining its own directors and company secretary
- Keeping statutory registers and accounting records
- Preparing financial statements
- Filing annual returns and fulfilling applicable tax obligations
- Entering into contracts and holding assets in its own name
A foreign parent company can own 100% of a Cyprus subsidiary. The subsidiary’s separate legal personality generally means that its obligations remain its own, subject to applicable law, guarantees and other arrangements.
What Is a Branch of a Foreign Company in Cyprus?
A Cyprus branch is a foreign company’s registered place of business in the Republic of Cyprus. Registration takes place under Part XI of the Companies Law, Cap. 113, which governs overseas companies establishing a place of business in Cyprus.
A branch does not create a separate legal entity. It remains part of the foreign company, and contracts entered into through the branch are contracts of the overseas company. The foreign parent remains responsible for its branch’s obligations and liabilities.
An overseas company establishing a place of business in Cyprus must register it with the Registrar of Companies within one month of establishment. It must also appoint an authorised person residing in Cyprus to accept legal documents and represent the company in dealings with third parties, courts and authorities.
A branch can therefore provide a local business presence while keeping the Cyprus operation legally integrated with its foreign head office.
What Is the Difference Between a Cyprus Subsidiary and a Branch?
The main difference between a Cyprus subsidiary and a branch is their legal identity. A subsidiary is a separate Cyprus company, while a branch operates as part of its foreign parent.
| Feature | Cyprus Subsidiary | Cyprus Branch |
| Legal personality | Separate Cyprus entity | Part of foreign parent |
| Liability | Subsidiary’s obligations generally remain with the subsidiary | Parent directly liable |
| Ownership | Foreign parent can own all shares | No separate ownership structure |
| Name | Own approved company name | Generally uses parent company’s name |
| Management | Own board and governance structure | Operates under parent authority |
| Contracts | Entered into by subsidiary | Entered into by foreign company through branch |
| Financial reporting | Cyprus company reporting requirements | Overseas company and branch reporting requirements |
| Taxation | Cyprus tax treatment of subsidiary | Cyprus taxation of branch profits attributable to local operations |
| Closure | Liquidation or other company closure procedures | Branch deregistration and relevant parent-level procedures |
The choice affects legal risk, reporting responsibilities and operational independence. Businesses should assess how much autonomy their Cyprus operation needs and whether they want local liabilities separated from the parent company’s activities.
How Do You Register a Cyprus Subsidiary Company?
Cyprus company incorporation involves preparing the required constitutional documents and submitting an application to the Registrar of Companies.
The process generally includes:
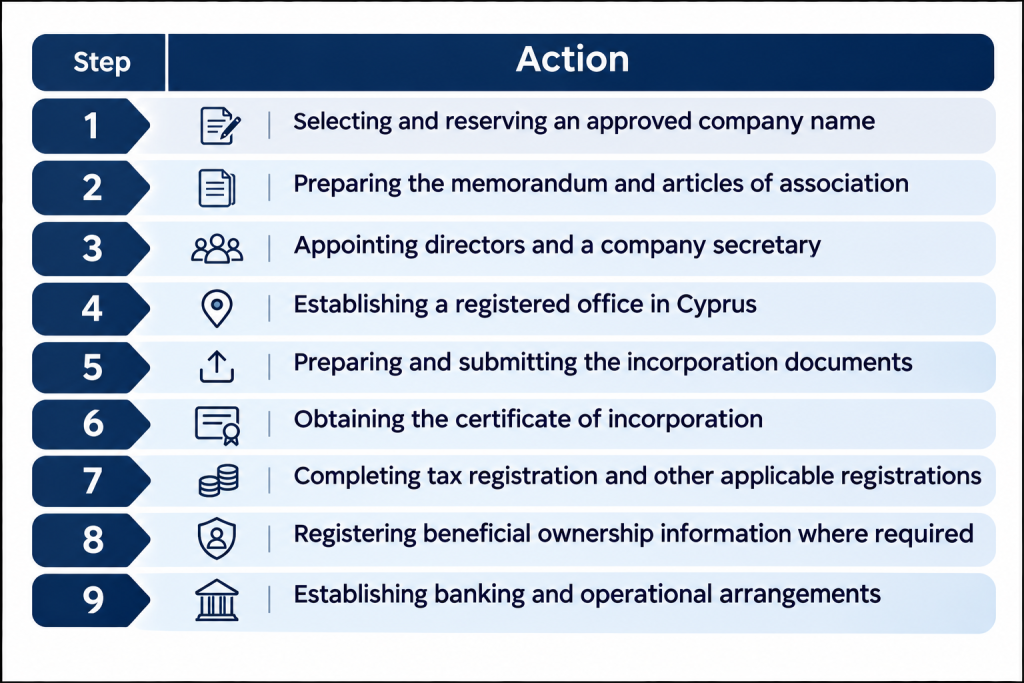
The memorandum and articles of association define the company’s structure, powers and internal governance arrangements. Incorporation documents are prepared and submitted through the appropriate Cyprus legal process.
Once incorporated, the subsidiary must maintain its statutory records and complete the applicable post-incorporation registrations.
What Documents Are Required to Incorporate a Cyprus Subsidiary?
The documents required depend on the shareholder structure and the company’s proposed activities. A foreign corporate shareholder may need to provide additional documents to establish its identity and authorise the investment.
A practical checklist includes:
- Proposed company name
- Memorandum and articles of association
- Details of shareholders and beneficial owners
- Director and company secretary particulars
- Identification and due diligence documents
- Registered office address
- Parent company incorporation documents, where applicable
- Corporate resolutions authorising the investment
- Supporting documents required by the Registrar or professional advisers
Foreign corporate documents may require certification, apostille or other authentication. Additional information may also be requested during incorporation or due diligence.
How Do You Register a Branch in Cyprus?
Registering a Cyprus branch involves establishing a place of business for the foreign company and submitting the required overseas company documents to the Registrar.
The process generally follows these steps:
- Establish the foreign company’s place of business in Cyprus
- Select and obtain approval for the branch name, where required
- Appoint an authorised representative residing in Cyprus
- Prepare the foreign company’s constitutional documents
- Compile details of directors, secretary and authorised representatives
- Prepare particulars of the Cyprus branch address
- Submit the prescribed documents to the Registrar
- Complete applicable tax registration
- Maintain the branch’s registration and reporting obligations
The overseas company must submit its registration application within one month of establishing its Cyprus place of business. The registration process can be completed through the Registrar’s electronic filing system or by the prescribed submission method.
What Documents Are Required to Register a Cyprus Branch?
Cyprus branch registration requires documents identifying the foreign company and its authorised representatives.
The Registrar’s prescribed documentation generally includes:
- Certificate of incorporation of the foreign parent
- Memorandum and articles of association or equivalent constitutional documents
- Details of directors and secretary
- Names and addresses of authorised representatives
- Cyprus branch address
- Details of the foreign company’s registered office
- Information on the company’s legal name and registration number
- Prescribed Registrar forms and supporting declarations
- Certified translations or authentication where required
The Registrar’s AE1, AE2 and AE3 forms are used for registering an overseas company’s place of business. Foreign documents may require apostille or other authentication, while documents in languages other than Greek or English require an acceptable translation.
The precise requirements depend on the foreign company’s jurisdiction and the documentation submitted.
How Are Cyprus Subsidiaries and Branches Taxed?
Cyprus applies a corporate income tax framework to taxable profits earned by companies and qualifying permanent establishments. From 1 January 2026, the standard corporate income tax rate is 15%, following an increase from 12.5%.
The tax treatment depends on the company’s residency and operating structure.
| Tax Consideration | Cyprus Subsidiary | Cyprus Branch |
| Taxable income | Generally taxed under Cyprus rules on the subsidiary’s taxable income | Taxed on profits attributable to the Cyprus permanent establishment |
| Corporate tax rate | 15% from 2026 | 15% from 2026 |
| Profit allocation | Subsidiary’s own income and expenses | Allocation between branch and foreign head office |
| Parent transactions | Transfer pricing considerations | Attribution of income and expenses to the permanent establishment |
| Profit transfers | Dividends or other permitted distributions | Transfers to foreign head office generally do not attract additional withholding tax |
A Cyprus subsidiary is generally treated as a Cyprus tax-resident company and is subject to the applicable rules governing its taxable income.
A branch is taxed on profits attributable to its Cyprus permanent establishment. The allocation of income, expenses and assets between the branch and foreign head office must reflect the applicable tax rules.
Both structures may have VAT, withholding tax, payroll and other obligations depending on their activities. The foreign parent’s home-country taxation and applicable double tax treaties can also influence the structure.
What Are the Annual Compliance Requirements for Each Structure?
Both Cyprus subsidiaries and branches must maintain records and fulfil applicable reporting obligations. However, the nature of their filings differs because a subsidiary is a Cyprus company, while a branch belongs to an overseas company.
| Compliance Requirement | Cyprus Subsidiary | Cyprus Branch |
| Accounting records | Required | Required |
| Financial statements | Cyprus company financial statements | Parent and branch reporting requirements |
| Annual Registrar filing | Annual return and relevant accounts | Overseas company and branch filings |
| Audit or review | Assess under applicable company rules | Assess under applicable reporting rules |
| Corporate tax return | Required where applicable | Required for Cyprus taxable operations |
| VAT registration | Where applicable | Where applicable |
| Payroll compliance | If employing staff | If employing staff |
| Registered particulars | Maintain company records | Maintain overseas company and branch particulars |
A Cyprus subsidiary generally files its annual return with the Registrar alongside the relevant financial statements. The first financial statements must be presented within 18 months of incorporation at the latest, followed by annual reporting requirements.
An overseas company must maintain its branch registration, notify changes in its particulars and fulfil its applicable annual obligations. These can include filing financial statements and other required documents relating to the foreign company and its Cyprus establishment.
Audit and review requirements should be assessed separately against the applicable legislation and company circumstances. Choosing a branch does not remove accounting, tax or reporting responsibilities.
Which Structure Is Better for a Foreign Company Entering Cyprus?
The right structure depends on the company’s business objectives, risk appetite and operational plans.
A Cyprus Subsidiary May Suit Businesses That:
- Want a separate legal entity for Cyprus operations
- Need local contracts and independent commercial relationships
- Plan to build a long-term local business
- Want to separate Cyprus operational risks from parent-company activities
- Expect local investors or future ownership changes
A Cyprus Branch May Suit Businesses That:
- Want to operate directly through their existing foreign company
- Prefer a unified legal structure
- Need a local establishment without incorporating another entity
- Can accept direct parent-company liability
- Want the Cyprus operation to remain integrated with the head office
Regulated activities may impose additional structural or licensing requirements. Businesses should confirm these requirements before choosing a subsidiary or branch.
What Other Registrations and Approvals Are Required?
Company incorporation or branch registration establishes a legal business presence. It does not automatically authorise every commercial activity.
Depending on the business, additional registrations and approvals may include:
- Tax registration with the Cyprus Tax Department
- VAT registration where applicable
- Employer registration and payroll compliance
- Social Insurance registration
- Business premises approvals where required
- Sector-specific licences and authorisations
- Immigration and employment permissions for relevant non-EU personnel
- Beneficial ownership reporting where applicable
- Foreign investment screening where the transaction falls within the applicable regime
Businesses operating in regulated sectors should identify the relevant licensing authority and approval requirements before commencing operations.
How Can Arnifi Help With Cyprus Company Setup?
Establishing a Cyprus subsidiary or branch involves decisions about legal structure, registration requirements and ongoing administrative responsibilities. Arnifi supports founders in understanding these options and organising the documentation needed for company establishment.
Its support can include:
- Guidance on Cyprus subsidiary and branch structures
- Assistance with company establishment and administrative documentation
- Guidance on registration requirements
- Help identifying relevant tax, licensing and compliance considerations
- Coordination with appropriate local professionals for specialised legal and tax matters
- Support for businesses planning their Cyprus market entry
Working through these requirements early can help businesses establish a clearer plan for their Cyprus operations.
FAQs
What is a Cyprus subsidiary company?
A Cyprus subsidiary is a company incorporated under Cyprus Companies Law, Cap. 113. It has its own legal personality and can be wholly owned by a foreign parent company.
Can a foreign company own 100% of a Cyprus subsidiary?
Yes. A foreign company can generally own all shares in a Cyprus subsidiary, subject to any applicable sector-specific restrictions or regulatory requirements.
Is a Cyprus branch a separate legal entity?
No. A Cyprus branch is part of its foreign parent company and does not create a separate legal personality.
What is the difference between a branch and a subsidiary in Cyprus?
A subsidiary is a separate Cyprus company with its own legal identity. A branch is a registered place of business belonging to an overseas company.
How long does it take to register a Cyprus subsidiary?
The timeframe depends on name approval, document preparation, due diligence and Registrar processing. The incorporation timeline should be confirmed against the current requirements and the completeness of the application.
How long does branch registration take in Cyprus?
The registration timeframe depends on the documents submitted and the Registrar’s processing. The foreign company must apply within one month of establishing its Cyprus place of business.
Is a Cyprus branch liable for its parent company’s debts?
The branch is part of the foreign company. Its obligations are therefore obligations of the parent company, which remains directly liable.
Does a Cyprus branch pay corporate tax?
Yes. A branch is generally taxed on profits attributable to its Cyprus permanent establishment at the applicable corporate income tax rate.
Does a Cyprus subsidiary need a local director?
Cyprus company law does not generally require every subsidiary to have a Cyprus-resident director. However, director appointments, management arrangements and tax residency considerations should be assessed carefully.
Which structure is better for a foreign company entering Cyprus?
A subsidiary may suit businesses seeking a separate legal entity and greater operational independence. A branch may suit companies that prefer to operate directly through their foreign parent. The decision depends on liability, taxation, reporting and commercial objectives.
Conclusion
Opening a Cyprus subsidiary or branch allows a foreign company to establish a business presence in Cyprus, but the two structures have different legal and operational implications. A subsidiary offers a separate legal identity, while a branch remains part of its overseas parent. These differences influence liability, registration, taxation and annual compliance. Businesses should assess their operational plans, risk appetite and regulatory requirements before choosing a structure, then prepare the necessary documentation and registrations to establish their Cyprus presence.
References
Top UAE Packages
Related Articles
Top UAE Packages
Planning Your Next Business Move?
