
Complete Operational Guide | Transfer Pricing Study in UAE
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact:
The UAE Corporate Tax legislation on transfer pricing dictates that any transaction with related parties or connected persons should be done at arm’s length through the use of mandatory Master/Local Files for those with a turnover of more than AED 200 million.
Table of contents
- Introduction
- Who Needs to Comply With UAE Transfer Pricing Rules?
- The UAE Transfer Pricing Compliance Framework
- When Are a Master File and Local File Required?
- Step-by-Step Transfer Pricing Study in UAE
- How Free Zone Companies and Tax Groups Are Affected
- Transfer Pricing Evidence Pack and Digital Proof
- Quarterly Transfer Pricing Monitoring Framework
- Advance Pricing Agreements (APAs) & New 2026 Fees
- Change-Control Protocol for Restructurings
- Common Transfer Pricing Compliance Risks
- Transfer Pricing Compliance Checklist
- Transfer Pricing Study vs. Ongoing TP Compliance
- Frequently Asked Questions
- Conclusion
- References
Introduction
Transfer Pricing in the UAE is the legislation that deals with the regulations on how related parties and connected persons make pricing of transactions under the UAE Corporate Tax legislation. In order to avoid profit shifting and maintain equitable treatment in taxation, UAE tax laws ensure that the arm’s length standard is adhered to in the pricing of transactions of business enterprises.
While traditional guidelines provide information regarding the fundamental rules as well as approved approaches to evaluation, true compliance entails much more than a one-time process at the end of the year. The process of conducting a thorough transfer pricing study in the UAE is more like a process flow within an organization, which includes segment accounting with audit documentation, functional analysis, benchmarking using databases, as well as change control for changes in organizational structure and services provided.
Who Needs to Comply With UAE Transfer Pricing Rules?
The requirement to be compliant with the UAE transfer pricing rules applies to various types of businesses in the following ways:
- Related-Party Transactions: Foreign or domestic transactions between parent companies, subsidiaries, sister companies, or associated firms.
- Connected-Person Transactions: Payments or transfers made to any person in relation to the shareholders, founders, directors, key management personnel, or their immediate family members.
- Mainland Companies: Inland companies doing business with local or international group companies.
- Free Zone Companies: All eligible free zones must be in compliance with the arm’s length rules; otherwise, it may affect their eligibility for 0% Corporate Tax.
- Tax Groups: Registered UAE tax groups are still required to prepare transfer pricing documentation and comply with arm’s length principles.
- Multinational Enterprise (MNE) Groups: UAE entities that form part of domestic or cross-border MNE groups are subject to multi-layered documentation.
The UAE Transfer Pricing Compliance Framework
The UAE transfer pricing structure is based on four key documentation building blocks aimed at providing full transparency for the Federal Tax Authority (FTA):
1. Transfer Pricing Disclosure Form
A form that must be submitted together with the annual Corporate Tax return. This document includes all relevant transactions between related parties or connected persons, and ensures that transaction amounts correspond to entries in the accounting general ledger.
2. Master File
It provides a summary of the entire enterprise group on a global level, including details on global business activities, the company’s organizational structure, value-chain drivers, intangibles, intercompany finance, and financial and tax positions of the consolidated group.
3. Local File
This file relates to the particular UAE resident entity and includes detailed functional analysis (FAR), transaction descriptions, intercompany agreements, selected methods of transfer pricing analysis, benchmarking reports, and economic analysis.
4. Country-by-Country Reporting (CbCR)
It applies to ultimate parent entities or surrogate reporting entities of MNE groups whose revenues exceed AED 3.15 billion. CbCR provides information on global revenue, taxes paid, number of employees, and capital allocation on a jurisdictional basis.
Practical Note: Transfer Pricing Documentation shall not be seen as a year-end task. There is a need for active maintenance of underlying documents, inter-company agreements, accounting records, and operational evidence throughout the financial year.
When Are a Master File and Local File Required?
Preparation and maintenance of the annual Master File & Local File shall be done based on the following revenues:
| Threshold Type | Condition / Trigger | Obligation |
| UAE Turnover Threshold | Entity revenue exceeds AED 200 million in the relevant tax period. | Prepare Master File and Local File annually. |
| CbCR Group Threshold | Entity is part of an MNE group with consolidated revenue exceeding AED 3.15 billion. | Prepare Master File and Local File annually. |
Businesses must track revenue limits through the year to ensure that all necessary documentation is completed before statutory FTA audits become necessary.
Step-by-Step Transfer Pricing Study in UAE
Executing a robust transfer pricing study in the UAE requires following an eight-step operational workflow:
Step 1: Map Related-Party and Connected-Person Transactions
Determine and value all intra-group transactions such as tangible assets, management/ intra-group services, financial transactions, intellectual property, and transactions with connected persons.
Step 2: Build the Segmental Accounting Map
The segmentation accounting chart should directly link all accounting segments (revenue, cost of sales, operating expenses, and margins) to general ledger accounts. The segmentation accounting chart helps in the preparation of the Local File, Disclosure Form, DMTT calculations, and safe harbour assessments.
Practical Note: The segmentation accounting system should be created such that the transaction-level data can be reconciled with the general ledger accounts and applied consistently in TP documentation and associated tax calculations.
Step 3: Conduct the FAR Analysis
Analyze the Functions performed, Assets used, and Risks taken by each entity. Evaluate the difference between contractual obligations and actual performance to develop the economic profiles of each entity.
Step 4: Select the Appropriate TP Method
Select the TP evaluation method out of the five known methods according to transaction features and availability of market data:
- Comparable Uncontrolled Price (CUP) Method: Comparison of the prices set for controlled and uncontrolled transactions
- Resale Price Method: Analysis of the gross margins generated from the resale of the product bought from a related party
- Cost-Plus Method: Assessment of the gross margin based on direct and indirect costs incurred
- Transactional Net Margin Method (TNMM): Comparison of the net margin indicators (Operating margin) to a relevant base
- Profit Split Method: Allocation of operating profits taking into account economic contribution
Step 5: Select the Tested Party and Profit Indicator
For the unilateral methods (TNMM and Cost Plus), select the tested party (usually the simpler one and without unique IP). Choose the Profit Level Indicator (PLI), for example, Operating Margin and/or Return on Total Costs.
Step 6: Conduct the Benchmarking Analysis
Look up business information from commercial databases to choose appropriate comparable companies according to industry, geographical scope, and function. Filter search outputs to come up with an appropriate arm’s-length range.
Practical Note: Benchmarking should be consistent with the entity’s activities, asset base, risks, and transaction characteristics and not just the industry margins alone.
Step 7: Determine the Arm’s-Length Outcome
Test the results of the party under test against the benchmark range to determine whether there will be any adjustments are needed in terms of margins to ensure consistency in the interquartile range.
Step 8: Prepare the TP Documentation
Compile all TP Documents such as the master file, local file, disclosure form, intercompany agreements, economic benchmarking, and general ledger reconciliations.
How Free Zone Companies and Tax Groups Are Affected
- Free Zone Entities: Arm’s length pricing on related-party dealings is an essential statutory obligation to continue the eligibility for Corporate Tax at 0%. Inappropriately priced transactions may lead to income re-characterization and the loss of all tax privileges.
- Tax Groups: Although intra-group dealings are not taken into account when calculating corporate tax liabilities of consolidated companies, tax groups are still obliged to provide arm’s length pricing and documentation as per FTA requirements.
Transfer Pricing Evidence Pack and Digital Proof
The following should be included in the dedicated evidence pack to prepare for potential audits:
- Intercompany agreements and amendments
- Invoices, general ledger entries, and segmented income statement
- Benchmarking report and FAR documentation
- Boards’ decisions, pricing formulas, and true-ups
Integration of Paperless Digital Tax Certificates
With Cabinet Decision No. 174 of 2025, tax registration certificates in physical form are replaced by free paperless digital certificates with verification through a QR code. With the inclusion of digital certificates in the Evidence Pack, the tax status of the entity can be verified electronically in the event of an FTA audit.
Quarterly Transfer Pricing Monitoring Framework
To prevent year-end tax surprises, implement an ongoing quarterly review cycle:
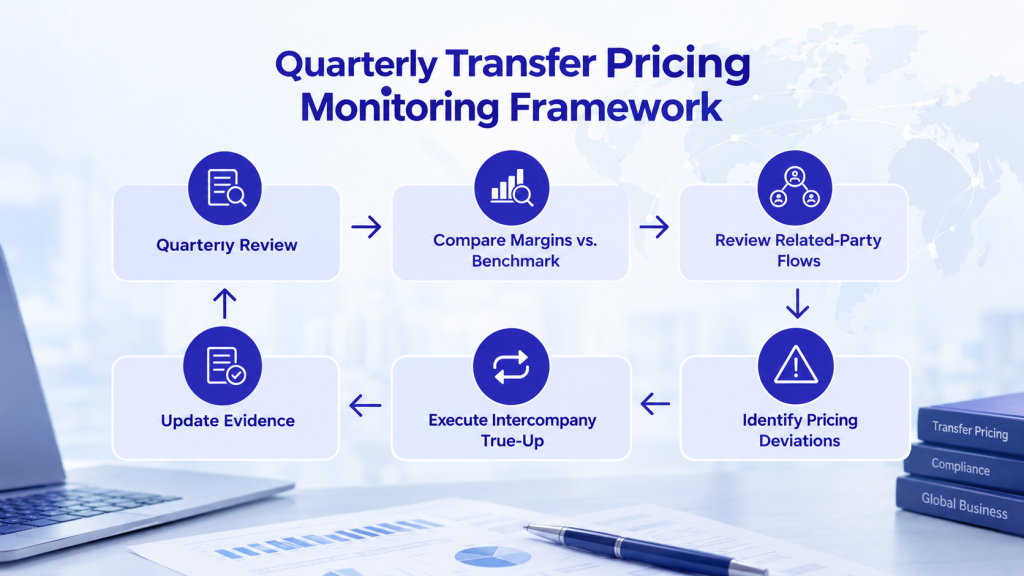
With periodic reviews, companies have the opportunity to compare their profit margins with benchmark targets, make true-up adjustments on time, harmonize the intercompany agreement with the general ledger inputs, and update the log of evidentiary records.
Advance Pricing Agreements (APAs) & New 2026 Fees
Advance Pricing Agreements (APAs) help businesses get upfront certainty in terms of taxation since they can agree on the method of pricing with the tax authorities in advance.
In accordance with Cabinet Decision No. 174 of 2025 (implemented from January 1, 2026), the following fees apply to unilateral APA applications:
- First-Time Unilateral APA Application Fee: Applicable upon initial submission.
- APA Renewal or Amendment Fee: Applicable when extending or modifying an existing agreement.
Change-Control Protocol for Restructurings
If there is a change in the company’s operation, such as reorganization of the group, change in ownership, intercompany service flows, or risk allocation, then documentation needs to be updated.
Practical Note: An existing APA cannot automatically be considered to be still valid once there is a change in the transaction, corporate form, or range of services being performed.
Common Transfer Pricing Compliance Risks
The following are some of the typical risks faced by businesses conducting transfer pricing studies in the UAE:
- Management service fees without any support for their benefit
- Unsupported royalty rates or transfers of intellectual property rights
- Interest rates on intra-group loans that are not arm’s-length in nature
- Mismatch between contractual terms and entries in the company’s general ledger
- Usage of generic or old benchmarking information that is not location-specific
Transfer Pricing Compliance Checklist
| Compliance Area | Verification Check |
| Related Parties & Connected Persons | All related-party and connected-person transactions identified and classified. |
| FAR Analysis | Functions, assets, and risks fully documented for involved entities. |
| TP Method | Appropriate method chosen from the 5 approved evaluation methods. |
| Benchmarking | Databases queried for comparable market data and arm’s-length range established. |
| Accounting & Segmental Mapping | Intercompany flows reconciled to general ledger categories. |
| Disclosure Form | Information prepared for submission with annual tax return. |
| Local File & Master File | Annual files prepared if turnover >AED 200M or group falls under CbCR rules. |
| CbCR Assessment | MNE group revenues checked against the AED 3.15B threshold. |
| Evidence Pack | Supporting contracts, invoices, and digital tax certificates maintained. |
| Change Control & APAs | Business shifts evaluated for documentation updates or APA amendments. |
Transfer Pricing Study vs. Ongoing TP Compliance
The one-off TP assessment in UAE will involve static analyses like mapping of transactions, creation of FAR profiles, selection of appropriate methodologies, and benchmarking. However, transfer pricing compliance involves continuous monitoring of operations, which includes tracking of quarterly margins, reconciling transactions from agreements to accounts, true-up of intercompany transactions, change control process, and preparation of an auditable package of evidence.
Frequently Asked Questions
What is transfer pricing in the UAE?
Transfer pricing in the UAE is about the laws and regulations surrounding the pricing of transactions (goods, services, finance, and intellectual property) carried out between related parties and connected persons as per UAE Corporate Tax law.
Who needs to comply with UAE transfer pricing rules?
It is applicable to mainland companies, free zone companies, tax groups, connected persons, and multinational groups conducting transactions with related parties.
What is the arm’s-length principle in the UAE?
The arm’s-length principle entails that related parties treat their transactions as independent commercial enterprises under similar circumstances in the market.
What are the five transfer pricing methods in the UAE?
These include the Comparable Uncontrolled Price (CUP) Method, Resale Price Method, Cost-Plus Method, Transactional Net Margin Method (TNMM), and Profit Split Method.
When is a Local File required in the UAE?
This file must be provided on an annual basis by entities that have revenues in the UAE exceeding AED 200 million or belong to MNE groups with CbCR requirements.
When is a Master File required in the UAE?
This file must be provided on an annual basis along with the Local File in case the revenues exceed AED 200 million, or the entity belongs to a CbCR group.
What is the UAE transfer pricing disclosure form?
It is a form that summarizes the information provided along with the Corporate Tax return and includes details of all related party transactions and connected persons arrangements.
Does transfer pricing apply to UAE Free Zone companies?
Yes, Free Zones must observe the arm’s length principle; failure to do so will result in loss of 0% Corporate Tax qualifying income.
Does transfer pricing apply to tax groups?
Yes, even if tax liability is consolidated within the tax group, it needs to comply with the arm’s length pricing principle, along with maintaining documentation of the intra-group transactions.
What is a transfer pricing study?
A transfer pricing study in the UAE includes a systematic process that involves transaction mapping, FAR analysis, choice of methods, benchmarking, and documentation to support arm’s length pricing.
What is an APA in the UAE?
Advance Pricing Agreement (APA) is an agreement between the taxpayer and the FTA in respect of setting the methodology of pricing among intercompany transactions.
What are the new UAE APA fees from 2026?
According to Cabinet Decision No. 174 of 2025, official fees have been introduced for first-time unilateral APA applications as well as APA renewals and amendments, starting from January 1, 2026.
How should businesses prepare for a UAE transfer pricing audit?
One should make sure to maintain an active Evidence Pack, ensure GL consistency with intercompany agreements, and perform quarterly true-ups and benchmarking report updates.
How does segmental accounting support transfer pricing compliance?
Segmental accounting separates intercompany revenues, costs, and margins, connecting transactional data to ledger accounts and facilitating Local File disclosures.
When should an existing APA be reviewed or amended?
It will be necessary to review/amend an APA when there are changes in the structure of the group, scope of services, operations, risks, or assets.
Conclusion
Completing a transfer pricing analysis in the UAE entails mapping out all intercompany transactions, conducting an intensive FAR analysis, choosing the right pricing strategy, and performing accurate benchmarking searches. Companies have to perform their Disclosure Form, Master File, and Local File tasks alongside segmental accounting consistent with ledger classifications.
To be prepared for audits in the UAE Corporate Tax environment, businesses need to transition from the traditional year-end activity to continuous monitoring and analysis involving review of margins on a quarterly basis, completion of true-ups on time, keeping the evidence pack updated with digital evidence, and managing changes properly.
References
- Federal Tax Authority (FTA) Official Portal: https://tax.gov.ae/
- Ministry of Finance (MoF) – UAE Corporate Tax & Transfer Pricing Regulations: https://mof.gov.ae/
- OECD Transfer Pricing Guidelines for Multinational Enterprises and Tax Administrations: https://www.oecd.org/tax/transfer-pricing/
Top UAE Packages
Related Articles

Top UAE Packages
Get in Touch
