
Securing Limited Partnership Interests in Cayman Fund Finance
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: While subscription lines depend upon capital commitments without funding made by the investors, NAV facilities get collateralized through the value of the portfolio of assets held. Both entail proper structuring within the Cayman Islands laws to make sure that the security package is enforceable.
Table of contents
- Introduction
- Subscription Lines vs. NAV Facilities: Understanding the Security Landscape
- Mechanics of Taking Security: The Role of Equitable Charges
- Statutory Compliance: Navigating Mandatory General Partner (GP) Consent
- Establishing Priority: Serving Formal Notice & Register Updates
- Cross-Border Execution: Bridging Foreign Security Agreements with Cayman Law
- Managing Enforcement Risks & Resolving GP Conflicts
- How Arnifi Simplifies Global Fund Structuring & Post-Setup Compliance
- References
Introduction
In the arena of global alternative investment, the Cayman Islands continue to be an outstanding offshore jurisdiction for PE, VC, and hedge fund structures. Leveraged fund financing is a common method of financing such funds when they strive for liquidity. But the proper security package is what makes the financing of the fund successful.
Fund finance is usually categorized into two types of financing: subscription line facilities (financing that takes advantage of commitments made by investors) and NAV facilities (financing that takes advantage of underlying assets within the portfolio). In either case of financing, whether through the use of an ELP, a Cayman LLC or an exempted company, lenders have to be cautious about statutory requirements, GP consents, security registration and the enforcement process from the get-go.
While the majority of discussion around the markets revolves around commercial loan terms and not on the technical process of creating and enforcing security over Cayman fund interests, this guide takes a closer look at the process of structuring security over limited partnership interests, meeting statutory requirements, cross-border documentation and avoiding GP enforcement problems before closing.
Subscription Lines vs. NAV Facilities: Understanding the Security Landscape
The understanding of the vehicle nature and the asset underpinnings of that vehicle will be reflected in the structure of the collateral package used by the lending institution.
Subscription Line Facilities
Subscription line (or capital call) facilities represent short-to-medium term credit facilities for the fund.
- Primary Collateral: The lending institution secures its financing arrangement based on the ability of the fund to draw uncalled capital commitments from its Limited Partners (LPs), ability to force capital commitments from LPs who violate their obligations, and the dedicated capital call bank account where LP commitments are deposited.
- Risk Profile: The credit risk associated with the facility is linked to the creditworthiness of the LPs rather than the performance of the underlying investment.
NAV Facilities
NAV facilities are usually provided towards the end of the fund lifecycle when there is little uncalled capital left in the fund, but the portfolio is highly valuable.
- Primary Collateral: The security is placed either directly or indirectly over the fund’s investment portfolio, cash flow, and equity in holding entities.
- Why NAV is Growing in Cayman: As funds continue to retain their assets in different macroeconomic circumstances, it is common for sponsors to finance through NAV facilities for their follow-on investments, liquidity or distributions.
Common Cayman Security Targets
Based on the asset level at which lending is done, lenders may place security over:
- Limited Partnership Interests in a Cayman Islands Exempted Limited Partnership (ELP).
- Shares/Membership Interests in Cayman Limited Liability Companies (LLCs).
- Shares in Cayman Exempted Companies (acting as holding vehicles or co-investment entities).
The selection of collateral determines the degree of flexibility of the sponsor throughout the loan period and determines how a lender will collect its dues on default.
Mechanics of Taking Security: The Role of Equitable Charges
In terms of securing the loan against a limited partnership interest in a Cayman ELP, lenders practically always rely on using the so-called equitable charge (also known as an equitable mortgage) rather than legal assignment.
How an Equitable Charge Operates
Creates an Encumbrance on Economic Rights: It provides the borrower with a lien over the economic interests associated with the LP interest, including such things as rights to get money from the funds and return the initial investment.
Preserves Legal Title with the Borrower: In case no default happens, the borrowing Limited Partner keeps legal ownership and participation in the partnership.
Provides Contingent Enforcement Rights: Upon the occurrence of a default event, the lender/collateral agent is entitled to exercise its power of sale.
Advantages of an Equitable Charge
- Operational Continuity: Legal title, voting rights, and ongoing communications within the fund framework remain with the LP until default occurs.
- Avoidance of Immediate Liability: In failing to effect an immediate transfer of legal ownership, the lender does not become a substituted limited partner on completion of the transaction, thus shielding itself from being automatically liable for the obligations of the partnership until enforcement has been executed.
- Enforcement Realization: This charge confers on the lender the ability, through contract and equity, to enforce the transfer of the LP interest to the lender or to a nominated person upon default.
Practical Consideration: It is necessary that security documentation clearly sets out the absolute right of the lender to demand a formal transfer of the LP interest.
Statutory Compliance: Navigating Mandatory General Partner (GP) Consent
Under the Exempted Limited Partnership Law (revised) of the Cayman Islands, statutory requirements relating to transfers of and encumbrances on LP interests are strictly adhered to.
Statutory Consent Requirements
Section 7(3) of the Cayman ELP Act normally stipulates that an LP cannot assign, transfer, or pledge its partnership interest without the express written consent of the General Partner, except where the LPA specifically states otherwise.
In this respect, lenders must secure such consent for two separate acts:
- The Initial Pledge: Consent to the creation and granting of the security interest/equitable charge over the LP interest at closing.
- The Enforcement Transfer: Consent to the assignment or transfer of the LP interest to the lender, their nominee, or a third-party purchaser in the event of an enforcement following a default.
Seeking only consent to the initial pledge is often a mistake made by lenders, as it leaves discretionary control in the hands of the GP over future assignments or transfers. This effectively gives them the power to stop the lender from taking title and transferring the LP interest in the event of a default.
Establishing Priority: Serving Formal Notice & Register Updates
Prioritization of security against an interest in a Cayman LP shall be determined according to the principles of equity and statute under Cayman law. It shall be necessary to execute notice and registration procedures to achieve priority over third parties.
Servicing Formal Notice
In order to have the right of priority according to the rule in Dearle v Hall, it will be necessary to provide statutory notice of the interest in writing to the ELP at its registered office in the Cayman Islands.
Mandatory Contents of Statutory Notice:
- Name of the security agreement.
- Date of execution.
- Full legal names of all parties (Grantor and Grantee/Lender).
- Clear description of the specific LP interest being encumbered (e.g., percentage, committed capital amount).
Statutory Registers
It will be necessary to create statutory registers under the ELP Act, which obliges the General Partner to keep the following registers at the registered office:
- Register of Limited Partner Interests: Record legal ownership and commitments.
- Register of Security Interests: Record encumbrances over the partnership interests.
Practical Closing Checklist
- Security Agreement (Equitable Charge) Executed
- Dual-Scope GP Consent Obtained (Covering both Initial Grant and Enforcement Transfer)
- Formal Statutory Notice Prepared with all required statutory details
- Notice Served directly at the ELP’s Cayman Registered Office
- ELP Register of Security Interests Updated by the GP/Registered Office
- Post-Closing Verification: Certified copy of updated Register of Security Interests reviewed by Lender
Cross-Border Execution: Bridging Foreign Security Agreements with Cayman Law
Financing structures for funds are often based on cross-border documentation. Facility Agreement and Main Security Documentation could be subject to New York Law or English Law jurisdiction, while the governing law for the underlying fund is Cayman Islands law.
Harmonizing Foreign Law and Cayman Requirements
Whereas UCC filings or English debentures may govern the overall security structure, Cayman Islands law will govern the creation, perfection, and enforcement mechanics for Cayman-based equity interests and LP interests.
- Cayman Recognition: Security documents under foreign law must include references to Cayman legal requirements, namely the Cayman ELP Act or the Companies Act.
- Undated Transfer Deliverables: Undated transfer documents, power of attorney documents, and proxy documents will need to be executed by the borrower/LP at closing, which will be placed in escrow by the lender, in case these need to be used in the event of default without any signatures of the borrower needed.
- Third-Party & Manager Approvals: Determine if investment managers, advisory board, or regulatory bodies have independent consent rights in the LPA and fund management agreements.
Practical Consideration: Documentation across borders needs to be considered as one integrated security package, rather than considering Cayman statutory filings as a procedural step after closing.
Managing Enforcement Risks & Resolving GP Conflicts
Even when the security is created properly and documented, there could be resistance to enforcement of security due to the centralized authority of the General Partner.
GP Conflict of Interest During Default
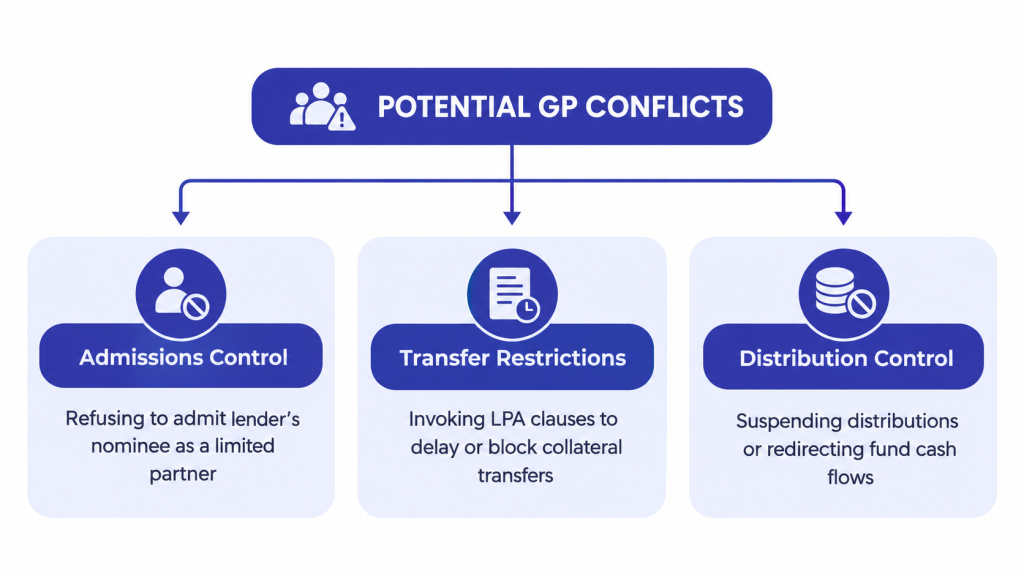
The General Partner controls the day-to-day business operations of the fund and is a common owner or affiliate with the fund sponsor. The interest of the GP may conflict with that of the lender if the fund defaults.
Crucial LPA Terms to Negotiate Upfront
It is recommended for lenders to review and negotiate the following provisions of the Limited Partnership Agreement before the closing of the credit facility:
- Unconditional Admission: Insist on the LPA stipulating that all lenders and transferees who have taken LP interests through enforcement of the security will be admitted as a Limited Partner irrespective of the GP’s approval.
- Waiver of Transfer Restrictions: Check if typical LPA provisions of rights of first refusal (ROFR) and co-sale rights do not restrict the lender from transferring the asset through enforcement.
- Distribution Mechanics: Ensure that there are provisions requiring any distributions related to the charged LP interest to be paid directly into the account of the lender upon receiving default notice.
- GP Removal Mechanics: Determine if the lender and other secured creditors have the right to change the GP in case of catastrophic defaults.
Key Takeaway: Realizing value from secured collateral relies as much on clear terms within the underlying partnership agreement as it does on the security document itself.
How Arnifi Simplifies Global Fund Structuring & Post-Setup Compliance
Setting up cross-border fund structures entails a smooth integration between the processes of setting up an entity, governance across jurisdictions, and compliance. In case a fund manager wants to set up an entity in the Cayman Islands, it is important for the organization to remain ready in order to get debt financing as well as comply with the stringent due diligence of lenders.
Arnifi provides corporate governance and business setup services for fund managers and asset managers operating their fund entities across the globe:
- Global Entity Formation: Smooth process of setting up ELPs, LLCs, exempted holding companies, and regional entities in key financial jurisdictions.
- Corporate Governance Support: Setting up corporate records and statutory registers in line with international financing standards.
- Post-Setup Compliance: Ensuring good standing and statutory compliance of the entity throughout its lifecycle.
The fund financing structures are not only about setting up a Cayman entity. From setting up to corporate governance and jurisdictional compliance of entities, Arnifi will help fund managers coordinate the entire process.
References
- Cayman Islands Monetary Authority (CIMA) – Regulatory body supervising financial services and investment funds in the Cayman Islands.
- Cayman Islands Judicial Administration – Official portal for Cayman legal and statutory frameworks.
- Loan Market Association (LMA) – Authoritative guide and documentation standards for syndicated and private fund financing transactions.
- Institutional Limited Partners Association (ILPA) – Industry association providing standards and guidelines for private equity subscription lines and fund governance.
Top UAE Packages


Related Articles
Top UAE Packages
Get in Touch