
Evolving Fund Distribution Waterfalls: A Modern Guide to Carried Interest & GP-LP Alignment
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Table of contents
- Introduction
- What Is Carried Interest and Why Is the Traditional Model Changing?
- Modern Fund Vehicles Driving Complexity in Carry Arrangements
- Multi-Tiered Waterfalls: Hurdles, Catch-Ups, and Distribution Sequencing
- Valuation and Timing: Managing NAV-Based Accruals and Unrealized Assets
- Recycled Carry and Targeted Incentive Pools
- LP Protection Mechanisms: Blended Waterfalls and Offset Clauses
- Legal Documentation: Drafting Bespoke Partnership Agreements
- Frequently Asked Questions
- Structuring Global Investment Vehicles with Arnifi
- References
Introduction
The traditional structure of funds has always been based on a simple economic model, whereby Limited Partners (LPs) would have their capital contribution, along with their agreed-upon preferred return, returned before the General Partner (GP) could participate in any gains generated by the fund, usually through a standard 20% carried-interest structure.
Modern fund structures are far more sophisticated. The current environment features many types of return hurdles, catches, interim valuations, designated carry pools, and increased LP protections for investors. In this guide, we take a look at how modern fund waterfall distributions work and how modern carry structures are negotiated, calculated, and contractually set up.
What Is Carried Interest and Why Is the Traditional Model Changing?
Meaning of Carried Interest
Carried interest, or simply “carry,” is a performance-related profit participation of the GP in the returns of the fund. As the main economic mechanism used in private equity, venture capital, real estate, and private credit funds, carry aligns the economic interests of the fund manager with its investors.
The Traditional Carry Model
In a standard closed-ended fund lifecycle, cash flows traditionally flow through three distinct phases:
- Return of Capital: LPs recover 100% of their cumulative contributed capital.
- Preferred Return / Hurdle: LPs receive a contractual return threshold (typically 7%–8% annualized).
- GP Carry: The GP receives its 20% share of net fund profits (often after a GP catch-up tier).
Why the Traditional Model Is Changing
The closed-ended single pool is no longer the only type of fund model used by institutional managers. Contemporary investment vehicles are leading to developments in the following ways:
- Multiple Investment Vehicles: Parallel funds, co-investments, and continuation vehicles working simultaneously.
- Cross-Border Participation: International LPs in different jurisdictions with diverse taxes, regulations, and laws.
- Diverse Investor Classes: Customized fees and carry arrangements based on commitment amount, anchor investor, or liquidity.
- Complex Multi-Strategy Mandates: Liquidity strategies, illiquid credit investments, real assets, and growth equity within one managerial organization.
Practical Note: The standard waterfall presumes a sequential life cycle. Modern investment vehicles usually have overlapping life cycles, multistage valuations, and reinvestment rights that need to be clearly structured legally.
Modern Fund Vehicles Driving Complexity in Carry Arrangements
Today’s capital approaches involve customizing investment vehicles that directly impact the traditional approach to carry calculation:
1. GP-Led Continuation Funds
In the case where high-conviction investments span beyond the customary ten years of a fund’s life, there is a need for the migration of such investments to a CV. The carry mechanics need to take into consideration the realized returns on the primary fund and roll/crystallize carry for the investment.
2. NAV-Based Financing
Often, funds use the NAV lines in order to manage liquidity, raise follow-ons, or pay out the LPs their capital. The use of leverage in a fund would change the basic NAV, hence the point at which carry will be computed before realizing the investment.
3. How an Equitable Charge Operates
The functioning of an equitable charge involves creating a charge on the economic rights and interest attached to the LP interest in relation to economic rights (distributions and capital returns) without changing the legal title of the LP interest to that of the lender.
- Economic Encumbrance: Economic rights and distributions (cash flow) are charged, but legal title is not changed.
- Legal Title Retention: Borrowing LP keeps legal title until an enforcement event.
- Power of Sale: If there is an event of default, then the lender uses its power of sale to enforce the charge and change the legal title of the partner interest.
4. Co-Investment Funds
Co-investment funds provide select LPs an option to invest directly in addition to their investment in the main fund. Since such investments have a lower management fee and no carry (0/10 or 1/10 structure), it becomes necessary for distributions to be carved out separately from the main fund.
5. Multi-Strategy Platforms
Firms that invest in private equity, venture capital, and private credit via a common management platform often maintain separate carry pools. This ensures that good performance in one asset class does not compensate for poor performance in another.
6. Hybrid and Evergreen Structures
The absence of set liquidation deadlines in evergreen funds means that carry becomes dependent on periodic and independent portfolio valuations.
7. Cross-Border Participation
International funds generally employ a master-feeder structure through several jurisdictions. Issues such as withholding taxes, local regulations, and double taxation agreements determine how carry is realized and distributed among GP managers.
Multi-Tiered Waterfalls: Hurdles, Catch-Ups, and Distribution Sequencing
The distribution waterfall sets out the exact order of contractually distributing the profits to the LPs and the GP.
| Waterfall Stage | Sequence Priority | Primary Recipient | Commercial Purpose |
| 1. Return of Capital | First | Limited Partners | Fully recovers contributed capital, management fees, and fund expenses. |
| 2. Preferred Return / Hurdle | Second | Limited Partners | Pays baseline contractual return threshold (typically 7%–8% IRR). |
| 3. GP Catch-Up | Third | General Partner | Allocates catch-up percentage (e.g., 50%–100%) until GP reaches its agreed carry share. |
| 4. Subsequent Profit Sharing | Fourth | LP / GP Split | Splits remaining profit according to contractual terms (e.g., 80% LP / 20% GP). |
| 5. Adjustments & Offsets | Fifth | LP / GP Rebalancing | Applies fee offsets, blended valuation checks, or escrow withholdings before final distribution. |
Core Waterfall Tiers
- Return of Capital: LPs receive back 100% of the capital invested in the investment write-off, together with management fees and fund expenses allocated to it.
- Preferred Return / Hurdle: LPs get a minimum contractual return on their invested capital (e.g., 8% IRR) before any profit participation by the GP.
- GP Catch-Up: This is a contractual provision that allows the GP to take more than its agreed percentage (for example, 20%) of the distributions (up to 50-100%) until the total amount of the profits received by the GP equals its contractual share.
- Subsequent Profit-Sharing Tier: Subsequent profits are shared in accordance with the terms of the standard deal (for example, 80% to LPs, and 20% to the GP).
- Multiple Hurdles: More sophisticated deals include barriers with ratchets. So, if there is an 8% IRR, then 20% carry applies, but if there is a 15% IRR, then the GP will get 25% carry.
- Class-Specific Distribution: Side letters or different classes of LPs (e.g., Seed, Anchor, and Institutional) can have varying barriers or fee offset levels requiring separate waterfall calculations.
Practical Note: The waterfall calculation is very sensitive to order of precedence. The interplay between capital recovery definitions (deal-specific vs. overall fund), hurdle compounding frequency, and catch-up percentages determines distributions.
Valuation and Timing: Managing NAV-Based Accruals and Unrealized Assets
| Feature | Realized Distributions | NAV-Based / Interim Accruals |
| Calculation Basis | Actual cash proceeds from exits | Mark-to-market valuation estimates |
| Certainty Level | High (actual cash available) | Subject to market volatility & audit adjustments |
| Clawback Risk | Low to moderate (depends on fund-level performance) | Higher (subsequent asset markdowns can create over-allocation) |
| Primary Use | Final cash distributions | Financial reporting, carry crystallization in open-ended vehicles |
Handling Unrealized Assets and Interim Accruals
Valuations of carry allocations for hard-to-value assets must be done in line with clearly outlined valuation policies. If carry allocation is made based on the increase in interim Net Asset Value (NAV) before the actual realization of the asset, market decline would cause overpayment of carries to the GP.
To prevent this from happening, most funds usually have clawback mechanisms through which the GP will return over-allocated carry payments at the point of liquidation of the fund. Escrow mechanisms also ensure withholding of carry percentages until the conclusion of fund operations.
Recycled Carry and Targeted Incentive Pools
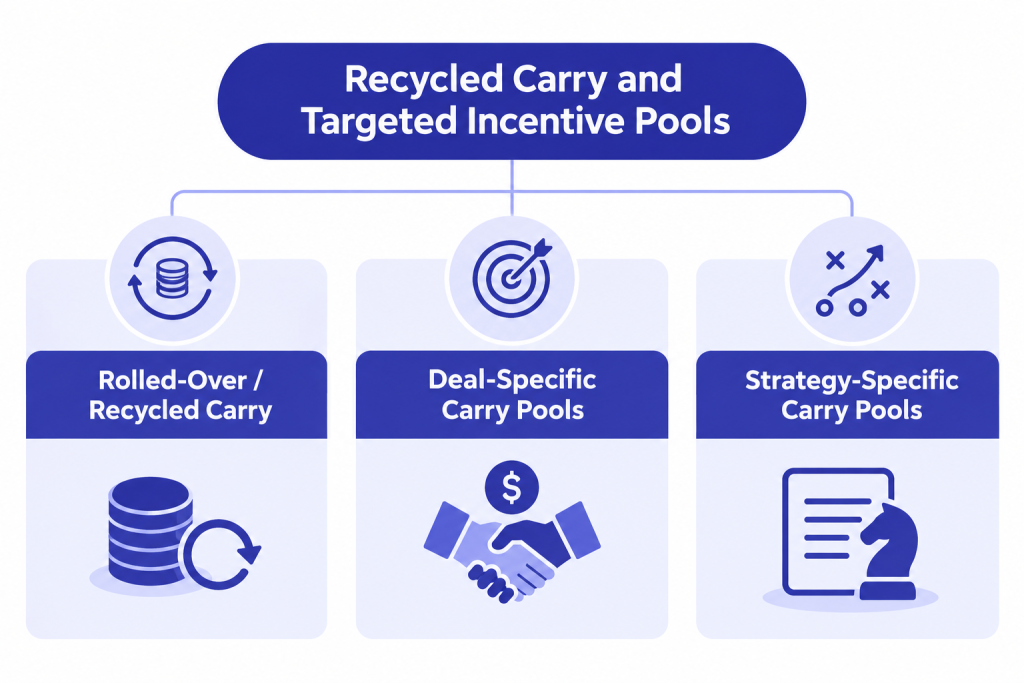
The key incentive models used in modern fund structures include:
- Rolled-Over / Recycled Carry: In GP-led continuation vehicles, managers have a choice to either roll over realized carry into the continuation vehicle to defer tax while aligning the interests of the GP with the newly added LPs.
- Deal-Specific Carry Pools: Used mostly in co-investment vehicles and pledge funds where performance incentive pool is allocated to the team managing a specific deal.
- Strategy-Specific Carry Pools: In multi-strategy vehicles, carry generated by real estate is separated from the one generated by credit or buyout.
LP Protection Mechanisms: Blended Waterfalls and Offset Clauses
LPs need certain structural provisions to protect themselves from premature or undue distribution of carried interest:
- Offset Clauses: The offset of the management fees against transaction fees, monitoring fees, and board fees (such as a 100% offset of these fees against management fees) ensures that other revenues earned by the GP automatically lower the fee cost for LPs.
- Blended Waterfalls: Blended provisions consider the economics of the entire portfolio, combining the realized cash returns and conservative valuation of the unrealized investments, before making interim distributions of carry interests.
- Clawback Guarantees & Escrow Accounts: A certain percentage of the GP carry interest distribution (usually between 20%-30%) is held in an escrow account until the completion of the fund’s final liquidation.
Legal Documentation: Drafting Bespoke Partnership Agreements
The translation of commercial carry arrangements into legal documents requires integration between several key documents as follows:
- Limited Partnership Agreement (LPA): Specifies the legal description of the distribution waterfall, hurdle rates, GP catch-up structure, clawback terms, and the LP advisory committee rights.
- Carry Plan & Partnership Documents: Covers the internal allocation of carry among the various GP partners, investment committee members, and deal teams.
- Management Agreement: Deals with the fee structure, the obligations of the managers, expense allocation, and management fees waterfall interaction.
- Award Letters: Covers individual carry allocation, vesting schedule, bad-leaver provisions, and restrictive covenants for the team members.
- Investor Communications: Quarterly and annual financial reporting requires that the waterfall calculation be presented clearly, in line with LPA definitions.
Frequently Asked Questions
What is carried interest in a private fund?
Carried interest is the percentage of net gains that is earned by a General Partner (GP) in a fund, which is usually 20% after all the money contributed by the LPs is returned with their preferred rate.
How does a fund distribution waterfall work?
It is the order of cash distribution made from the fund according to a legal document called a waterfall, which gives a sequence of allocations of capital to the recovery of LPs’ capital contributions, to preferred returns, to the GP’s catch-up, and to profit splits.
What is a preferred return or hurdle rate?
Preferred return (or hurdle rate) is the minimum annual percentage return on the contributed capital, which is usually 7%-8%.
What is a GP catch-up in a fund waterfall?
A GP catch-up is the tier of the waterfall where a larger percentage of net proceeds (usually 50%-100%) is allocated to the GP for it to earn its carry.
What is a GP-led continuation fund, and how does it affect carry?
GP-led continuation fund involves the transfer of portfolio investments from one expiring fund to a newly created one. The calculation of carry will vary depending on the rollover of LPs and valuation.
How does NAV affect carried interest calculations?
The Net Asset Value determines the valuation of unrealized assets. In an open-ended fund or in an interim accrual model, the value of NAV determines the theoretical carry entitlement before the realization of assets.
What is an offset clause in a fund agreement?
An offset in a fund agreement refers to the reduction of the management fee or the distribution of carry to the GP from the money the GP gets from transaction fees, advisory, or monitoring fees from the portfolio companies.
What is the difference between deal-by-deal and European waterfalls?
A European or whole-of-the-fund waterfall requires that the LPs are paid back all their money from the total amount in the fund before carry is paid out. A deal-by-deal or American waterfall calculates the carry per investment.
Structuring Global Investment Vehicles with Arnifi
Creating a modern fund structure involves harmonizing processes of legal formation, cross-border taxation issues, and compliance after legal formation.
Arnifi provides end-to-end global platform services designed to support fund managers and corporate sponsors in establishing bespoke investment vehicles:
- Global Investment Vehicle Structuring: Parallel fund structures, Master Feeder Structures, Continuation Vehicles and Co-Investment Platforms in alignment with the new distribution channels.
- Cross-Border Expertise: Set-up and administration of funds in popular foreign jurisdictions such as Cayman Islands, BVI, Luxembourg, UAE (ADGM/DIFC), Singapore.
- Post-Setup Compliance & Governance: Full service offering including regulatory reporting, corporate secretarial services, directors’ services, and statutory compliance.
No matter what you are looking for, a multi-strategy platform, GP-led continuation vehicle, or a bespoke multi-tiered waterfall, Arnifi will ensure that your business and legal infrastructure is in accordance with global standards.
References
- ILPA (Institutional Limited Partners Association): ILPA Principles & Waterfalls Best Practices
- Invest Europe: Professional Standards and Valuation Guidelines
- U.S. Securities and Exchange Commission (SEC): Private Fund Adviser Rules & Compliance Resources
- Alternative Investment Management Association (AIMA): Sound Practices for Alternative Investment Managers
Top UAE Packages


Related Articles
Top UAE Packages
Get in Touch