
Cyprus Tax Incentives for Businesses | Deductions, Exemptions and Reliefs
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: Cyprus has one of the most competitive tax rates in Europe at 15% coupled with an 80% Intellectual Property (IP) deduction, thus creating an effective tax rate of 3% for intellectual property profits of internationally growing companies.
Table of contents
- Introduction
- 1. Understanding Cyprus Corporate Tax Framework
- 2. Key Corporate Tax Exemptions for Businesses
- 3. Major Tax Deductions and Special Tax Regimes
- 4. Sector-Specific Tax Incentives in Cyprus
- 5. Structural Tax Reliefs and International Treaty Benefits
- 6. Personal Tax Incentives for Founders and Executives
- 7. How to Claim Cyprus Tax Incentives: Eligibility and Compliance
- 8. How Arnifi Helps Businesses Establish and Manage a Cyprus Company
- 9. Conclusion
- Frequently Asked Questions About Cyprus Tax Incentives
- References
Introduction
Cyprus is a prime business jurisdiction in the European Union that provides extremely beneficial corporate tax allowances, deductions, and exemption rules. The country combines an effective corporate structure with international treaties that promote international businesses, global holding structures, and technology companies.
Utilization of Cyprus tax advantages helps cross-border businesses to make the best out of international earnings without breaching any statutes. Some of the key tools include the participation exemptions, Intellectual Property (IP) Box scheme, Notional Interest Deduction, and Research and Development super-deduction schemes. Business leaders must evaluate statutory eligibility, substance demands, and compliance obligations prior to claiming benefits.
1. Understanding Cyprus Corporate Tax Framework
Taxation in Cyprus is based on an easy-to-understand system that helps attract foreign direct investment and promote sustainable business growth.
Cyprus Corporate Income Tax Rate
The corporate income tax rate in Cyprus is 15% by default. Such a system conforms to OECD Pillar Two and global minimum taxes, delivering long-term stability for cross-border operations.
Key Corporate Tax Reforms
Recent amendments in legislation have made corporate business easier and more flexible:
- Stamp Duty Abolition: The stamp duty on business transactions and company documents is abolished.
- Deemed Dividend Reform: Regulations related to deemed dividend distribution do not apply to corporate profits.
- Loss Carry-Forward: Corporate tax losses may be carried forward for 7 years.
- Group Relief Provisions: Losses of qualifying group companies may be used to reduce profits of other group companies.
2. Key Corporate Tax Exemptions for Businesses
A Cyprus business can be offered numerous corporate tax exemptions, thereby avoiding double taxation in international business operations.
Participation Exemption on Foreign Dividends
Dividends obtained by a Cyprus company that qualify are offered a corporate tax exemption of 100%. A Cyprus entity will have to have at least a 10% shareholding, meeting all anti-avoidance requirements.
Capital Gains Tax Exemption on Securities
Sale of qualifying securities, such as stocks, bonds, and debentures, is offered a 100% exemption on Capital Gains Tax. The Capital Gains Tax exemption does not apply to gains realized through immovable property located in Cyprus or property-rich companies.
Zero Outbound Withholding Tax
Cyprus imposes a withholding tax of 0% on outbound payments of dividends, interest, and royalties to foreign companies. In some cases, withholding tax exemptions do not apply to royalties that are utilized locally or payments that are remitted to blacklisted jurisdictions in the EU.
Foreign Permanent Establishment Exemption
Corporate taxes do not apply to profits earned from foreign permanent establishments located outside Cyprus. This mechanism allows multinational entities to expand abroad without increasing local tax burdens.
3. Major Tax Deductions and Special Tax Regimes
Special tax regimes allow corporations to reduce effective corporate tax liability through structural deductions.
Intellectual Property (IP) Box Regime
In the Cyprus IP Box system, there is an 80% tax deduction on IP profits. Qualifying assets include patents, copyrights on software, and proprietary technology. The 80% tax deduction, along with the 15% corporate tax, leads to an effective tax rate of up to 3%.
Research and Development (R&D) Super-Deduction
Businesses are entitled to claim a 120% tax deduction on qualifying expenditures made for R&D, which amounts to an additional 20% super-deduction. Eligible expenses are scientific research, software development, and technical innovation. The same asset cannot qualify for both IP box benefits and R&D super-deduction.
Notional Interest Deduction (NID)
A Notional Interest Deduction is allowed for companies that bring in fresh equity as a source of capital financing. NID is based on the reference interest rate for fresh equity. It allows an entity to offset up to 80% of its profits from taxes.
Loss Carry-Forward and Group Relief
The trading losses may be carried forward up to seven years in order to offset future profits. Group relief regulations enable losses for the year to be shared among 75% parent-subsidiary groups.
4. Sector-Specific Tax Incentives in Cyprus
Targeted incentives are provided in major national sectors in relation to investments in innovation, transport, and green energy.
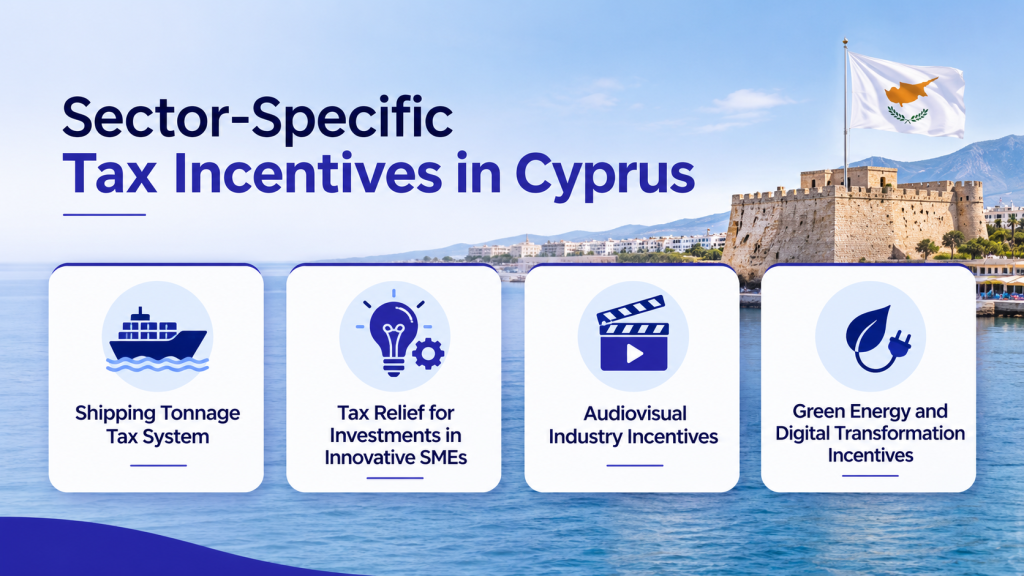
Shipping Tonnage Tax System
The owners, charterers, and ship managers of ships may avail themselves of the Tonnage Tax regime, which allows for payment of corporate income tax not to exceed 6% of total earnings derived from the ownership of the vessel based on net tonnage.
Tax Relief for Investments in Innovative SMEs
An individual investing in an approved innovative SME is eligible for tax deduction of up to 50% of his/her annual income tax chargeable amount. The tax incentive is subject to annual limits and a carry-forward period of five years.
Audiovisual Industry Incentives
Projects of films and television productions made in Cyprus are entitled to tax exemptions of up to 35% of eligible costs incurred in the production process. Unused deductions in the year of production may be carried forward for five years.
Green Energy and Digital Transformation Incentives
There is an enhanced tax deduction for investments in artificial intelligence, cloud computing, and blockchain technologies. Tax incentives also include accelerated depreciation of solar energy and wind energy equipment and Green Investment Tax Credits.
5. Structural Tax Reliefs and International Treaty Benefits
The Republic of Cyprus possesses favorable international structuring attributes through extensive tax agreements and adaptable corporate governance systems.
Cyprus Double Taxation Treaty Network
The Republic of Cyprus maintains over 65 double taxation treaties across the globe. Such an extensive treaty network helps avoid foreign withholding tax levies on dividends, interest, and royalty payments made to Cypriot companies.
Tax Benefits for Holding Companies
The presence of participation exemptions, zero capital gains from sale of securities, and zero withholding tax on outbound payments make Cyprus an attractive venue for global holding company structures.
Management, Control, and Economic Substance
To access treaty benefits and claim primary Cyprus tax incentives, entities must demonstrate local management and control. Companies require qualified resident directors, physical board meetings in Cyprus, and fully documented commercial decisions.
6. Personal Tax Incentives for Founders and Executives
Cyprus lures foreign executive personnel and entrepreneurs using customized personal tax policies.
Non-Domiciled Tax Status
Non-domiciled tax residents who meet eligibility requirements are provided with 17 years of exemption from Special Defense Contribution (SDC) for dividends and interest on passive income. This policy benefits international investors seeking relocation of their residence to Cyprus.
The 60-Day Tax Residency Rule
Tax residency can be acquired by spending only 60 days in Cyprus each year. The applicant must own a residential property, operate a local business or have employment there, and not spend more than 183 days in any other particular country.
Personal Income Tax Exemption for High-Earning Executives
Foreign executives choosing to work in Cyprus receive a 50% exemption from personal income tax. This provision applies to foreign workers earning above €55,000 per annum for the first time.
7. How to Claim Cyprus Tax Incentives: Eligibility and Compliance
Obtaining tax breaks in Cyprus involves stringent compliance with financial reporting requirements.
Understanding Eligibility Requirements
A statutory tax break comes with its own set of eligibility criteria. The exact nature of activities, share structure, and cost heads need to be looked into prior to availing any tax deduction.
Documentation and Financial Records
Detailed accounting information needs to be maintained in order to claim such tax breaks. Documentation has to prove expenditure on R&D, IP creation, equity investments, and capital expenditures.
Annual Tax Filings and Corporate Compliance
In order to retain tax breaks, one will have to file the annual corporate returns and VAT returns. In addition, audited financial statements will be required. Non-compliance or missed deadlines can invalidate statutory incentive access.
8. How Arnifi Helps Businesses Establish and Manage a Cyprus Company
Arnifi provides comprehensive company formation, tax compliance, and structuring services for foreign investments in Cyprus.
Cyprus Company Formation and Corporate Structuring
Arnifi works through all aspects of your new entity formation. We advise on the establishment of trading, holding companies, and intellectual property management companies for increased operational efficiency.
Accounting, Tax, and VAT Support
Arnifi provides bookkeeping services, VAT registration, annual statutory audits, and corporate filings. Well-organized accounting will ensure that your business is fully able to take advantage of all possible tax incentives in Cyprus.
Corporate Banking and Cross-Border Transactions
Arnifi helps with international corporate banking setup. We facilitate merchant services integration, multi-currency corporate accounts, and cross-border banking regulations.
Ongoing Compliance and Substance Support
Arnifi assists businesses with substance requirements by organizing local governance, administration, and secretarial services.
Arni AI Tools for Business Setup
- Arni Organogram: Map out visual corporate ownership structures.
- Arni Cost Calculator: Estimate initial formation costs and ongoing administration expenses.
- Arnifi Docs: Generate customized legal contracts and corporate governance paperwork.
- Arni AML Screener: Perform rapid background checks and regulatory compliance screening.
9. Conclusion
Cyprus is still considered one of the most efficient corporate jurisdictions, as it provides the following tax reliefs: 15% corporate tax, strong participation exemptions, and 3% effective IP Box tax. Nevertheless, the use of tax relief benefits necessitates proper corporate structuring, presence of substance, and effective financial management.
Businesses should assess operational goals and eligibility before setting up local entities. Contact Arnifi today to start your Cyprus entity registration and streamline your compliance requirements. You can also explore our Arnifi Corporate Structuring Solutions or use our online Arnifi Business Setup Calculator to launch your global expansion smoothly.
Frequently Asked Questions About Cyprus Tax Incentives
What are the main tax incentives available to businesses in Cyprus?
These are a 15% corporate tax rate, an 80% IP Box deduction, a 120% R&D super-deduction, a Notional Interest Deduction, and participation exemption for foreign dividends.
What is the corporate tax rate in Cyprus in 2026?
The standard corporate income tax rate in Cyprus is 15%.
Are foreign dividends tax-exempt in Cyprus?
Yes, dividends paid by foreign subsidiaries are fully exempt from corporate income tax when received by a tax resident entity.
How does the Cyprus IP Box regime work?
IP Box offers 80% tax deduction of qualifying profits from IP, which lowers the effective tax rate to 3%.
What is the R&D super-deduction in Cyprus?
It provides a deduction of 120% of qualifying costs of research and development.
How does the Notional Interest Deduction reduce corporate tax?
NID grants a tax deduction on new equity introduced into a business, offsetting up to 80% of taxable profits.
Are capital gains from the sale of shares taxable in Cyprus?
No, capital gains from the sale of shares and qualifying securities are fully exempt, unless tied to Cyprus real estate.
Does Cyprus impose withholding tax on dividends paid abroad?
No, Cyprus levies a 0% withholding tax on outbound dividend, interest, and royalty payments to non-residents.
What tax incentives are available for innovative businesses in Cyprus?
There are R&D super-deductions, IP box, and investor tax reliefs for financing innovative enterprises.
How can a foreign company qualify for Cyprus tax incentives?
The foreign business should create a tax resident enterprise or branch in Cyprus and meet all the conditions for the presence of sufficient substance.
What are the substance requirements for a Cyprus holding company?
Sufficient substance means the presence of resident directors, holding of local meetings of the board of directors, presence of an operational office, and decision-making in Cyprus.
How can Arnifi help with Cyprus company formation and tax compliance?
Arnifi takes care of the incorporation of your entity, its registration, accounting, VAT reporting, and governance.
References
- Cyprus Tax Department (Ministry of Finance): https://www.mof.gov.cy/tax
- Invest Cyprus (National Investment Promotion Agency): https://www.investcyprus.org.cy/
- PwC Cyprus Tax Summaries: https://taxsummaries.pwc.com/cyprus
Top UAE Packages
Related Articles
Top UAE Packages
Planning Your Next Business Move?
