
The Ultimate Guide to Setting Up a Cyprus Holding Company | Requirements in 2026
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: The Cyprus Holding Company provides a 100% participation exemption on foreign dividends and share disposals to international business groups with an attractive corporate tax rate of 15% in the 2026 tax system.
Table of contents
- What Is a Cyprus Holding Company and Why Use One?
- Cyprus Holding Company Tax Benefits Under the 2026 Corporate Tax Reform
- Economic Substance, Governance and Double Tax Treaty Access
- Cyprus Holding Company Exit Planning and Non-Dom Tax Benefits
- How to Set Up a Cyprus Holding Company: Step-by-Step Process
- Cyprus Holding Company Compliance Calendar and Ongoing Obligations
- How Arnifi Helps You Set Up and Manage a Cyprus Holding Company
- Conclusion
- FAQs
What Is a Cyprus Holding Company and Why Use One?
A Cyprus structure provides flexible corporate legal structures for international holding of investments.
Legal Definition of a Cyprus Holding Company
A Cyprus holding company is a regular private limited company registered according to the Cyprus Companies Law (Cap. 113). The structure does not operate under any specialized legal regime or offshore classification. The structure operates as a typical resident company enjoying corporate tax exemptions.
Key Functions of a Cyprus Holding Structure
- Subsidiary Consolidation: It owns shares in multiple operating subsidiaries abroad in a consolidated ownership structure.
- Asset Protection: It segregates assets, intellectual property rights, and real estate from operating liabilities.
- Intra-Group Financing: It serves as a centralized treasury function for transferring funds and loans among subsidiaries.
- Governance Streamlining: It streamlines corporate governance, succession, and equity distribution for the group.
Who Should Consider a Cyprus Holding Company?
Foreign founders, venture capital firms, business groups, and high-net-worth individuals considering expansion in multiple jurisdictions can benefit from a Cyprus holding company structure.
Cyprus Holding Company Tax Benefits Under the 2026 Corporate Tax Reform
Tax Reform of 2026 revised the Cyprus tax policies and ensured investment inducements were not undermined.
Cyprus Corporate Income Tax Rate in 2026
The standard corporate income tax rate set by Cyprus is 15% on net taxable profits. Foreign trade income, domestic rental income, and interest income, apart from ordinary business transactions, will attract standard taxation.
Participation Exemption on Foreign Dividends
- 100% Tax Exemption: Dividends earned from foreign sources by a Cyprus holding company enjoy full tax exemption, including special defense contribution (SDC).
- Anti-Abuse Safeguards: The tax exemption applies as long as the foreign payer firm does not earn more than 50% passive income and is taxed at not less than 6% overseas.
Capital Gains Tax Exemption on Share Disposals
- Qualifying Sales: Profits from disposing of shares, securities, and debentures are completely exempt from Cyprus capital gains tax.
- Real Estate Exception: Shares in firms which hold real estate in Cyprus are taxable under Cyprus capital gains tax.
Zero Withholding Tax on Outbound Dividends
- Non-Resident Distributions: Dividends distributed to non-residents are taxed at a 0% withholding rate.
- Defensive Tax Measures: A withholding tax of 5% to 17% is charged solely on payments made to companies located in low-tax jurisdictions or countries blacklisted by the EU.
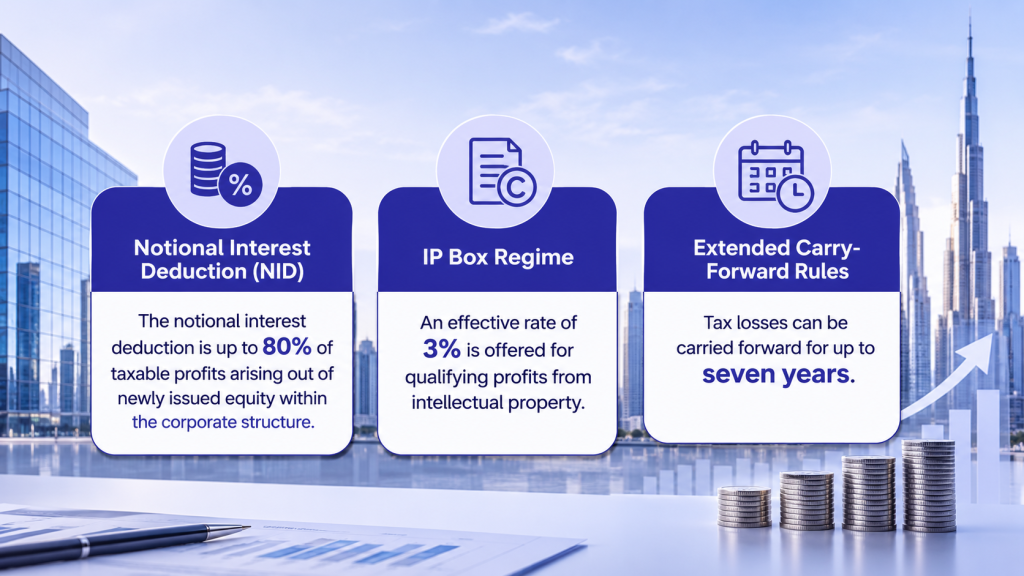
Additional Tax Incentives for Holding Companies
Economic Substance, Governance and Double Tax Treaty Access
Substance and local governance are needed for international tax advantages and bank account opening.
Establishing Cyprus Tax Residency
Local tax residency is achieved when an entity’s management and control happen in Cyprus. A majority-resident board of directors needs to hold physical board meetings in Cyprus to make decisions.
Economic Substance Requirements for Holding Companies
In order to meet international banking standards and European Union (EU) tax requirements, it is necessary for the holding structure to have a physical presence, records management, executive management, and bank account activity in Cyprus.
Understanding ATAD, CFC Rules and the MLI Principal Purpose Test
The ATAD and CFC rules make sure that there is no manipulation and tax planning by shifting profits artificially. The benefit of the tax treaty should have commercial substance, not just tax planning purposes.
Constructive Dividends and Anti-Avoidance Considerations
Non-commercial dealings, transfer pricing problems, and intra-group loans that do not follow arm’s length principles may be classified as constructive dividends.
Cyprus Holding Company Exit Planning and Non-Dom Tax Benefits
Exit strategies become easy for foreign founders thanks to holding companies.
Why Holding Structures Matter for Business Exits
The formation of a core company enables the founders to sell off their shares without untangling complicated business agreements in various countries.
Capital Gains Tax Planning for Share Disposals
Transferring subsidiary shares via a Cyprus-based company will not expose the profits made to capital gains tax. Such tax-free gains can be used anywhere.
Cyprus Non-Domiciled Tax Status for Founders
- 17-Year SDC Exemption: Foreign entrepreneurs relocating to Cyprus gain Non-Domiciled (Non-Dom) status, exempting personal dividend income from Special Defence Contribution for 17 years.
- Healthcare Capped Charges: Non-Dom residents pay only a 2.65% healthcare contribution on dividend distributions, capped at €4,770 annually.
How to Set Up a Cyprus Holding Company: Step-by-Step Process
Incorporation entails consecutive filings of regulatory documentation via official registries.
Step 1: Choose and Reserve a Company Name
Proposed corporate names need to be filed with the Cyprus Registrar of Companies for registration.
Step 2: Draft the Memorandum and Articles of Association
Prepare the company’s constitutional documents describing the holding company’s operations, class of share capital, and board governance guidelines with the help of local lawyers.
Step 3: Appoint Directors and a Company Secretary
Nominate residents as directors and a company secretary to gain operational control in Cyprus.
Step 4: Establish a Registered Office in Cyprus
Arrange an official office location within Cyprus where legal papers, correspondence with authorities, and documentation will be kept.
Step 5: Complete Company Incorporation
Filing of documents with the Registrar of Companies will result in obtaining a Certificate of Incorporation.
Step 6: Register for Tax and UBO Reporting
A TIC number should be obtained, and ultimate beneficial owners should be registered in the Central UBO Register.
Step 7: Open a Corporate Bank Account
Pass anti-money laundering procedures to open bank accounts with European/international banks.
Cyprus Holding Company Compliance Calendar and Ongoing Obligations
Compliance ensures continuous operation of corporate entities and compliance with local laws.
Annual Financial Statements and Audit Requirements
All enterprises should keep their records, produce financial statements according to IFRS, and conduct the annual audit by a licensed Cyprus auditor.
Corporate Tax Filing and Provisional Tax Payments
Provisional payments of corporation tax in equal parts are paid on July 31 and December 31. Income tax return should be filed electronically before the annual statutory deadline.
Annual Registrar and UBO Compliance
Companies should file their Annual Return (HE32 form) at the Registrar of Companies and update their beneficial ownership information in the UBO register annually.
Tax Loss Carry-Forward Rules
As per existing taxation laws, all operating and trading losses qualify for carry-forward during the seven years.
Common Compliance Mistakes to Avoid
Not having board meetings of resident directors, not updating UBO information on time, lack of physical substance, and non-compliance with annual statutory audits lead to sanctions and tax residence issues.
How Arnifi Helps You Set Up and Manage a Cyprus Holding Company
Arnifi facilitates corporate activities across multiple jurisdictions by leveraging technology for setup and compliance.
End-to-End Cyprus Company Formation
Arnifi facilitates the process of registration, legal setup, and structuring of the business entity for your international presence.
Post-Setup Compliance, Accounting and Legal Support
Arnifi offers continuous services such as tax compliance, accounting services, auditing, and corporate secretarial services.
Corporate Banking and Global Expansion Support
Arnifi assists founders with corporate bank account onboarding, compliance documentation, and resident visa applications.
Expand Internationally with Arnifi HR
Arnifi assists the founders of companies with opening corporate bank accounts, compliance documents, and the visa application process.
Simplify Holding Structures with Arnifi’s Digital Tools
- Arni Organogram: Visualize and manage complex ownership hierarchies digitally.
- Arni Cost Calculator: Calculate precise incorporation and operational fees upfront.
- Arni AML Checker: Conduct instant background and compliance checks.
- Arni Docs: Generate, execute, and archive corporate legal documents securely.
Conclusion
The Cyprus holding company provides unparalleled structural flexibility, the benefit of a 15% corporate tax regime, and a generous dividend exemption system for developing international companies. The appropriate economic substance and adherence to the annual reporting requirements guarantee the safety and treaty protection of assets. The global promoters must carefully examine their ownership expectations prior to selecting their jurisdiction of incorporation.
FAQs
1. What is the standard corporate tax rate for a Cyprus holding company in 2026?
The standard corporate income tax rate in Cyprus is 15% on net taxable profits.
2. Are foreign dividends taxable in Cyprus?
Foreign dividends received by the holding company are completely exempt from Cyprus taxation and SDC, provided there are no tax abuse conditions.
3. Does Cyprus charge withholding tax on dividends paid to foreign owners?
Cyprus applies 0% withholding tax on dividends distributed abroad to non-residents, individuals and companies.
4. Are share sale profits subject to capital gains tax in Cyprus?
Profits from the sale of eligible shares or securities are not taxable, provided that the underlying company does not have immovable property in Cyprus.
5. How long does it take to register a holding entity in Cyprus?
It normally takes 8 to 12 business days to incorporate a holding company in Cyprus after submission of the necessary documents.
6. What are the key tax deadlines for provisional payments?
Provisional corporate tax payments must be paid in two installments on July 31 and December 31.
7. How long can tax losses carry forward under Cyprus tax rules?
Tax losses can be carried forward to offset future taxable profits for up to seven tax years.
References
Top UAE Packages
Related Articles
Top UAE Packages
Planning Your Next Business Move?
