
UAE VAT on Services Provided Outside UAE | 0%, 5%, or Out of Scope?
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: Zero-rating is treated as a tax concession; the UAE business bears 100% of the burden of proving the client was outside the UAE during performance.
Table of contents
- Does UAE VAT Apply to Services Provided Outside the UAE?
- UAE VAT Treatment of Services Outside the UAE
- What Is Out-of-Scope VAT in the UAE?
- Zero-Rated vs Out-of-Scope vs Exempt vs 5% VAT
- What Is the Place of Supply for Services Under UAE VAT?
- When Can Services Provided to Foreign Customers Be Zero-Rated?
- Article 31 and Export of Services Under UAE VAT
- When Does 5% UAE VAT Apply to Services Provided to Foreign Customers?
- What If a UAE Business Buys Services From a Foreign Supplier?
- VAT on Services Provided to GCC Countries
- Does Free Zone Status Change VAT on Services Outside UAE?
- Practical UAE VAT Examples for Services Outside the UAE
- UAE VAT Cross-Border Services Scenario Matrix
- How to Invoice Foreign Clients Without Charging UAE VAT?
- What Documents Should You Keep for Zero-Rated Export Services?
- How to Report Cross-Border Services in a UAE VAT Return
- Common Mistakes When Applying UAE VAT to Overseas Services
- UAE VAT Compliance Checklist for Cross-Border Services
- Latest UAE VAT Updates Affecting Exported Services
- Frequently Asked Questions
- References
The VAT applicable to services provided outside the UAE will determine the taxation of cross-border business as 5% taxable, 0% zero-rated, or out-of-scope services.
Tax classification for cross-border services must be accurate to prevent substantial financial penalties that will be imposed by the FTA. Business executives should consider factors other than the billing address of the invoice in order to assess the location of the performance, resident of the customer’s residence, and the benefits derived from the transaction.
Does UAE VAT Apply to Services Provided Outside the UAE?
Yes, UAE VAT is applied to cross-border services, but the applicable rate differs (5%, 0%, or Out of Scope) based on Place of Supply, the client’s place of business, and where the benefits are used.
- 0% (Zero-Rated): Cross-border services when the foreign customer does not have an establishment in the UAE, when the service is performed outside of the UAE, and it is not related to UAE real estate or assets.
- Out of Scope: Cross-border services when all service activities are performed in a non-UAE place and are not connected with a business or establishment in the UAE.
- 5% (Standard Rate): Cross-border services that are performed for foreign customers when the benefit of the service, its physical use, or the related asset is in the UAE.
UAE VAT Treatment of Services Outside the UAE
As per the VAT Law of the UAE (Federal Decree-Law No. 8 of 2017 on Value Added Tax), any transaction having an international dimension will be subject to the following four methods of taxation:
- Standard Rated (5%): In case the place of supply is within the UAE and zero-rated conditions are not satisfied.
- Zero-Rated (0%): The taxable supply having the rate of 0%. It allows the recoverability of total input tax on the cost of doing business.
- Exempt: Certain types (residential property, some financial services, etc.) which are not subject to VAT and are non-recoverable.
- Out of Scope: The transactions falling outside the geographic jurisdiction of UAE VAT legislation. No VAT will apply and will not form part of local taxable turnover.
What Is Out-of-Scope VAT in the UAE?
Out-of-Scope VAT is used when there is a service that has a Place of Supply outside the UAE.
This service will generate no VAT liability in the UAE, and there is no need for any local VAT collection on the customer’s invoice. The out-of-scope turnover will not be taken into consideration when it comes to the VAT registration threshold for VAT registration purposes.
Zero-Rated vs Out-of-Scope vs Exempt vs 5% VAT
| VAT Classification | VAT Rate | Place of Supply | Input VAT Recovery | Invoicing Requirement |
| Standard-Rated | 5% | Inside UAE | Recoverable | Tax Invoice showing 5% VAT |
| Zero-Rated | 0% | Inside UAE (special rule) | Recoverable | Tax Invoice showing 0% VAT |
| Exempt | 0% (No tax) | Inside UAE | Not Recoverable | Commercial/Tax Invoice (Exempt) |
| Out of Scope | N/A | Outside UAE | Conditionally Recoverable* | Commercial Invoice (No VAT) |
*Input VAT on out-of-scope supplies can be recovered if the supply would have been taxable (or zero-rated) had it been performed within the UAE.
What Is the Place of Supply for Services Under UAE VAT?
The default rule for the place of Supply of services shall be the Place of Residence of the Supplier (Article 29). Nevertheless, Article 30 contains significant exceptions to the rule:
Business-to-Business (B2B) vs. Business-to-Consumer (B2C)
- B2B Imports: Reverse Charge Mechanism (RCM) is applicable; the place of supply becomes the country of the recipient.
- B2C Services: Normally, the place of supply will be the place of the supplier unless specified otherwise (telecommunications services and other electronic supply).
Special Place of Supply Exceptions (Article 30)
- Real Estate Services: Place where the real estate is situated.
- Means of Transport Leasing: Place where the transport is made available to the recipient.
- Restaurant, Hotel, Cultural, Catering Services: Place where performed physically.
- Services Related to Movable Assets: Place where such services are performed physically.
When Can Services Provided to Foreign Customers Be Zero-Rated?
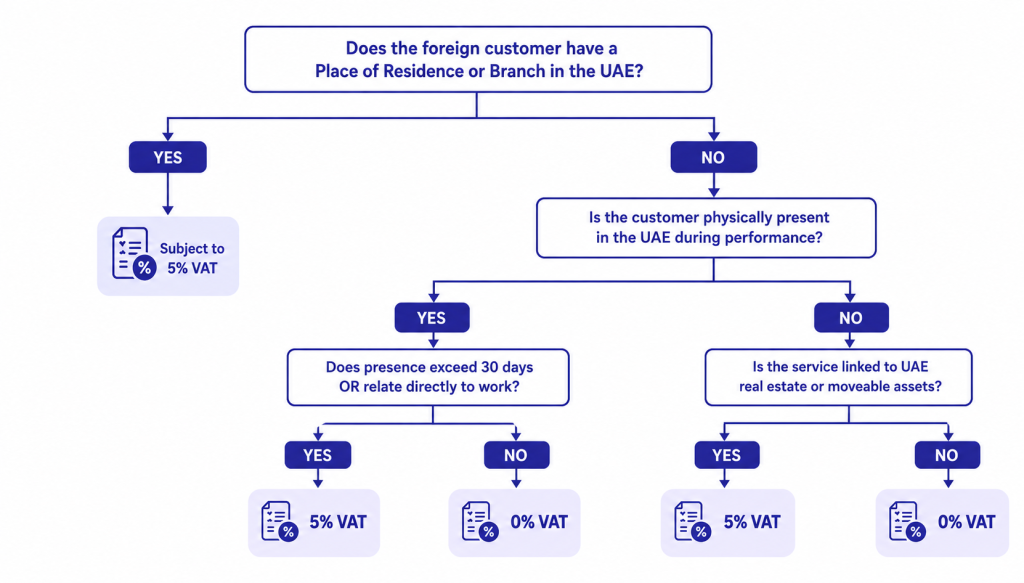
Exported services to foreign entities qualify for a 0% VAT rate when specific conditions under Executive Regulations are met.
Article 31 and Export of Services Under UAE VAT
All the following criteria must be met for Article 31(1)(a) of the Executive Regulations to classify the export of services as zero-rated:
- Non-Resident Recipient: The customer should not be residing in or have a fixed place of business in the UAE.
- Outside the State: The customer should be outside the UAE at the time of rendering of the services.
- No Direct Asset Link: The services rendered should NOT be in direct connection with real estate or movable property in the UAE.
- Not Covered by Article 30 Special Rules: The service should not come within the purview of special cases described in Article 30.
The “30-Day Rule” (Article 31(2))
A customer is considered “outside the UAE” if their physical presence in the country is:
- Less than 30 consecutive days, AND
- Not effectively connected with the supply of the service.
When Does 5% UAE VAT Apply to Services Provided to Foreign Customers?
Foreign customers have to pay the standard 5% UAE VAT if their services are directly related to assets or facilities in the local market.
The standard rate applies if the services relate to UAE property, including any architectural design of local buildings. Any service rendered on tangible goods or movable assets located within the UAE attracts 5% VAT. Services that are rendered to foreign customers if their local branch within the UAE accepts or directs the service do not qualify for zero-rating.
What If a UAE Business Buys Services From a Foreign Supplier?
When the UAE-registered company imports services from a foreign service provider, for example, from a US company in terms of software and marketing, then the Reverse Charge Mechanism (RCM) will be applicable:
- The foreign supplier invoices without any UAE VAT being charged.
- The UAE company calculates the 5% output VAT.
- The UAE company is also allowed to recover the 5% input VAT.
- Cash flow effect: No cash flow impact.
VAT on Services Provided to GCC Countries
The UAE VAT Law makes mention of “Implementing States” regarding GCC transactions, but from 2026 onward, any transactions conducted with GCC nations will be treated according to general export guidelines until the GCC VAT system is officially accepted through FTA.
- B2B Services to GCC (e.g., KSA, Oman): Considered as exports of services based on Article 31. Zero-rated at 0% if criteria are met.
- B2C Services to GCC: Considered either as standard exports or place-of-supply-specific, depending on consumption.
Does Free Zone Status Change VAT on Services Outside UAE?
Designated Free Zones (DFZs) receive special treatment primarily for goods. For services, DFZ entities follow standard UAE VAT rules:
- Services supplied by a Free Zone company to an overseas client follow Article 31 export rules (0% or out of Scope).
- Services provided between two Designated Zone companies are generally subject to 5% VAT unless explicitly treated as zero-rated under statutory rules.
Practical UAE VAT Examples for Services Outside the UAE
| Scenario | Tax Treatment | Key Statutory Rationale |
| Dubai IT firm selling SaaS to US business | 0% Zero-Rated | Recipient has no UAE residence or branch and is located outside the UAE (Art. 31(1)(a)). |
| UAE company buying Google Ads (US) | Reverse Charge Mechanism (RCM) | Import of services by a UAE business; recipient self-assesses 5% Output VAT and recovers 5% Input VAT (if eligible). |
| Consulting to a UK client for a Dubai property | 5% Standard Rated | Directly connected to real estate located in the UAE (Art. 30(7) / Art. 31(1)(a)). |
| Local engineering firm repairing equipment in Germany | Out of Scope | Physical performance on tangible assets takes place entirely outside the UAE. |
| Marketing services for a foreign company with a local Dubai branch | 5% Standard Rated | The UAE fixed establishment directly receives or benefits from the services. |
| Legal services for a French client whose executive attends meetings in Dubai | 5% Standard Rated | The recipient’s representative is physically present in the UAE during performance and effectively connected to the service. |
| Online training course delivered to consumers globally | 0% Zero-Rated or Out of Scope | Qualified export of services or non-UAE place of use/performance depending on B2C telecommunication/electronic service rules. |
| Architectural design for a resort in Oman supplied to an Omani firm | 0% Zero-Rated | Services are linked to real estate located outside the UAE, meeting export requirements (Art. 31). |
| Event management hosted in Dubai for a foreign corporation | 5% Standard Rated | Place of supply is the UAE as the event is physically performed in the State (Art. 30(6)). |
| Financial advisory by an Abu Dhabi firm to a Singapore fund | 0% Zero-Rated | Meets Article 31 criteria for B2B service exports to a non-resident with no UAE presence. |
UAE VAT Cross-Border Services Scenario Matrix
| Service Type | Recipient Location | Physical Location of Service | VAT Treatment |
| Management Consulting | UK Entity (No UAE office) | Performed remotely from UAE | 0% Zero-Rated |
| Property Valuation | US Investor | Dubai, UAE | 5% Standard Rated |
| Equipment Maintenance | Saudi Arabia | Riyadh, KSA | Out of Scope |
| Software Licensing | US Vendor | UAE Business (Import) | 5% RCM |
| Staff Training | German Firm | Dubai (Client staff in UAE) | 5% Standard Rated |
How to Invoice Foreign Clients Without Charging UAE VAT?
Regarding invoices for billing 0% or out-of-scope services to overseas customers:
- Invoice Currency: In USD, EUR, or other currencies, but when issued by a UAE VAT-registered business, conversion into AED should follow official CBUAE exchange rates.
- Invoice Mandatory Fields:
- Title: “Tax Invoice” (for 0% supplies)
- Name, address and TRN of Supplier.
- Name and overseas address of Recipient.
- 0% rate must be stated explicitly (or “Out of Scope”)
- Explanation of 0%: “Article 31 of UAE VAT Executive Regulations”.
What Documents Should You Keep for Zero-Rated Export Services?
In the case of an FTA audit, the onus of proof lies with the supplier. The following documents need to be kept:
- Service Contracts & Agreements: Detailing the scope, customer, and destination.
- Proof of Customer Location: Certificate of Incorporation, foreign tax registration, or overseas office address.
- Delivery Confirmation: Emails evidencing deliverables, time sheets, and IP activity proving remote delivery.
- Payment Evidence: Bank SWIFT indicating receipt of funds transferred from an overseas bank account.
How to Report Cross-Border Services in a UAE VAT Return
Inside the EmaraTax portal, cross-border transactions are entered in Form VAT201:
- Box 1 (Standard Rated Supplies): Report services that failed Article 31 criteria (charged at 5%).
- Box 2 (Taxable Supplies to GCC): Currently reported as zero-rated exports until GCC integration.
- Box 5 (Zero-Rated Supplies): Report qualifying Article 31 service exports.
- Box 9 (Imports under RCM): Report imported services subject to Reverse Charge.
- Box 10 (Input VAT Recovery): Reclaim input VAT on RCM imports.
Common Mistakes When Applying UAE VAT to Overseas Services
- Assuming foreign billing = automatic 0% VAT: Without considering the presence of a local branch or benefit to the local project.
- Missing proof of non-residence: Without obtaining any paperwork relating to overseas business operations.
- Misclassifying real estate services: Applying 0% VAT on Dubai real estate consultancy for foreigners.
- Ignoring short-term presence: When clients’ representatives participate in UAE-based training programs related to the deliverable.
- Missing Reverse Charge Mechanism Entry: Not self-assessing 0% VAT on import of software subscription.
UAE VAT Compliance Checklist for Cross-Border Services
Following a systematic verification process ensures complete tax adherence across all international service agreements.
- Verify the client lacks a permanent establishment or registered branch in the UAE.
- Confirm client representatives remained outside the UAE during service execution.
- Ensure deliverables do not connect to UAE real estate or local physical goods.
- Convert all foreign invoice currency amounts using official Central Bank exchange rates.
- Archive contracts, foreign business licenses, and SWIFT payment receipts in audit files.
Latest UAE VAT Updates Affecting Exported Services
The amendments introduced by the cabinet in the Article 31 provisions on regulations made things stricter when it comes to services that are considered to be provided within the UAE. Services associated with local performance, local installation, or local enjoyment cannot be considered for zero-rating since they will always be taxed at a rate of 5%.
Frequently Asked Questions
Is VAT charged on services provided outside the UAE?
Normally not. If the service is provided outside the UAE, then the service is Out of Scope or Zero-Rated (0%) provided that the criteria in Article 31 are fulfilled.
Are services provided to foreign clients zero-rated?
Yes, provided that the customer has no presence in the UAE, is outside the UAE during provision of the service, and the service is not provided to UAE real estate or goods.
What is out-of-scope VAT in the UAE?
Out-of-scope VAT covers supplies whose Place of Supply is completely outside the UAE such that UAE VAT laws have no jurisdiction on it.
What is the difference between zero-rated and out-of-scope VAT?
Zero-rated (0%) is within UAE VAT scope but taxed at 0% and with full input VAT recovery. Out-of-scope is out of the scope of UAE VAT.
Are services performed outside the UAE automatically zero-rated?
No. Provided that the service is related to UAE real estate, local assets, or to benefit the local branch, 5% VAT is applicable.
When does 5% VAT apply to a foreign customer?
If the service is used locally, associated with property/assets located in the UAE, or provided to the UAE branch of the foreign company.
Does a UAE branch of a foreign company change VAT treatment?
Yes, when the service is provided to or enjoyed by the UAE branch of the foreign company, then the foreign customer is viewed as a local individual who should pay a 5% VAT.
What is Article 31 of UAE VAT?
Article 31 of the VAT executive regulations provides the requirements that should be met in order to zero-rate exported services.
What is the 30-day rule for exported services?
If the physical presence of the foreign customer in the UAE during the supply period does not exceed 30 days, then he/she is regarded as “outside the UAE”.
Does VAT apply to consulting services provided to overseas clients?
Consulting delivered to foreign customers in remote mode is zero-rated (0%).
Does VAT apply to software services provided to foreign customers?
Software as a service (SaaS) and other remote software provided to non-residents outside of the UAE is zero-rated (0%).
Does VAT apply to services related to UAE property?
Yes. Services directly associated with property situated in the UAE are standard-rated (5%) at all times.
Does VAT apply to services related to goods located in the UAE?
Yes. Any services provided to movable goods in the UAE are standard-rated (5%).
How does reverse charge apply to imported services?
The customer will assess the Output VAT of 5% and the Input VAT of 5% in its VAT return.
How are zero-rated services reported in a UAE VAT return?
Zero-rated export services should be declared in box 5 of Form VAT201 in the EmaraTax system.
References
Federal Decree-Law No. 8 of 2017 on Value Added Tax
Cabinet Decision No. 52 of 2017 (Executive Regulations): Article 31 (Export of Services)
Top UAE Packages
Related Articles


Top UAE Packages
Planning Your Next Business Move?
