
VAT in Saudi Arabia: The Complete Business & Tax Compliance Guide
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: VAT (Value-Added Tax) in Saudi Arabia is a 15% tax administered by ZATCA. VAT in Saudi Arabia is mandatory for companies whose annual taxable sales exceed SAR 375,000, and it has implications on business incorporation, pricing, cash flow, and operations.
Table of contents
- Introduction
- What Is VAT in Saudi Arabia?
- VAT Registration in Saudi Arabia
- VAT Rates and Categories in Saudi Arabia
- Filing VAT Returns and Compliance
- Input VAT vs. Output VAT
- VAT Refunds and Adjustments
- VAT and Business Operations in KSA
- Strategic VAT Considerations for 2026–2027
- VAT Guidelines for Foreign Investors
- Recommended Compliance Roadmap for New Businesses
- How Arnifi Assists Foreign Enterprises
- Frequently Asked Questions
- Conclusion
- References
Introduction
VAT in Saudi Arabia plays an important role in the structure of the Kingdom’s economy. VAT was introduced as part of Saudi Arabia’s Vision 2030 reforms and ensures steady non-oil revenue generation to finance the development of public infrastructure, healthcare, and the education sector.
For international companies, growing enterprises, and local start-ups, VAT is not just another process of tax declaration, but also affects:
- Company Incorporation & Legal Setup: Coordination of the ZATCA registration process and Commercial Registration (CR).
- Pricing & Profit Margins: Decision-making on whether VAT expenses should be absorbed by the company or passed to the consumer.
- Cash Flow & Liquidity: Planning for the time lag between Output VAT collection and Input VAT recovery.
- Operational Readiness: Setting up the e-invoicing process and maintaining records to satisfy rigorous audit requirements.
Navigating tax compliance in KSA necessitates a well-thought-out strategy. Apart from the standard registration process and filings, companies must incorporate recent regulatory requirements like Wave 25 E-Invoicing requirements, 2025 restricted input regulations, digital platforms, and GCC tax agreements into their market entry strategy.
What Is VAT in Saudi Arabia?
Value Added Tax (VAT) is an indirect tax imposed on each stage of the value chain from the procurement of raw materials to the final sale at the retail level.
- Tax Mechanism: As companies pay and collect VAT at all production stages, the ultimate cost is borne by the final consumer.
- Implementation History: In KSA, VAT became effective on January 1, 2018, at 5%. As a strategy to help diversify and mitigate the effects of volatile oil revenues, the Saudi government raised the standard rate of VAT to 15% on July 1, 2020.
- Strategic Role: VAT offers sustainable non-oil revenue streams to help fuel growth and mega-projects in KSA under Vision 2030.
Knowledge about such mechanisms is critical for investors who construct financial models and enter into international business arrangements in the Kingdom.
VAT Registration in Saudi Arabia
ZATCA (Zakat, Tax and Customs Authority) establishes clear financial thresholds determining when a company must register for VAT.
| Registration Type | Annual Taxable Turnover Threshold | Strategic Action |
| Mandatory Registration | Exceeds SAR 375,000 | Required by law; failure to register incurs administrative fines. |
| Voluntary Registration | Between SAR 187,500 and SAR 375,000 | Recommended for startups with high initial capital expenditure to reclaim Input VAT on setup costs. |
Strategic Note: Companies must assess their expected taxable sales when formulating a market entry plan. Early registration helps companies offset the huge initial VAT payments on office rentals, equipment purchases, and consulting fees.
Step-by-Step ZATCA Registration Process
- Create a ZATCA Account: Create your account on the official ZATCA website and access the VAT registration section of the portal.
- Complete the Application Form: Fill out all information on business profiles, tax identification, and expected taxable sales.
- Upload Mandatory Documents:
- Copy of Commercial Registration (CR)
- Financial statements/proof of expected taxable sales
- Bank account details in Saudi Arabia
- Details of authorized representative
- Obtain VAT Registration Certificate: After approval from ZATCA, collect your VAT registration certificate showing your unique 15-digit Tax Identification Number (TIN).
VAT Rates and Categories in Saudi Arabia
The VAT laws in Saudi Arabia divide goods and services into three VAT categories. It is vital to identify them to be able to protect the right to reclaim Input VAT.
1. Standard-Rated Supplies (15%)
It covers most commercial goods, electronic goods, services rendered, and retail sales in KSA.
2. Zero-Rated Supplies (0%)
Tax is charged at 0% while companies may still claim Input VAT paid on expenses incurred for these sales.
- Qualifying Supplies:
- Goods or services exports to countries other than the GCC zone
- International transport of passengers and goods
- Certain medicines and medical devices
- Certain higher education services and private healthcare services
3. Exempt Supplies (No VAT)
VAT is not charged on sales; however, companies cannot claim Input VAT paid on business overheads and production expenses relating to these sales.
- Qualifying Supplies:
- Certain financial services (e.g., margin lending, life insurance)
- Certain residential real estate leases/purchase (subject to RETT regulations)
Filing VAT Returns and Compliance
VAT returns have to be filed electronically through the ZATCA portal according to their annual sales.
Filing Schedule
Annual Revenue < SAR 40M ───► Quarterly Filing (Due last day of following month)
Annual Revenue > SAR 40M ───► Monthly Filing (Due last day of following month)
Core Compliance & Record-Keeping Rules
- Tax Invoices: Every sales invoice should contain a proper 15-digit VAT number, price, tax percentages, amount of taxes, and should adhere to ZATCA standards for electronic invoices.
- Record Retention: Accounting records, tax invoices, bank statements, and customs declarations should be stored safely for at least 6 years.
- Penalty Risks: Non-filing of returns, delayed payments or willful underreporting results in penalties in the form of either 5% to 25% of the unpaid tax or administrative fines.
Input VAT vs. Output VAT
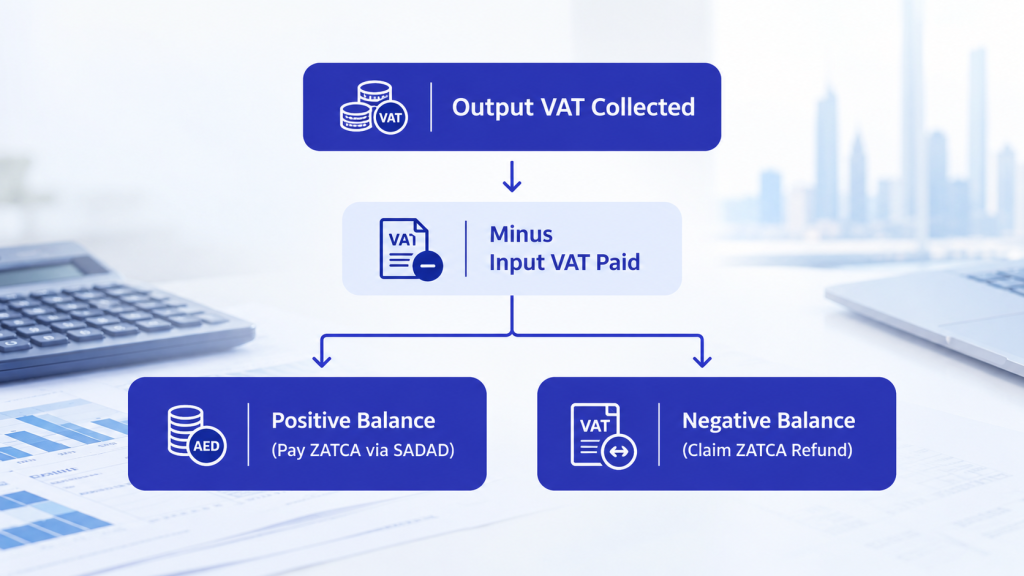
Calculating net tax liability depends on the difference between taxes received and taxes paid:
- Output VAT: 15% tax received by the company from its customers for sales of commercial items.
- Input VAT: 15% tax paid by the company to local vendors for the purchase of goods and capital assets.
When Input VAT Exceeds Output VAT
If business expenses and Input VAT exceed sales in a taxation period, then the negative balance means that your business has entered into a VAT Refund Position. The tax credit will either be carried forward, or you will directly apply for a refund through ZATCA.
VAT Refunds and Adjustments
Reclaiming VAT Refunds
Applicable organizations are eligible for refunds via their portal dashboard through ZATCA. It requires:
- Matching the digital records with the physical tax invoice.
- Provision of documentation related to clearance of customs for imported goods.
- Valid proof of payment for all invoices submitted by suppliers.
Foreign Business VAT Recovery
Foreign business entities that incur VAT liability without establishing permanent business establishments within the Kingdom of Saudi Arabia or making taxable supplies within the country are eligible for VAT Refunds according to special rules of ZATCA.
VAT and Business Operations in KSA
VAT integration into your operational framework will help avoid margin erosion and liquidity constraints:
- Pricing Strategy: Businesses need to determine whether the 15% tax rate should be absorbed in their current pricing structure or should be entirely passed on to customers.
- Working Capital Management: Late VAT payments by corporate clients can lead to cash flow problems since Output VAT needs to be paid to ZATCA even before the invoice is settled by the corporate client.
- ERP & Accounting Systems: Modern accounting systems will need to automatically break down the base amount, Output VAT, and recoverable Input VAT and generate ZATCA-compliant invoices.
- Tax Advisory Support: Smaller companies usually rely on outside tax advisors for tax-related services, but larger businesses have their internal tax departments.
Strategic VAT Considerations for 2026–2027
Entrant firms need to match their operational setup with the latest and future regulations:
1. Market-Entry Timing & Wave 25 E-Invoicing
Kingdom of Saudi Arabia is steadily progressing in its Phase 2 (Integrating Phase) E-Invoicing rollout (Fatoora).
- Wave 25 Deadline (1 February 2027): Target companies need to achieve system integration of their accounting software with ZATCA’s portal.
- Amnesty Periods: Businesses have an opportunity to use closing periods of amnesty to address any historical tax issues without fines.
- Execution Strategy: Coordinate your business registration, software purchases, and ZATCA API integration early in your business setup plan.
2. Restricted Input VAT & Digital Platform Obligations
- Restricted Input VAT Rules: New rules limit Input VAT refunds for certain types of employee perks, entertainment, and travel not used for business purposes.
- Online Marketplace (OMP) Obligations: Digital platforms and e-commerce providers active in KSA are deemed suppliers and should collect taxes from foreign sellers using their platforms.
3. GCC Unified VAT Agreement Developments
Developments related to the GCC Unified VAT Agreement have implications on cross-border supply chains, regional trade agreements, and regional headquarters (RHQ) set-ups:
- Inter-GCC Trade: Proper paperwork is needed for goods that are moving between GCC countries to preserve their zero-rating status or use reverse charge systems.
- Contract Design: Organize cross-border intercompany services and visa-dependent RHQ operations to prevent double taxation in GCC countries.
VAT Guidelines for Foreign Investors
1. Verify mandatory threshold vs voluntary option
2. Map local domestic sales vs zero-rated exports
3. Review input VAT recovery and non-deductible items
4. Implement ZATCA Phase 2-compliant e-invoicing software
5. Structure GCC cross-border intercompany contracts
6. Establish a ZATCA tax calendar and filing schedule
The foreign firms operating within KSA should consider the tax regulations that apply to all avenues generating revenue. Sales within the country will be charged a regular tax rate of 15%, while qualified exports will qualify for a zero rate of 0%. The use of such regulations involves transport and customs paperwork.
Recommended Compliance Roadmap for New Businesses
Follow this sequential roadmap to ensure full tax compliance during market entry:
Step 1: Assess Taxable Activities & Turnover
Step 2: Determine VAT Registration Requirement (Mandatory vs. Voluntary)
Step 3: Complete ZATCA Registration & Obtain VAT Certificate
Step 4: Configure Accounting & ZATCA-Compliant E-Invoicing Systems
Step 5: Establish Input / Output VAT Tracking Workflows
Step 6: Prepare & Submit Timely VAT Returns via ZATCA Portal
Step 7: Monitor Tax Refunds, Audit Adjustments & Regulatory Updates
How Arnifi Assists Foreign Enterprises
Expert advice and an understanding of the dynamic taxation system in Saudi Arabia are essential. Arnifi offers full-scale services and expertise for corporate setup and taxation compliance that will help your business grow:
- ZATCA Registration & Onboarding: Rapid setting up of your CR number, tax registration, and VAT certification.
- VAT Return Filing & Advisory: Managing monthly/quarterly filings, reviewing input tax recovery options, and avoiding penalties.
- E-Invoicing Systems Implementation: Implementation of accounting systems in line with ZATCA phase two requirements.
- Cross-Border Tax Structuring: Optimizing GCC intercompany service structures, Regional Headquarters (RHQ) compliance, and supply chain tax efficiency.
Frequently Asked Questions
What is VAT in Saudi Arabia?
VAT (Value-Added Tax) in KSA is an indirect consumption tax applied at 15% on the majority of commercial products and services in each supply chain stage.
What is the standard VAT rate in Saudi Arabia?
The standard VAT rate in Saudi Arabia is 15%, and it is applicable from July 1, 2020.
Who needs to register for VAT in Saudi Arabia?
Every company in KSA that makes taxable supplies above SAR 375,000 in one year should be registered at ZATCA. Non-resident companies in KSA making taxable supplies need to register at ZATCA irrespective of their turnover.
What is the VAT registration threshold in Saudi Arabia?
The mandatory registration threshold is SAR 375,000, and the voluntary registration threshold is SAR 187,500.
Can a business voluntarily register for VAT in Saudi Arabia?
Yes. Any company with a taxable turnover or expense of SAR 187,500 to SAR 375,000 is able to register voluntarily to get back Input VAT.
How do I register for VAT with ZATCA?
Log in to the ZATCA website, fill out the registration form, submit your CR and financial documents, and download your VAT certificate.
What is the difference between Input VAT and Output VAT?
Output VAT is the tax charged by the business on the sales of its products or services. Input VAT is the tax paid by the business to the suppliers. The net tax to be paid is the difference between output and input VAT.
Can businesses claim VAT refunds in Saudi Arabia?
Yes. If the Input VAT is greater than the Output VAT during any taxable period, businesses may apply for a VAT refund using the ZATCA portal.
How often do businesses file VAT returns in Saudi Arabia?
If the annual revenue is less than SAR 40 million, they will be filing the returns quarterly, while those above SAR 40 million annually will file returns annually.
What records must businesses maintain for VAT compliance?
The documents include invoices, books of accounts, customs papers, banking statements, and credit/debit notes for not less than 6 years.
What are zero-rated supplies in Saudi Arabia?
Zero-rated supplies (taxed at 0%) are exports of products/services outside the GCC, international transportation, qualified medicines, and healthcare and educational services. Input VAT is fully reclaimable.
What are exempt supplies in Saudi Arabia?
Examples of exempt supplies include certain financial services and residential rentals where no VAT applies but input VAT cannot be recovered by businesses.
How does VAT affect foreign investors in Saudi Arabia?
VAT impacts on foreign investors include ensuring that they have VAT of 15% included in local selling prices, early registration of their businesses under ZATCA, proper configuration of e-invoices software, and cross-border transaction regulations.
How does VAT affect GCC cross-border businesses?
The GCC’s cross-border supplies regulations adhere to the provisions of a unified framework, which includes contract structuring, the reverse charge mechanism, and verification of exports/imports.
What should businesses know about Saudi Arabia’s e-invoicing deadlines?
Phase 2 (Integration Phase) of E-Invoicing is being rolled out in batches. Businesses must integrate their billing/ERP system with ZATCA before the deadline set in their batch (Wave 25 deadline is 1 February 2027).
How does VAT affect digital platforms and GCC sellers?
Digital platforms have deemed supplier obligations, and hence are required to collect and remit VAT on behalf of non-resident and GCC suppliers.
Conclusion
Compliance with VAT involves constant operational efforts that influence pricing, financial flow, and legality in the country. To survive in Saudi Arabia, it is crucial to do more than file forms: companies need to make sure their company formation is in line with the ZATCA registration process, have proper tracking of input and output VAT, use the phase two e-invoices system, and keep up with the evolving GCC taxation regime. Managing these tax obligations early will help companies avoid problems and secure their success in KSA.
References
- Tax Authority: Zakat, Tax and Customs Authority (ZATCA)
- Saudi Official Portal: National Single Window for Government Services (GOV.SA)
- Regional Framework: GCC Unified VAT Agreement Guidelines
Top Saudi Arab Packages
Related Articles
Top Saudi Arab Packages
Get in Touch
