
Mauritius Offshore Corporate Banking Guide: Onboarding and Post-Opening Compliance
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: Mauritius has over $20 billion in foreign currency deposits. The FSC Authorised Bank Signatory Regime mandates that a bank signatory of GBC must be an officer of a licensed Management Company.
Table of contents
- Introduction
- Why Mauritius is a Preferred Banking Jurisdiction
- Why Businesses Consider Mauritius for Offshore Banking
- Key Features to Look for in Offshore Corporate Banking
- Top Banks in Mauritius for Offshore Companies
- How to Choose the Right Bank for Your Business
- Pre-Submission Readiness for Mauritius Bank Onboarding
- Key Challenges in Offshore Banking
- Mauritius GBC Bank Signatory Requirements: What Businesses Need to Prepare For
- Best Practices for Offshore Companies
- What Happens After the Bank Account Is Opened?
- How Arnifi Supports Offshore Banking Setup
- Frequently Asked Questions
- Conclusion
- References
Introduction
Mauritius is a leading international financial hub, offering access to African, Asian, and international markets for trade and investments. It provides an attractive platform for multinational companies, investment funds, and global trading entities through their corporate offshore bank accounts in multiple currencies. In addition to providing currency options, regulatory stability, and trade financing instruments, the onboarding process of opening an offshore bank account demands more attention.
Increased international regulations by FATF and OECD, among others, have led to strict anti-money laundering and know your customer policies in the Mauritian financial sector. This guide takes you beyond the bank list to the onboarding process, which will help you prepare for the process, understand the requirements like the FSC Authorised Bank Signatory Regime, and complete the process successfully.
Why Mauritius is a Preferred Banking Jurisdiction
Regulated Banking Ecosystem
The Mauritian banking system follows a dual regulation system. BoM, or the Bank of Mauritius, functions as the central bank that regulates commercial banking operations, monetary stability, and credit institutions in the country. At the same time, the Financial Services Commission (FSC) regulates non-banking financial services, Global Business License, and management companies.
Strict AML & International Compliance Standards
Mauritius follows international financial governance standards such as:
- FATF Standards: Complete compliance with the FATF 40 recommendations for money laundering and terrorist financing.
- CRS & FATCA: Automatic exchange of information about financial accounts through CRS and FATCA (U.S. Foreign Account Tax Compliance Act).
- OECD Inclusive Framework: Compliance with BEPS (Base Erosion and Profit Shifting) norms to prevent any kind of harmful tax practice.
Strategic Location & International Connections
Mauritius is located in the Indian Ocean, and it functions as the financial gateway for Asian capital markets and African growing sectors.
- Investment Treaties: A large number of DTAAs (Double Taxation Avoidance Agreements) and IPPAs (Investment Promotion and Protection Agreements).
- Institutional Connectivity: Direct financial connectivity through SWIFT and regional clearing houses.
Why Businesses Consider Mauritius for Offshore Banking
Companies choose Mauritius for offshore corporate banking due to the following three key operational drivers:
- International Business Operations: Allows making cross-border payments and settlements easily for holding companies, service providers, and international vendors across EMEA and APAC.
- Multi-Currency Requirements: Enables companies to keep cash balances in USD, EUR, GBP, and other currencies in order to protect from currency fluctuations and minimize conversion costs.
- Trade Finance & Financial Services: Direct access to trade financing products such as LCs, performance guarantees, and tailor-made treasury solutions.
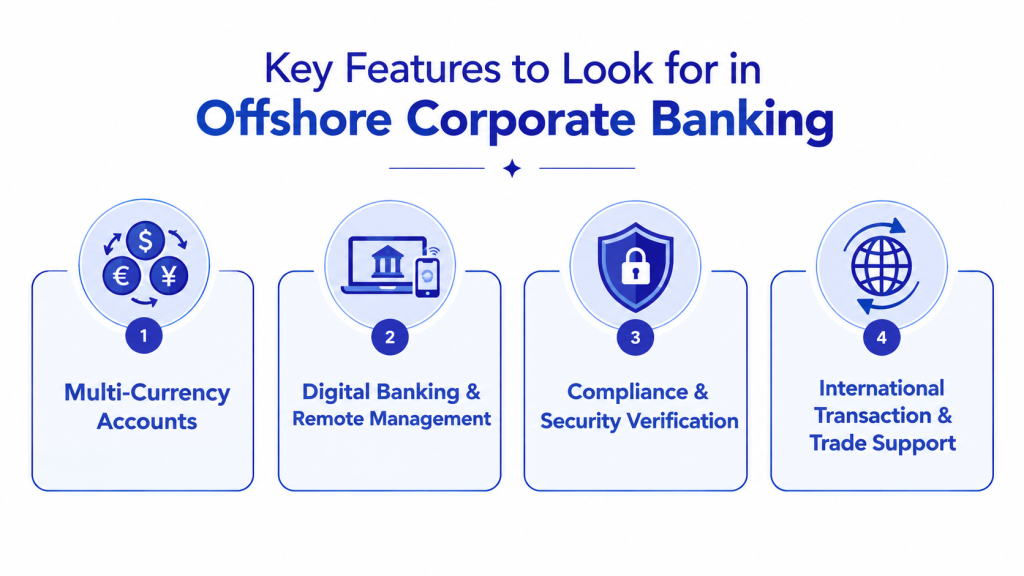
Key Features to Look for in Offshore Corporate Banking
1. Multi-Currency Accounts
Most offshore companies operate in many different jurisdictions and need multi-currency accounts in order to manage foreign exchange. Top offshore banks in Mauritius provide multi-currency accounts for USD, EUR, GBP, ZAR, AUD, CAD, SGD, and JPY within one banking account.
2. Digital Banking & Remote Management
Corporate clients working in various locations across the globe need to be able to manage their bank account remotely and securely 24/7. Such features as:
- Multi-factor Authentication (MFA) and hardware tokens;
- Custom Authorization Workflow (such as dual-signatory, limit controls);
- Real-Time Transaction Monitoring; API connectivity for corporate ERP systems.
3. Compliance & Security Verification
Banks evaluate account integrity using a four-tier compliance review process:
| Compliance Review Stage | Core Objective & Deliverables |
| 1. Customer Due Diligence (CDD) | Identify and verify legal entity status, incorporation records, and operating history. |
| 2. UBO Verification | Unravel ownership structures down to natural persons holding ≥20% equity or voting rights. |
| 3. Source of Funds & Wealth | Audit financial statements, client contracts, and capital injections to verify funding legitimacy. |
| 4. Automated Transaction Monitoring | Screen post-opening activity continuously against approved operational profiles. |
4. International Transaction & Trade Support
There are financial products other than wire transfers that international business organizations use:
- Letters of Credit (LCs): Import/Export transactions.
- Bank Guarantees & Standby LCs (SBLCs): Letters of Credits (SBLCs): Assurance of performance and security.
- Treasury & FX Hedging: Forward Contracts and Currency Swaps.
Top Banks in Mauritius for Offshore Companies
| Bank Name | Key Strengths & Focus Areas | Target Entity Profile | Digital & FX Capabilities |
| Mauritius Commercial Bank (MCB) | Largest bank in Mauritius; extensive correspondent network, advanced trade finance. | Multinationals, large GBCs, institutional funds. | Enterprise digital platform, multi-currency treasury. |
| State Bank of Mauritius (SBM) | Strong regional footprint across India and East Africa; structured corporate credit. | Cross-border trade firms, regional corporates. | Robust corporate online banking, FX services. |
| AfrAsia Bank | Wealth management, bespoke corporate banking, flexible international desks. | High-net-worth entity holdings, mid-market GBCs. | Personal relationship managers, multi-currency setup. |
| HSBC Mauritius | Global connectivity, standardized international cross-border compliance. | Global enterprises, subsidiaries of foreign MNCs. | HSBC Net integration, global trade solutions. |
| Absa Bank Mauritius | Sub-Saharan trade corridor focus, specialized corporate financing. | Regional trade hubs, African expansion ventures. | Digital corporate portal, structured trade finance. |
How to Choose the Right Bank for Your Business
Finding the right banking partner involves aligning your business operations with the preferences of institutions:
- Nature and Scale of Operations: The investment holding business type needs good custody capabilities, while international business vendors will need good transaction processing capabilities.
- Transaction Volume and Currency Profile: Consider the minimum account balances, incoming/outgoing transfer fees, and foreign exchange spread schedules for target currencies.
- Digital Banking Infrastructure: Consider bulk payment capabilities, SWIFT MT103 transaction confirmation tracking capability, and multi-user access privileges.
- Institutional Due Diligence Thresholds: Determine if your business is too complex for the institution (e.g., multi-trust ownership).
Pre-Submission Readiness for Mauritius Bank Onboarding
Document preparation failure is one of the most important causes of problems with account opening or rejection. Pre-submission checks will assist with the following three stages of onboarding:
- 1. AML and Sanctions Pre-Screening: Pass UBOs, directors, and trading counterparties through screening systems such as the Arni AML Checker based on global watchlists and PEP databases.
- 2. Organogram Preparation: Prepare an organogram indicating all holding levels, trusts, or companies up to the ultimate beneficial owners and clearly stating direct and indirect percentage ownership.
- 3. Dossier Compilation: Provide the dossier consisting of apostilled corporate incorporation documents, passports of directors/UBOs, source of funds information (bank statements, audited financials), and a 3-year business plan.
Practical Note: Banks run their own compliance checks. Early detection of potential document deficiencies will prevent further processing problems.
Key Challenges in Offshore Banking
- Rigorous Due Diligence: A thorough investigation into cash flow coming in and out, trading agreements and counterparties will be undertaken.
- Extended Account Opening Timelines: Complicated structures or insufficient dossier information could lead to delays of weeks, even months.
- Complex Ownership Verification: Multiple jurisdictional layers will need apostilled documents for all holding levels.
Mauritius GBC Bank Signatory Requirements: What Businesses Need to Prepare For
1. FSC Authorised Bank Signatory Mandate Overview: Regulatory mandate under the Financial Services Act.
In accordance with the new regulatory regimes set up by the Financial Services Commission (FSC), GBCs (Global Business Companies) in Mauritius have to ensure that their bank account controls comply with local management standards.
2. Approved Management Company Officer as Signatory: Governance requirement for GBC accounts.
A GBC’s bank accounts must have at least one approved officer of the GBC’s licensed Management Company (MC) as an authorised signatory on the bank mandate.
3. Structuring Bank Mandates from Day One: Operational coordination during account setup.
In order to avoid any operational problems, the founders of the corporation need to coordinate their work with their MC from the very start and to determine joint signatories’ mandates (for example, dual signatory requirement above certain transaction values).
Best Practices for Offshore Companies
- Prepare Documentation Ahead of Time: Make sure all foreign corporate documents have proper legal certification (Apostille/Consular legalization) before filing them.
- Maintain Operational Transparency: Give clear descriptions of your operational structure, trade operations, and key commercial contacts.
- Select a Banking Partner Based on Operational Needs: Choose your banking partner based on the type of transactions, FX needs, and trade activities.
- Work with Offshore Specialists: Collaborate with corporate service providers who will be able to introduce you to the banks, check the completeness of compliance, and communicate with the bank’s underwriters.
What Happens After the Bank Account Is Opened?
Approving accounts is an operational standard that is never-ending rather than a definitive process. Ensuring a fully functional corporate banking system entails going through these various stages in the account lifecycle:
- Phase 1: Initial Account Setup & Funding: The bank provides credentials and SWIFT details; the corporation makes the first minimum funding to enable services.
- Phase 2: Ongoing Substance Monitoring: The company makes sure to monitor its local operational expenses, board meetings, and management actions to comply with FSC requirements.
- Phase 3: Accounting & Record Management: Accounting software is used to capture invoice and balance information in real time to keep audit-ready.
- Phase 4: Annual Compliance Maintenance: Corporate managers update their annual KYC, file annual audited returns, and renew due diligence records at the bank.
- Phase 5: Uninterrupted Banking Operations: Proper record-keeping guarantees uninterrupted banking processes despite compliance and transactional holds.
How Arnifi Supports Offshore Banking Setup
Arnifi delivers full-cycle assistance during the offshore banking process:
- Bank Selection & Profiling: Matching your corporate profile with the right banks in Mauritius.
- Pre-Submission Readiness: Using Arni AML Checker for sanctions screening, organizing an organogram, and document validation.
- Bank Coordination: Assisting with communication with the bank’s compliance department for faster application assessment.
- Post-Opening Compliance: Comprehensive ongoing assistance through regulatory substance management.
Frequently Asked Questions
What is offshore banking in Mauritius?
Offshore banking in Mauritius is the provision of corporate banking services offered by licensed Mauritian banks to non-residents or to GBCs carrying on their businesses outside Mauritius.
Why do companies choose Mauritius for offshore banking?
Businesses opt for offshore banking in Mauritius due to sound financial regulations, multi-currency banking, the presence of tax treaties, political stability, and its role as an investment platform between Africa and Asia.
Which banks in Mauritius offer offshore corporate banking?
Some of the prominent offshore banks in Mauritius include Mauritius Commercial Bank (MCB), State Bank of Mauritius (SBM), AfrAsia Bank, HSBC Mauritius, and Absa Bank Mauritius.
Can an offshore company open a bank account in Mauritius?
Foreign businesses and Mauritius-incorporated GBCs/ACs may open accounts in the local banks, which are subject to the basic KYC requirements.
What documents are required to open an offshore bank account in Mauritius?
The key documents required for opening an offshore bank account in Mauritius include Certificate of Incorporation, Memorandum & Articles of Association, FSC Global Business Licence, business plan, UBO’s identity and address, and source of funds documentation.
How long does it take to open a corporate bank account in Mauritius?
The process of account setup usually takes anywhere between 2 and 6 weeks, based on the intricacies involved in the ownership, availability of documents, and compliance by the bank.
Is Mauritius offshore banking regulated?
Yes, commercial banking activities are regulated by the Bank of Mauritius (BoM), whereas financial services and global companies are regulated by the Financial Services Commission (FSC).
What is the role of the Bank of Mauritius in offshore banking?
Bank of Mauritius regulates the offshore banking industry of Mauritius by issuing banking licenses, regulating commercial banks, setting up capital adequacy requirements, and implementing AML/CFT regulations at the national level.
What is the FSC Authorised Bank Signatory Regime?
It is a regulation that mandates the inclusion of an authorised officer of the licensed management company of a GBC in bank signatory mandates when opening bank accounts in Mauritius.
Does a Mauritius GBC need an approved Management Company officer as a bank signatory?
Yes, according to the FSC regulatory requirements, a bank account for a GBC should have at least one approved officer from the Management Company as an authorized signatory.
Can offshore companies open multi-currency accounts in Mauritius?
Yes, Mauritian banks provide accounts for corporate clients in major foreign currencies like USD, EUR, GBP, ZAR and AUD.
What causes delays in Mauritius offshore bank account opening?
The reasons for delays may include non-disclosure of ownership structure, not verified source of funds, lack of Apostille certificates and delays in answering the bank’s questions.
How can I prepare for Mauritius bank due diligence?
To prepare for the process you may conduct pre-submission screening, draw up an ownership structure and prepare your documentation.
Does Arnifi help with offshore banking services in Mauritius?
Yes, Arnifi is able to provide end-to-end services that include the choice of banks, preliminary screening before submission, managing the process of the application itself and compliance post-account opening.
What happens after a Mauritius offshore bank account is opened?
A company will need to ensure continued compliance substance, update its accounting records, perform periodic KYC renewals and comply with activities consistent with approved profiles.
Conclusion
Mauritius represents a secure environment for the international corporate banking services thanks to the solid regulation from the side of Bank of Mauritius and FSC. The successful establishment of a bank account in Mauritius requires choosing the right partner, having the necessary documentation and knowing the rules such as FSC Authorised Bank Signatory Regime. By conducting pre-submission checks and maintaining clear accounting standards, businesses can streamline onboarding and ensure long-term operational success.
References
- Bank of Mauritius (BoM): Central bank regulatory framework, banking guidelines, and supervisory codes.
- Financial Services Commission (FSC) Mauritius: Global Business licensing regulations, FSA guidelines, and circulars.
- Mauritius Revenue Authority (MRA): Tax residence standards and treaty interpretation guidelines.
- Financial Action Task Force (FATF): Mutual evaluation standards and global AML/CFT compliance benchmarks.
Top UAE Packages

Related Articles
Top UAE Packages
Get in Touch