
The Ultimate Guide to Setting Up a Holding Company in Luxembourg in 2026
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: Luxembourg SOPARFIs control over €10 trillion worth of cross-border assets by virtue of 80+ double tax treaties, complete EU directive access, and 100% participation exemptions from taxes on eligible dividends and capital gains.
Table of contents
- Introduction
- Why Luxembourg Is a Strategic Hub for Holding Companies
- Choosing the Right Structure: SOPARFI vs. SPF
- Selecting the Right Legal Form for Your Luxembourg Holding Company
- Understanding Luxembourg’s Holding Company Tax Benefits
- Economic Substance and Anti-Avoidance Compliance Requirements
- Step-by-Step Process to Set Up a Holding Company in Luxembourg
- Ongoing Compliance and Company Maintenance
- Exit Strategies: Liquidation and Dissolution of a Luxembourg Holding Company
- How Arnifi Simplifies Luxembourg Holding Company Formation
- Conclusion
- Frequently Asked Questions (FAQs)
Introduction
Setting up a holding company in Luxembourg is considered to be the optimal solution for organizing and managing cross-border operations and assets. Being located in the very center of Europe, Luxembourg provides excellent predictability of the regulation, strong legislation, and well-developed networks of double-taxation treaties.
MNCs, private equity funds, family offices, and other institutional investors often establish their Luxembourg holding companies in the form of SOPARFIs to efficiently manage international subsidiaries. Nevertheless, setting up such companies includes careful consideration of various intricacies related to incorporation, participation exemptions, substance, and post-incorporation compliance.
Why Luxembourg Is a Strategic Hub for Holding Companies
Political Stability, EU Membership, and Global Reputation
The small European country of Luxembourg always receives AAA ratings because of political stability, sound public finance management, and a business-friendly legal system. Being one of the founding members of the European Union (EU), Luxembourg provides a Luxembourg holding company with easy access to the common market of Europe and a reliable corporate legal environment that is accepted by international banks.
Access to Double Taxation Treaties and EU Directives
One of the main reasons for the creation of a holding company in Luxembourg is the availability of more than 80 bilateral Double Taxation Treaties (DTTs) in the country. Besides, holding companies located in Luxembourg are entitled to EU Directives which include Parent-Subsidiary Directive and Interest and Royalties Directive.
Who Should Consider Setting Up a Holding Company in Luxembourg?
- Multinational Corporations: For management of international subsidiaries and other operational companies.
- Private Equity & Venture Capital Funds: For structuring regional investments portfolio and holding.
- Family Offices & High-Net-Worth Individuals (HNWIs): For management of multinational private assets, real estate, and stocks.
- Tech & IP Enterprises: For protection and monetization of intellectual property portfolio assets.
Choosing the Right Structure: SOPARFI vs. SPF
Luxembourg offers distinct legal structures depending on the intended commercial scope and ownership profile.
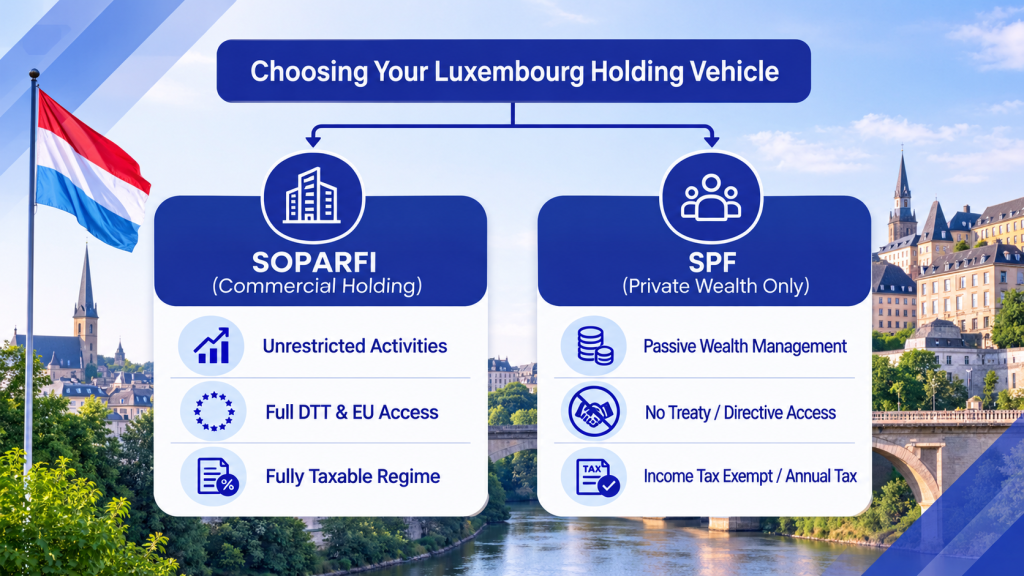
SOPARFI (Société de Participations Financières): Commercial Holding and Investment Activities
The SOPARFI is not a specific form of company but rather a standard commercial company that is subject to Luxembourg tax law on companies. The SOPARFI is used mainly for holding shares, providing finance, handling intellectual property rights, or conducting commercial activities. Being fully taxable means being able to benefit from double-taxation treaties and EU directives.
SPF (Société de Gestion de Patrimoine Familial): Private Wealth Management
The SPF is restricted solely for use by persons managing their personal family assets. The SPF cannot engage in commercial transactions, make loans that accrue interest, or manage actively. It is exempt from Luxembourg corporate income tax, municipality commercial tax, and net wealth tax; it however pays annual subscription tax of up to €125,000. It cannot access double taxation treaties.
SOPARFI vs. SPF: Taxation, Permitted Activities, and Treaty Access
| Feature | SOPARFI | SPF |
| Primary Purpose | Holding, financing, commercial activity | Private family wealth management |
| Eligible Investors | Corporations, funds, individuals | Individuals, family offices, trusts |
| Tax Regime | Fully taxable (subject to exemptions) | Exempt from CIT/MBT/NWT; Subscription tax applies |
| Treaty & EU Access | Yes (full treaty access) | No access to DTTs or EU Directives |
| Commercial Operations | Permitted | Strictly prohibited |
Selecting the Right Legal Form for Your Luxembourg Holding Company
When creating a SOPARFI holding company in Luxembourg, you must choose a legal entity form:
S.à r.l. (Société à responsabilité limitée): Requirements and Minimum Share Capital
- Minimum Share Capital: €12,000. (Recent Luxembourg corporate law updates allow founders to defer payment of the €12,000 capital for up to 12 months under specific incorporation terms).
- Shareholders: 1 to 100.
- Governance: Managed by one or more managers (managers do not need to be shareholders). Shares are subject to transfer restrictions.
- Suitability: Popular choice for small-to-medium holding structures and foreign parent entities due to flexibility.
S.A. (Société anonyme): Corporate Governance and Capital Requirements
- Minimum Share Capital: €30,000 (at least 25% paid up at incorporation).
- Shareholders: Minimum of 1 shareholder.
- Governance: Board of Directors or a two-tier Management Board/Supervisory Board model. Allows negotiable securities and public share issuances.
- Suitability: Favored by large corporations, joint ventures, and institutional investment structures requiring capital market readiness.
Alternative Structures: S.C.A. and SCSp for Investment and Family Office Arrangements
- S.C.A. (Société en commandite par actions): General partners have unlimited liability; limited partners have limited liability in an SCA structure. This form is highly recommended to retain management control.
- SCSp (Société en commandite spéciale): This partnership does not have legal personality and allows complete contractual freedom as well as full tax transparency.
Understanding Luxembourg’s Holding Company Tax Benefits
The SOPARFI holding company that is based in Luxembourg is considered a taxable corporate entity. Nevertheless, there are tax exemptions within the domestic taxation system of Luxembourg, which help in lowering taxes in relation to the activities of the holding.
Participation Exemption Regime: Tax Treatment of Dividends and Capital Gains
According to Article 166 of the LITL, dividends and capital gains on the sale of the stocks of the qualified subsidiaries are exempt from the CIT and MBT at 100%, if certain requirements are fulfilled:
- Eligible Entities: The parent must be a fully taxable Luxembourg entity, and the subsidiary must be a fully taxable resident entity, an EU entity under the Parent-Subsidiary Directive or non-resident entity taxed at a comparable rate (8% or higher).
- Minimum Ownership Threshold:
- For Dividends: Minimum 10% shareholding or an acquisition cost of at least €1.2 million.
- For Capital Gains: Minimum 10% shareholding or an acquisition cost of at least €6.0 million.
- Holding Period: The holding company must hold (or commit to hold) the qualifying stake for an uninterrupted period of at least 12 months.
Net Wealth Tax: Exemptions for Qualifying Participations
Luxembourg imposes an annual Net Wealth Tax (NWT) rate of 0.5% on net assets up to €500 million (0.05% on amounts above €500 million). Participations satisfying Participation Exemption requirements (10% stake or €1.2M cost of acquisition) do not pay any NWT. Minimum NWT rates are applied as per total balance sheet composition.
Withholding Tax on Dividends, Interest, Royalties, and Liquidation Proceeds
- Dividends: Dividend payments by a Luxembourg SOPARFI are subject to 15% domestic withholding tax. However, withholding tax is waived (i.e., withholding tax rate is reduced to 0%) when the tax payment is made to the EU/DTT parent company satisfying Participation Exemption requirements (10% stake or €1.2M investment held for 12 months).
- Interest & Royalties: There is no withholding tax imposed on arm’s-length interest and royalty payments.
- Liquidation Proceeds: Distributions in connection with the full liquidation of a SOPARFI are exempt from Luxembourg dividend withholding tax.
Luxembourg IP Box Regime: Tax Benefits for Qualifying Intellectual Property Income
According to article 50bis LITL, if qualifying IP is created by means of qualifying R&D, such IP can be exempted from 80% of the net IP income and net capital gains. This means that the corporate income tax rate will amount to 4.77% for the qualifying IP revenue.
Economic Substance and Anti-Avoidance Compliance Requirements
In order to avoid creating artificial structures, under the international tax standards (BEPS, ATAD I & II, and DAC6), all holding companies in Luxembourg must prove the existence of commercial purpose and substantive activity within Luxembourg.
Understanding ATAD, BEPS, and the Principal Purpose Test
The PPT concept according to ATAD and OECD BEPS project implies that transactions of such entity should be examined by the tax authorities. If the entity is considered a shell entity without sufficient economic substance, then the benefit of participation exemptions or tax treaties may be lost.
Local Directors, Physical Office, and Strategic Decision-Making
In order to prove economic substance in Luxembourg, the structure needs to:
- Board Composition: The majority of members on the board of managers/directors have to be Luxembourg tax residents with the necessary expertise.
- Management Control: Strategic decision-making and board meetings have to take place in Luxembourg.
- Registered Office: A local physical office in Luxembourg (not just a virtual office with an address in Luxembourg).
Maintaining Corporate Records, Banking, and Operational Substance
- Local Bank Accounts: Active operational bank accounts maintained within Luxembourg or the EU.
- Corporate Archives: Keeping share registers, board minutes, and accounting documents at the registered office.
- Operational Expense: Substantial operational expenses corresponding to the holding activity of the corporation.
Step-by-Step Process to Set Up a Holding Company in Luxembourg
Step 1: Assess Investment Objectives and Select the Legal Structure
Identify the business objective of the holding company (such as shareholding, financing, and intellectual property) and choose the type of entity, which may be an S.à r.l., S.A., or other type of company depending on capital needs and investment objectives.
Step 2: Reserve the Company Name and Prepare Incorporation Documents
File the request for name availability at the Luxembourg Trade and Companies Register (Registre de Commerce et des Sociétés – RCS) and prepare the Articles of Association, chart of entities, and documents for UBO declaration.
Step 3: Deposit Share Capital and Complete Notarial Incorporation
Open a special bank account for payment of share capital and deposit the minimum amount of capital as required for the entity chosen, which is €12,000 for S.à r.l. and €30,000 for S.A. Obtain capital blocking certificate from the bank. Then have notarized incorporation of the company.
Step 4: Register with the Luxembourg Trade and Companies Register (RCS)
In a matter of days after formation, submit the deed of incorporation to the RCS. Get a unique corporate identification number (R-number), and register the beneficial owners in the Luxembourg Register of Beneficial Owners (RBO).
Step 5: Complete Tax, VAT, Accounting, and Post-Incorporation Formalities
Submit the company to the Luxembourg Direct Tax Administration (Administration des Contributions Directes) for corporate income tax number. In case your activities involve commercial or financing operations that necessitate VAT, submit the company to the Registration Duties, Estates and VAT Authority (Administration de l’Enregistrement, des Domaines et de la TVA).
Ongoing Compliance and Company Maintenance
Annual Accounting, Financial Statements, and Audit Requirements
- Financial Statements: The Luxembourg-based holding company should draw up its annual accounting records (balance sheet, P&L account, and appendices) according to either Luxembourg GAAP or IFRS. They should be adopted by the shareholders within 6 months from the financial year-end and filed at the RCS within 7 months.
- Statutory Audit: Small SOPARFIs can opt out of independent audit (réviseur d’entreprises agréé) requirements, provided that they do not exceed any two out of the three following criteria during two consecutive fiscal years:
- Balance sheet total: €4.4 million
- Net turnover: €8.8 million
- Average headcount: 50 employees
Corporate Tax Filings, Regulatory Updates, and Governance Records
It is required to electronically file annual corporate income tax returns, municipal business tax returns, and net wealth tax returns. Also, you should update your corporate registers to stay compliant with current regulations.
Maintaining Compliance Across Cross-Border Investment Structures
Make sure that the distribution of dividends, financing, and intercompany transactions are in line with the transfer pricing policy (based on benchmarking studies), and DAC6, CbCR, and Pillar Two requirements are followed.
Exit Strategies: Liquidation and Dissolution of a Luxembourg Holding Company
When a holding company in Luxembourg reaches the end of its purpose, Luxembourg corporate law provides clear exit mechanisms.
Standard Voluntary Liquidation: Key Stages and Formalities
- Dissolution & Liquidator Appointment: Shareholders decide to wind up the company through a notary who also nominates the liquidator.
- Realization of Assets & Liabilities: Liquidator proceeds to realize the company’s assets, settle third party liabilities, prepare liquidation accounts that are independently audited by a commissaire à la liquidation.
- Closing Meeting: Final meeting held by shareholders approving the liquidator’s report, discharging him/her, distribution of leftover assets and finally the deregistration from the RCS.
Simplified Single-Shareholder Dissolution: Eligibility and Process
Article 1865-bis of the Luxembourg Civil Code allows a company having only one shareholder to opt for a dissolution simplifiée in a single notarial deed without undergoing any liquidation.
- Eligibility: Only companies having a single shareholder and all third-party debts cleared/settled (third-party clearances such as those on tax, VAT and social security must be done before execution).
- Effect: All the company assets and liabilities will directly transfer to the single shareholder after signing the deed.
Final Tax Filings, Asset Distribution, and Company Closure
Submission of final tax declarations up to the date of dissolution. Distributions to non-resident shareholders are 100% exempt from Luxembourg dividend withholding tax.
How Arnifi Simplifies Luxembourg Holding Company Formation
The process of establishing a holding company in Luxembourg has various international laws, taxes, and regulations associated with it. Arnifi offers a technology-based platform which is specially designed for multinational companies, funds, and family offices.
End-to-End Incorporation Support with Transparent Pricing (USD 17,760)
Arnifi manages the entire process of setting up your Luxembourg holding company at an all-inclusive fixed package cost of USD 17,760.
Legal Documentation, Notary Coordination, and RCS Registration
Arnifi prepares customized articles of association, coordinates capital account setup in banks, manages Luxembourg notary coordination, and registers at RCS and RBO.
Arni Organogram, AML Screening, Cost Calculator, and Compliance Dashboard
- Arni Organogram: Visualize complex multi-jurisdictional holding structures instantly.
- Automated AML/KYC Screening: Fast-track compliance checks for directors and ultimate beneficial owners.
- Digital Compliance Dashboard: Track filing deadlines, corporate records, and statutory obligations in real time.
Ongoing Support for Corporate Governance, Bookkeeping, Banking, and Visa Assistance
Arnifi offers comprehensive maintenance after incorporation, with local directorship contacts, registered address service, local bookkeeping, local tax compliance, bank accounts, and residency services for executives.
Access to Other Luxembourg Structures: SCSp, RAIF, and SPF
Move beyond SOPARFI entities by executing other investment structures using Arnifi’s services, such as Special Limited Partnerships (SCSp), Reserved Alternative Investment Funds (RAIF), and Private Wealth Vehicles (SPF).
Conclusion
By incorporating a holding company in Luxembourg, international investors get an environment that is safe and well-structured for managing assets and international expansion. This can be achieved through incorporation of the right type of business (S. à r.l. vs. S.A.), using participation exemptions, and ensuring local economic substance.
Would you like to create your holding company structure in Luxembourg? Reach out to Arnifi today for consultations from experienced cross-border business structuring experts and easy entity creation.
Frequently Asked Questions (FAQs)
What is a SOPARFI in Luxembourg?
SOPARFI is a taxable company incorporated in Luxembourg used as a vehicle for investment holding, group financing, and commercial operations.
What are the main benefits of setting up a holding company in Luxembourg?
It enjoys full participation exemptions, EU directives, double taxation agreements, political stability, and corporate flexibility.
What is the difference between a SOPARFI and an SPF?
SOPARFI is a taxable entity for commercial and holding activities, while SPF is an exempt private family wealth holding company.
What is the minimum share capital required to establish a Luxembourg holding company?
An S.à r.l. requires a minimum capital of €12,000, while an S.A. requires €30,000 (€7,500 paid up).
How does the Luxembourg participation exemption regime work?
This system offers 100% tax exemption on dividends and capital gains after one year if certain thresholds are met.
Does a Luxembourg holding company need local directors and office space?
Yes, local directors and office are needed in order to demonstrate the economic substance under international tax laws.
How long does it take to set up a holding company in Luxembourg?
Generally, the time to incorporate the company after the completion of KYC and payment of minimum share capital is around 1-2 weeks.
Can a Luxembourg holding company own foreign subsidiaries and intellectual property?
Yes, a SOPARFI can hold foreign subsidiaries, intellectual property and provide group financing in various jurisdictions.
What are the annual compliance requirements for a Luxembourg holding company?
It must maintain financial records, file annual accounts within 7 months, hold annual meetings, and submit tax returns
Credible Resources & References
- Guichet.lu (Luxembourg Public Administrative Portal): Setting up a company in Luxembourg
- Luxembourg Trade and Companies Register (RCS): Official Corporate Registry
- Administration des Contributions Directes (ACD): Luxembourg Direct Tax Authorities
- Legilux: Official Journal / Luxembourg Corporate Legislation
Top UAE Packages
Related Articles
Top UAE Packages
Get in Touch
