
HKFRS for Private Entities 2027 | Transition Guide for Hong Kong Companies
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: The revised HKFRS for Private Entities Accounting Standard applies to annual periods beginning on or after 1 January 2027, with early application permitted. Companies should use 2026 to assess accounting changes, contracts, data, systems, disclosures and transition requirements.
Table of contents
- What is the revised HKFRS for Private Entities?
- Who needs to prepare for the 2027 HKFRS for PE changes?
- When does the revised HKFRS for Private Entities take effect?
- What are the major changes under the revised HKFRS for PE?
- How will revenue recognition change under revised HKFRS for PE?
- What changes affect financial instruments?
- What should companies review about lease accounting?
- How will disclosures change?
- How does the 2027 transition work?
- What should companies do during 2026 to prepare?
- What systems and data should be reviewed?
- What are the common HKFRS for PE transition challenges?
- What is the difference between revised HKFRS for PE and full HKFRS?
- How can Arnifi help with HKFRS for PE transition?
- FAQs
- Conclusion
What is the revised HKFRS for Private Entities?
HKFRS for Private Entities (HKFRS for PE) is a financial reporting option for eligible private entities that do not have public accountability. It is designed to reduce the reporting burden compared with full HKFRS Accounting Standards while providing a suitable framework for general-purpose financial statements.
HKICPA issued the revised HKFRS for PE in April 2025 following the publication of the third edition of the IFRS for SMEs Accounting Standard by the IASB in February 2025. The revised Hong Kong standard is equivalent to the third edition of the IFRS for SMEs Accounting Standard.
The revisions are extensive and cover nearly all sections of the standard. They can affect accounting policies, accounting treatments, disclosures and the information companies need to collect.
The revised HKFRS for Private Entities Accounting Standard takes effect for annual periods beginning on or after 1 January 2027, with early application permitted.
Who needs to prepare for the 2027 HKFRS for PE changes?
The transition is particularly relevant to entities currently applying HKFRS for PE and those considering early application of the revised standard.
Companies should first confirm that they remain eligible to use HKFRS for PE. Eligibility is separate from the transition exercise and depends on the entity’s circumstances, including whether it has public accountability.
HKFRS for PE should also be distinguished from the SME-FRF and SME-FRS. Hong Kong has separate financial reporting frameworks, and eligibility for each is determined independently.
For example, publicly traded entities cannot use HKFRS for PE simply because they are small. Entities that hold resources in a fiduciary capacity as one of their primary business activities may also have public-accountability considerations.
When does the revised HKFRS for Private Entities take effect?
The revised standard applies to annual periods beginning on or after 1 January 2027, and early application is permitted.
For a company with a calendar financial year, the revised requirements will generally apply to its annual financial statements for the year beginning 1 January 2027.
Companies with different financial year-ends should identify their own first applicable reporting period rather than assuming that the transition date will be the same as that of a calendar-year entity.
Establishing the transition date during 2026 gives management time to identify accounting changes, collect additional information and coordinate with auditors.
What are the major changes under the revised HKFRS for PE?
The amendments are broad and can affect several areas of financial reporting. Some of the major areas to review include:
| Area | What to review | Potential impact |
| Revenue | Customer contracts and performance obligations | Timing and measurement of revenue |
| Financial instruments | Classification, measurement and disclosures | Accounting policies and additional data |
| Disclosures | New or revised information requirements | Financial statement preparation |
| Accounting policies | Revised recognition and measurement requirements | Policy updates and transition adjustments |
| Transition | Retrospective application and available reliefs | Comparatives and opening balances |
One important clarification is that Section 20, Leases, was not amended in this revision to align with HKFRS 16. Companies should therefore avoid assuming that the 2027 revision introduces an HKFRS 16-style lease model.
The actual impact will depend on the company’s transactions and existing accounting policies.
How will revenue recognition change under revised HKFRS for PE?
Revised Section 23, Revenue from Contracts with Customers, introduces a five-step revenue-recognition model.
Companies should assess:
- Whether a contract with a customer exists
- The performance obligations in the contract
- The transaction price
- How the transaction price is allocated to performance obligations
- When or as each performance obligation is satisfied
This can require a detailed review of customer contracts, particularly where arrangements contain multiple deliverables, variable consideration or longer-term obligations.
Companies should therefore avoid simply carrying forward their existing revenue-recognition approach without assessing whether the revised Section 23 changes the accounting outcome.
What changes affect financial instruments?
Companies should review their financial assets and financial liabilities against the revised financial-instrument requirements.
One important change concerns disclosures. The revised Section 11 introduces additional information requirements, including ageing analysis for financial assets and maturity analysis for financial liabilities.
This means companies may need to capture information that their existing accounting systems do not currently produce in the required format.
The review should therefore cover:
- Classification and measurement
- Existing accounting policies
- Financial-asset information
- Ageing information
- Financial-liability maturity information
- Supporting documentation
- Financial statement disclosures
The revised standard retains the incurred-loss model for impairment of financial assets measured at amortised cost, so companies should not assume that every financial-instrument requirement has been replaced by a new impairment model.
What should companies review about lease accounting?
Lease arrangements should still be included in the broader transition assessment, particularly where they affect financial statements, disclosures or existing accounting policies.
However, the 2025 revision did not amend Section 20 to align it with HKFRS 16. HKICPA has indicated that any future alignment will depend on further experience with HKFRS 16.
Companies should therefore review their lease arrangements and current Section 20 accounting without assuming that the revised HKFRS for PE introduces a new HKFRS 16-based lessee model.
How will disclosures change?
The revised standard introduces additional and amended disclosure requirements. These can require information that is not currently collected as part of routine financial reporting.
Financial instruments are one example, with additional ageing and maturity information potentially required. Revenue is another area where companies may need to assess whether existing records contain sufficient information to support the revised disclosures.
Disclosure preparation should therefore begin alongside the accounting-policy review rather than at the end of the reporting process.
How does the 2027 transition work?
A practical transition process can include:
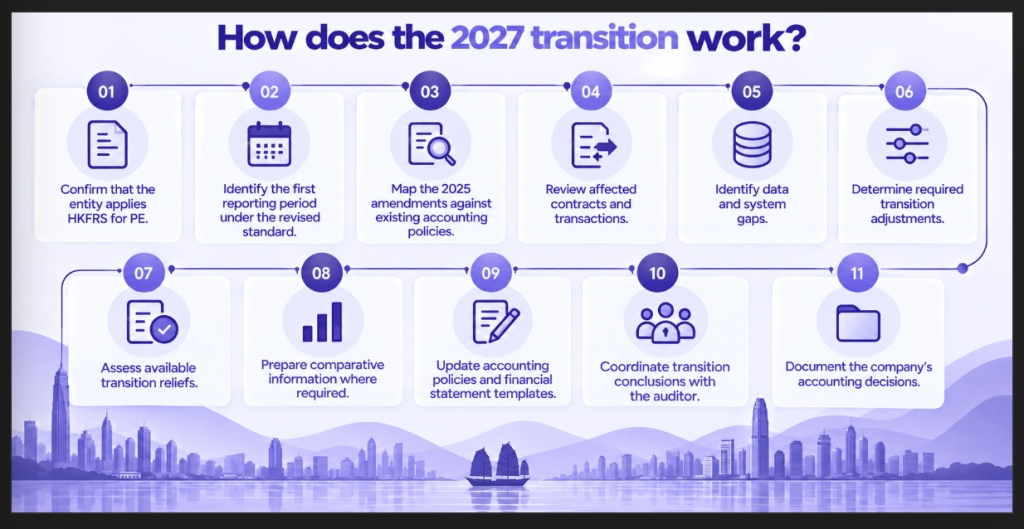
The revised standard requires retrospective application of the new and amended requirements, although specific reliefs are available for certain amendments.
What should companies do during 2026 to prepare?
Companies should treat 2026 as the preparation period rather than waiting until the first 2027 year-end.
The transition programme should include:
- An initial impact assessment
- Review of affected accounting areas
- Revenue-contract assessment
- Financial-instrument review
- Lease review
- Disclosure-gap analysis
- Accounting-system assessment
- Accounting-policy updates
- Finance-team training
- Auditor discussions
- A documented implementation timetable
HKICPA specifically recommends assessing how the amendments affect financial reporting based on each entity’s facts and circumstances.
What should the transition flow look like?
Assess
↓
Identify accounting changes
↓
Review contracts and data
↓
Update systems and policies
↓
Test transition adjustments
↓
Coordinate with auditor
↓
Apply revised HKFRS for PE
What systems and data should be reviewed?
The transition is not only an accounting-policy exercise. Companies should determine whether their existing systems can produce the information required under the revised standard.
Areas to review include:
- Accounting software and ERP capabilities
- Revenue-contract data
- Customer and transaction information
- Financial-asset ageing information
- Financial-liability maturity information
- Lease data
- Supporting documentation
- Financial-statement preparation processes
- Disclosure-generation processes
Where new information is required, companies may need additional data fields, reports, system configurations or internal controls.
Starting this review before 2027 can reduce the risk of discovering data gaps during financial-statement preparation.
What are the common HKFRS for PE transition challenges?
Common challenges include:
- Starting the assessment too late
- Treating the revision primarily as a disclosure exercise
- Failing to review customer contracts
- Not identifying affected financial instruments
- Missing data needed for new disclosures
- Leaving auditor discussions until year-end
- Failing to document accounting-policy decisions
- Assuming existing accounting software automatically captures all required information
- Not assessing available transition reliefs
The breadth of the amendments means the impact can vary significantly between companies. A business with relatively simple transactions may have limited changes, while companies with complex revenue arrangements or significant financial instruments may need more extensive preparation.
What is the difference between revised HKFRS for PE and full HKFRS?
HKFRS for PE remains a separate, simplified reporting framework for eligible private entities. It is not the same as adopting full HKFRS Accounting Standards.
The framework is based on the broader principles of financial reporting standards but incorporates simplifications designed around the needs and resources of eligible private entities.
Therefore, adopting the revised HKFRS for PE does not mean that a company is automatically moving to full HKFRS.
Companies should first confirm which financial reporting framework applies to them and then assess the specific transition requirements under that framework.
How can Arnifi help with HKFRS for PE transition?
Arnifi can support Hong Kong businesses with the transition to the revised HKFRS for Private Entities Accounting Standard.
Support can include reviewing the existing reporting framework, identifying affected accounting areas, assisting with accounting-policy updates and reviewing financial data and system requirements.
Arnifi can also assist with bookkeeping and financial reporting processes, audit-preparation coordination and ongoing accounting requirements, helping businesses prepare for the 2027 reporting cycle.
FAQs
What is the revised HKFRS for Private Entities Accounting Standard?
It is the 2025 revised Hong Kong financial reporting standard for eligible private entities without public accountability.
When does the revised HKFRS for Private Entities take effect?
It applies to annual periods beginning on or after 1 January 2027, with early application permitted.
Can companies apply the revised HKFRS for PE early?
Yes. Early application of the revised standard is permitted.
Who needs to transition to the revised HKFRS for PE?
Entities currently applying HKFRS for PE should assess the revised requirements and their transition obligations.
What are the major changes under the 2025 revised HKFRS for PE?
Major changes cover areas including revenue, financial instruments, accounting policies and disclosures.
How does the revised standard change revenue recognition?
Revised Section 23 introduces a five-step revenue-recognition model for customer contracts.
What financial instrument disclosures are changing?
Additional requirements include ageing analysis for financial assets and maturity analysis for financial liabilities.
Does the revised HKFRS for PE require retrospective application?
Yes. The revised requirements are generally applied retrospectively, subject to specific transition reliefs.
How should companies prepare for HKFRS for PE 2027?
Companies should assess affected transactions, update policies, review systems and data, test adjustments and coordinate with auditors.
Is HKFRS for PE the same as SME-FRS?
No. HKFRS for PE and SME-FRF/SME-FRS are separate financial reporting frameworks with different eligibility requirements.
Conclusion
The revised HKFRS for Private Entities Accounting Standard becomes effective for annual periods beginning on or after 1 January 2027, with early application permitted. The changes extend beyond disclosures, affecting areas such as revenue, financial instruments, accounting policies and transition procedures. Companies should use 2026 to review contracts, systems, data and accounting treatments, assess available transition reliefs and coordinate with auditors before the first reporting period under the revised requirements.
Official references
Top UAE Packages


Related Articles
Top UAE Packages
Get in Touch