
Form 5472 Filing Deadline | What Foreign-Owned US Businesses Need to Know
Nishant
Content Writer
Nishant Kumar is a technical content writer, he shares global business insights and bridges the gap between complex regulatory frameworks and actionable growth strategies.… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Facts: The filing requirement will apply to those 25% foreign-owned US corporations and foreign-owned disregarded entities. For non-disregarded entities, the filing requirement is usually activated by a reportable transaction that involves related parties. For calendar-year filers, the standard Form 5472 deadline is April 15. Fiscal-year entities follow the 15th day of the fourth month after their tax year-end, so April 15 is not universal. A late or incorrect filing can incur a statutory penalty of $25,000 under the IRS. If a filing deadline falls on a weekend or public holiday, then the deadline is the next working day.
Table of contents
Introduction
Running a foreign-owned corporate entity within the US demands that federal tax reporting procedures are adhered to. The IRS uses Section 6038A of the tax code to keep track of cross-border money movements and transactions.
Failure to submit the required forms before the statutory deadline results in financial penalties that deplete the cash flow of the firm. Corporate executives should ensure that strict accounting deadlines are met internally to reduce compliance risk.
What is Form 5472?
Form 5472 is an information document required by the IRS. The purpose of the document is to report any reportable transactions that occurred between the US reporting corporation and its domestic or foreign related parties. Contrary to the computation of the income tax liability, the information document plays only a regulatory role.
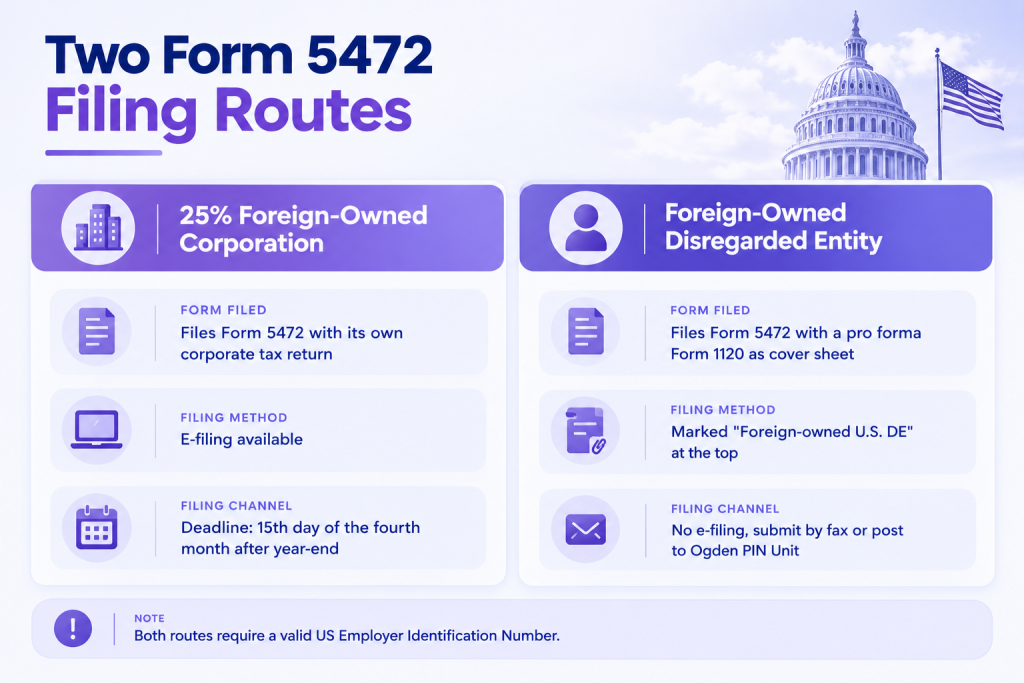
The regulation covers US corporations in which foreign stockholders own 25% or more of the stock by vote or value. Moreover, it includes foreign corporations having a business or trade in the US. What is interesting, founders of a single-member LLC, disregarded for tax purposes, should report too.
Annual filing is required regardless of whether the company made any profit during a year or was inactive. All the details are provided on the official IRS Form 5472 page.
When Is the Form 5472 Filing Deadline?
The normal deadline for the Form 5472 filings is exactly the same deadline as the one that applies when the taxpayer files their corporation tax return. In normal calendar years, the statutory deadline is the 15th day of the fourth month after the end of the taxable year, and that would be April 15. If April 15 falls on a weekend or legal holiday, then it would be postponed by the federal statutes to the next working day.
If entities need more time to complete their accounting, then they can get an automatic six-month extension if a filer successfully files Form 7004 before the deadline of April 15, then they will have extended their deadline to October 15.
How Do Disregarded Entities Submit the Form?
Single-member LLCs owned by foreign individuals cannot file Form 5472 independently. Federal tax rules mandate that the entity submit a pro forma Form 1120 solely for the purpose of using it as a cover sheet. The caption “Foreign-owned U.S. DE” should be written legibly at the top of this corporation’s income tax return.
A pro forma income tax return needs only minimal identification data like the name of the corporation, address, and Employer Identification Number. Disregarded entities have specific requirements for filing and are not allowed to e-file these forms. As per IRS guidelines, these forms should be faxed to the IRS dedicated fax number or mailed to the Ogden PIN Unit in Utah.
What Are the Penalties for Missing the Form 5472 Deadline?
Missing the Form 5472 filing deadline on time involves the most stringent administrative penalties found in the US Tax Code. The federal government imposes a base statutory penalty of $25,000 per instance of failure to report.
| Compliance Violation | Statutory Base Penalty (USD) | Continuation Penalty (USD) |
| Failure to file by deadline | 25,000 (Fixed base penalty) | 25,000 per 30-day period |
| Filing an incomplete form | 25,000 (Fixed base penalty) | 25,000 per 30-day period |
| Filing an inaccurate form | 25,000 (Fixed base penalty) | 25,000 per 30-day period |
| Failure to maintain records | 25,000 (Fixed base penalty) | 25,000 per 30-day period |
However, if the business does not rectify the problem regarding the compliance violation within 90 days from the issuance of the notification by the IRS, further penalties will be assessed automatically. The penalty imposed in this case will be $25,000 for each 30-day period thereafter.
How We at Arnifi Support US Corporate Compliance
At Arnifi, we function as a modern digital corporate service provider that aims to streamline the process of global business setup and ensure compliance. Foreign individuals who use a corporate structure in the US depend on our central digital platform for the removal of paperwork and to maintain pristine legal standing.
It requires great accuracy in managing related-party transactions, an area where our accounting and bookkeeping services help out to ensure proper tax preparation.
Apart from tax preparation, our team ensures that post-setup compliance takes place in its entirety after the establishment of the business so that all the required reports can be prepared. Our team ensures that corporate management goes through the entire process of money laundering prevention to get credible banking services across important financial markets.
Conclusion
The maintenance of the foreign business in the US needs constant monitoring of federal requirements with regard to information reporting. Given the heavy penalties for non-compliance with Form 5472, the management of the business calendar and transactions is extremely important for a company’s operations.
Having compliant accounting practices from the very beginning will ensure that all of your related parties will be reported on time.
Contact Arnifi today for personalized assistance and compliance.
FAQs
What is the standard Form 5472 filing deadline?
For calendar-year entities, the deadline is April 15. For fiscal-year filers, it is the 15th day of the fourth month after the fiscal year-end, and the extended date is six months after that original due date.
What if the deadline falls on a weekend?
In case of a weekend or holiday falling on April 15, the Internal Revenue Service moves the deadline to the next day.
Is there an option to get the filing deadline extended for Form 5472?
Yes. It can be done by filing Form 7004 prior to April 15, automatically extending the filing deadline by six months until October 15.
How much of a penalty is charged for the Form 5472 filing deadline being missed?
Internal Revenue Service may impose a penalty of $25,000 on each untimely, incomplete or missing form.
Does a dormant foreign-owned LLC need to file Form 5472?
Yes. Single-member LLCs that are foreign-owned have to file the form every year, whether or not they did any business activity or earned any revenue.
Which entities are considered 25 percent foreign-owned?
The corporation will qualify if one or more foreign person(s) own a minimum of 25% of the combined total voting power or the total value of all stock.
Can foreign-owned disregarded entities file Form 5472 online?
No. Foreign-owned disregarded entities cannot use electronic filing and should send their Form 1120 and 5472 pro forma through fax or postal mailing.
What will happen if you ignore a penalty notice from the IRS?
The IRS will impose a further penalty of $25,000 for every 30-day period after the initial 90-day period.
What is a Pro Forma Form 1120?
It is a business income tax return that is used only as a transmittal cover sheet by a disregarded entity that is owned by a foreign person to accompany the filing of Form 5472.
Do You Need An Employer Identification Number for Form 5472?
Yes. The entity filing this form should first acquire a valid US Employer Identification Number.
References
Internal Revenue Service: About Form 5472
Internal Revenue Service: About Form 1120
Top UAE Packages
Related Articles
Top UAE Packages
Get in Touch
