
Singapore Fund Audit and Reporting Requirements
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: Singapore fund audit requirements vary by legal structure, with Variable Capital Companies (VCCs) required to undergo an annual audit and appoint an auditor within three months of incorporation.
Table of contents
- Introduction
- Why are fund audits important in Singapore?
- What are the Singapore fund audit requirements for a VCC?
- What financial statements must a Singapore fund prepare?
- How do the audit requirements differ for standalone and umbrella VCCs?
- What are the annual audit and reporting deadlines for a Singapore VCC?
- What are the MAS reporting requirements for Singapore funds?
- What information should Singapore funds disclose to investors?
- What happens if a Singapore fund misses its audit or filing obligations?
- How can Arnifi help with Singapore fund compliance?
- FAQs
- Conclusion
- References
Introduction
Setting up an investment fund in Singapore is just the first step. The fund manager will also be required to keep proper financial records, arrange for independent audits, produce investor reports and meet all the ongoing regulatory deadlines.
The precise Singapore fund audit requirements will vary depending on the fund’s structure and classification. VCCs have specific statutory requirements, as do authorised and restricted schemes.
Why are fund audits important in Singapore?
An independent audit enables investors and fund managers to get a clear picture of whether the financial statements actually do reflect the fund’s financial position.
It supports:
- Verification of the financial statements and the accounting records
- Review of investment valuations and financial disclosures
- Greater transparency for investors
- Identification of accounting and internal control weaknesses
- Stronger financial governance and accountability
An audit doesn’t guarantee investment performance or eliminate investment risk. Its purpose is to provide an independent assessment of the financial reporting.
What are the Singapore fund audit requirements for a VCC?
Under the Variable Capital Companies Act 2018, every VCC must have at least one auditor appointed within three months of incorporation.
Key VCC audit requirements include:
- The auditor must comply with the relevant Singapore registration requirements
- The VCC must produce their financial statements for each financial year
- Its financial statements will of course be subject to an annual independent audit
- The normal small company audit exemptions under s205 B and s205C of the Companies Act don’t apply to VCCs
These obligations are irrespective of the size of the VCC. A smaller VCC cannot simply escape the requirement for an annual audit on the grounds that it is a small fund.
What financial statements must a Singapore fund prepare?
Fund financial statements in Singapore give a clear picture of the fund’s financial position, performance and activities.
Depending on the fund structure and applicable accounting framework, they may include:
- Statement of financial position
- Statement of comprehensive income
- Statement of changes in equity (or net assets) where applicable
- Cash flow statement
- Notes on accounting policies and financial disclosures
- Investment valuations and related party transactions
- Directors’ statement and independent auditor’s report
VCCs must prepare their financial statements in accordance with the relevant accounting requirements. The appropriate reporting framework will be determined by the entity and its circumstances.
How do the audit requirements differ for standalone and umbrella VCCs?
A standalone VCC operates as a single fund. An umbrella VCC can contain multiple sub-funds all under one legal entity.
| Area | Standalone VCC | Umbrella VCC |
| Structure | One fund | Multiple sub-funds |
| Accounting records | Records for the VCC | Separate records for each sub-fund |
| Financial reporting | VCC financial statements | Separate sub-fund financial statements alongside VCC-level reporting |
| Asset segregation | Single fund structure | Assets and liabilities segregated between sub-funds |
| Annual returns | VCC annual return | Separate annual returns for each sub-fund |
For umbrella structures, the key thing is that assets, liabilities, income and expenses are properly allocated. Each sub-fund must have its own set of financials, and you must not mix the assets and liabilities of one sub-fund with those of another.
What are the annual audit and reporting deadlines for a Singapore VCC?
The year-end determines the VCC’s annual compliance calendar.
| Requirement | Deadline |
| Appoint an auditor | Within three months of incorporation |
| Appoint a company secretary | Within six months of incorporation |
| Hold an AGM | Within six months of financial year-end, unless exempted or dispensed with |
| File annual return | Within seven months of financial year-end |
| Report relevant changes to VCC information and officers | Generally within 14 days |
The annual return must be filed post AGM. The VCCs will need to be well in advance of the deadlines to be in a position to co-ordinate with their auditors, administrators, directors and company secretary.
What are the MAS reporting requirements for Singapore funds?
ACRA filings and MAS regulatory reporting are for different purposes. ACRA is responsible for corporate registration and statutory filings. The reporting obligations to MAS are going to be very much dependent on the fund’s regulatory classification and the activities it’s engaged in.
Relevant requirements may include:
- Reporting obligations under the Securities and Futures Act
- Notifications and annual declarations for restricted schemes via MAS CISNet
- Periodic and annual reports for authorised collective investment schemes
- Compliance with the relevant provisions of the MAS Code on Collective Investment Schemes
- Relevant AML/CFT records and regulatory notifications
Not all private funds or hedge funds operate on the same reporting cycle. Fund managers should work out what the requirements are for their particular scheme rather than assume that one reporting regime will apply to all.
What information should Singapore funds disclose to investors?
Investor reporting enables participants to see how the fund is performing and how the assets are being managed.
Depending on the fund documents and applicable requirements, disclosures may cover:
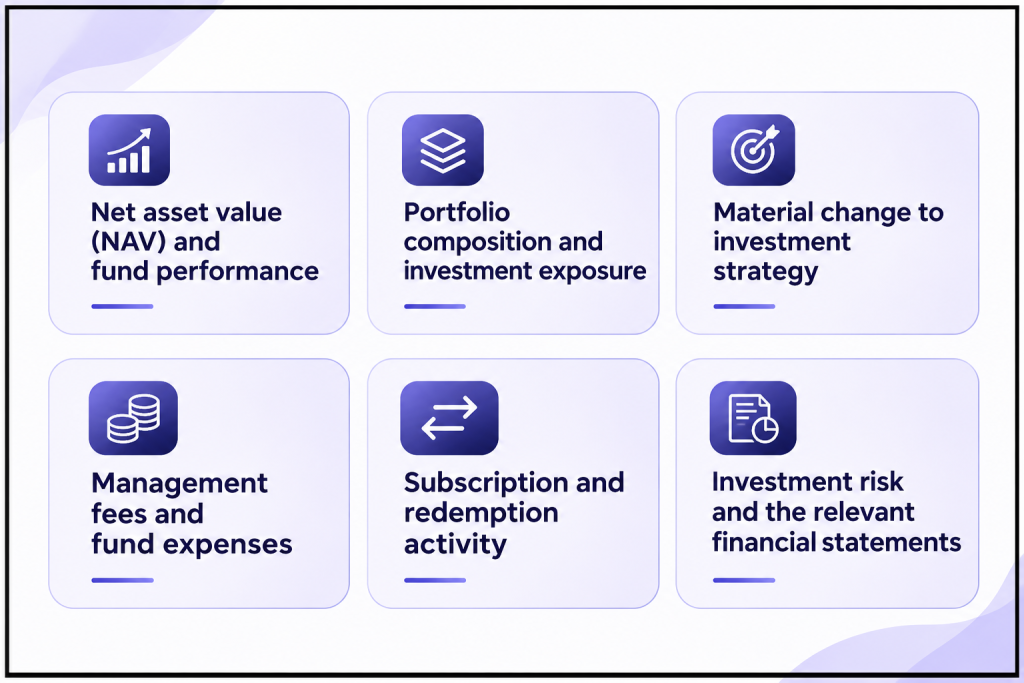
Reporting frequency and level of detail will vary according to the fund’s offering documents, the investor arrangements and regulatory requirements.
What happens if a Singapore fund misses its audit or filing obligations?
Missed deadlines can give rise to financial, regulatory and operational problems.
Potential consequences include:
- Late annual return filing penalties
- Regulatory enforcement or some other form of statutory action
- Delays in investor reporting
- Governance and record-keeping concerns
- Reputational damage
- Difficulties in demonstrating compliance with the applicable tax incentive conditions
Keep a compliance calendar and contact the appropriate service providers to ensure you don’t miss any filings and your records are complete.
How can Arnifi help with Singapore fund compliance?
Arnifi provides structured corporate support for Singapore entity formation, VCC structuring, corporate documentation, and statutory filing coordination. Arnifi also assists with company secretary arrangements and with ongoing corporate compliance.
From getting the right entity structure in place through to managing the various corporate formalities, Arnifi helps to take the administrative burden out of setting up and running a business in Singapore.
FAQs
Is an annual audit mandatory for a Singapore VCC?
Yes. Every VCC must be subject to an annual audit and cannot take advantage of the normal small company audit exemptions under the Companies Act.
When is a VCC required to appoint an auditor in Singapore?
A VCC must appoint at least one auditor within three months of incorporation.
Does an umbrella VCC require separate financial statements for each sub-fund?
Yes. Each sub-fund must have its own set of accounting records and financial information and must produce its own financial statements and annual returns.
When must a Singapore VCC file its annual return?
A VCC must file its annual return following its AGM and within seven months of the end of its financial year.
What accounting standards may a Singapore VCC use?
A VCC must conform to the accounting framework that applies to its financial statements under Singapore’s statutory requirements. The appropriate framework will be determined based on the fund’s circumstances.
Are the MAS reporting requirements the same for all Singapore funds?
No. The requirements are different for the various types of authorised schemes, the various types of restricted schemes and other private fund structures.
Can a small Singapore fund be exempt from an annual audit?
A VCC cannot avail itself of the standard small company audit exemptions. Other fund structures will have different audit requirements depending on their form of legal structure and the relevant regulations.
Conclusion
Singapore fund audit requirements extend beyond appointing an independent auditor. Funds must maintain accurate accounting records, prepare appropriate financial statements, meet filing deadlines and fulfil investor and regulatory reporting obligations.
The exact requirements depend on the fund’s legal structure and regulatory classification. Establishing an audit and reporting calendar early helps fund managers maintain transparency, meet statutory obligations and manage ongoing compliance more effectively. Contact us at Arnifi today for a compliant and structured setup experience.
References
ACRA: Overview of Managing a VCC
Top Singapore Packages
Related Articles
Top Singapore Packages
Planning Your Next Business Move?
