
Mandatory CSP Appointment for DIFC Prescribed Companies (SPVs) | What You Need to Know
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: Since 24 July 2026, non-exempt DIFC Prescribed Companies must appoint and continuously maintain an eligible Corporate Service Provider (CSP). Existing non-exempt Prescribed Companies incorporated before that date have until 24 January 2027 to comply.
Table of contents
- What changed for DIFC Prescribed Companies in 2026?
- What is a DIFC Prescribed Company?
- Why is a CSP now mandatory?
- Who can qualify as an Exempt Prescribed Company?
- What does the CSP do?
- Can a Prescribed Company use its CSP’s office address?
- What records must a Prescribed Company keep updated?
- What are the AML/CFT/CPF and financial crime considerations?
- When must existing Prescribed Companies appoint a CSP?
- What happens if a Prescribed Company does not comply?
- What should existing Prescribed Company owners do now?
- FAQs
- Conclusion
What changed for DIFC Prescribed Companies in 2026?
The DIFC Prescribed Company regime changed significantly when the Prescribed Company Regulations 2026 came into force on 24 July 2026.
The revised framework has broadened access to Prescribed Companies while introducing stronger governance, recordkeeping and compliance requirements. One of the most significant changes is the mandatory appointment of a Corporate Service Provider for every Prescribed Company that does not qualify as an Exempt PC.
The previous regime included eligibility requirements connected with the applicant, purpose of the company or its DIFC/GCC connection. These restrictions have now been removed, allowing a much wider range of international individuals and corporate groups to establish Prescribed Companies.
That wider access comes with a more structured compliance framework. Owners now need to consider CSP arrangements, ownership information, accounting records, regulatory filings and ongoing due diligence from the outset.
What is a DIFC Prescribed Company?
A DIFC Prescribed Company is a specialised structuring vehicle that can be used for holding and other permitted purposes. It is commonly used in structures involving:
- Shares in subsidiaries or other companies
- Investments and financing rights
- Family wealth and succession-planning arrangements
- Eligible assets and holding structures
- Special purpose structures permitted under the DIFC framework
A Prescribed Company can appoint directors and engage professional advisers, including CSPs, lawyers and accountants.
However, it is not designed to operate like an ordinary commercial company. Its licence is restricted to holding company activity unless a specific permitted purpose applies, and the company cannot employ employees or other workers.
What can a Prescribed Company not ordinarily do?
A Prescribed Company should not be treated as a substitute for an operating business. It generally cannot:
- Conduct an active commercial business
- Employ staff
- Provide regulated financial services without the required DFSA authorisation
- Operate outside the activities permitted by its licence
The regulations expressly state that a Prescribed Company cannot provide Financial Services unless authorised by the DFSA.
This makes it important to establish the intended purpose and activities before incorporation.
Why is a CSP now mandatory?
Under the 2026 Regulations, a non-exempt Prescribed Company must appoint a Corporate Service Provider to act on its behalf for specified regulatory and administrative purposes. The CSP is defined under the DIFC framework as a person registered with the DFSA as a Designated Non-Financial Business or Profession undertaking corporate services business in the DIFC.
The requirement is not limited to incorporation. The Prescribed Company must continuously maintain the required CSP relationship unless it qualifies as an Exempt PC.
For existing companies that were incorporated before the new Regulations came into force, the transitional period runs for six months from the enactment date.
Who can qualify as an Exempt Prescribed Company?
The CSP requirement does not apply where a Prescribed Company qualifies as an Exempt PC.
Under the 2026 Regulations, an Exempt PC is one where the Controller is:
| Controller | Exemption category |
| DIFC Registered Person | Exempt PC |
| DFSA Authorised Firm | Exempt PC |
| Government Entity | Exempt PC |
| Publicly Listed Entity | Exempt PC |
The basis for exemption should be established and documented rather than assumed. The regulations also exclude certain entities from the definition of Registered Person, including Foundations and Prescribed Variable Capital Companies. This means structures involving these entities require particular attention when determining whether an exemption is actually available.
Exemption status should also be reviewed when ownership, control or group structures change.
What does the CSP do?
The CSP becomes the Prescribed Company’s main administrative and compliance interface with the DIFC Registrar.
Its responsibilities can include:
- Lodging required documents, forms and fees
- Making regulatory filings and notifications
- Maintaining copies of required corporate records
- Keeping records accessible for regulatory purposes
- Supporting licence and compliance administration
- Acting on behalf of the company in dealings with the Registrar
The CSP must keep copies of relevant records up to date and readily accessible. The Prescribed Company, in turn, must provide the information and documents the CSP needs to perform its duties.
This makes the CSP relationship an ongoing compliance arrangement rather than a service used only when the annual licence renewal is due.
Can a Prescribed Company use its CSP’s office address?
Yes, subject to the applicable requirements and the CSP’s consent.
Under the 2026 Regulations, the registered office of a non-exempt Prescribed Company can generally be the registered office of its appointed CSP. An Exempt PC can use the registered office of an Affiliate where the relevant requirements are satisfied.
Using the CSP’s address can give the Prescribed Company an established DIFC registered office for official correspondence and regulatory communications.
What records must a Prescribed Company keep updated?
A Prescribed Company needs to maintain appropriate corporate and accounting records and provide relevant information to its CSP promptly.
This can include:
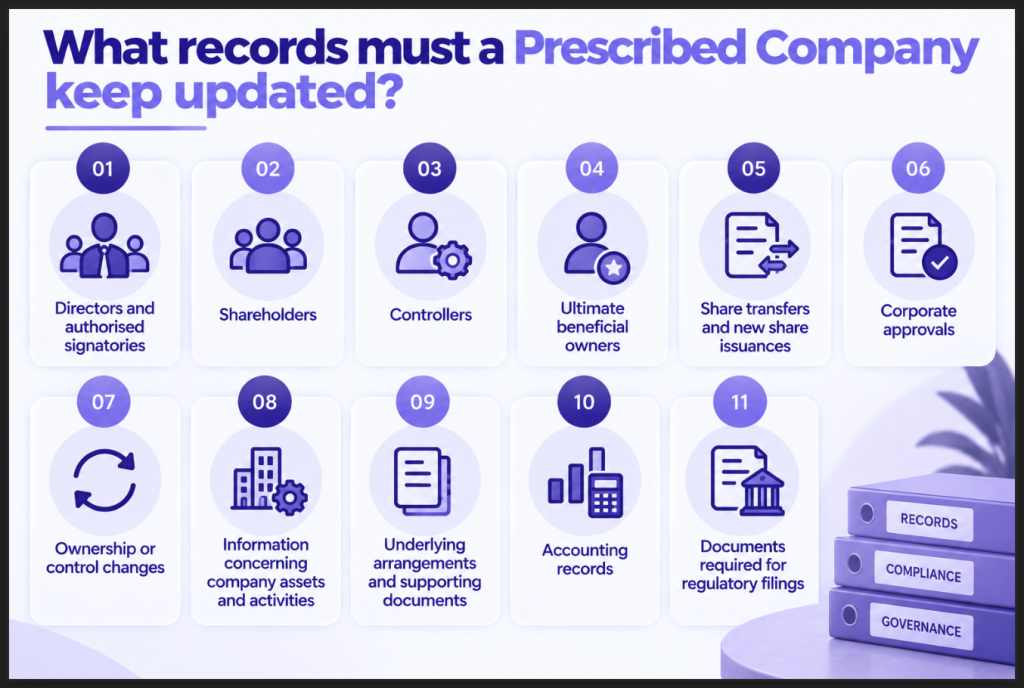
The Regulations require Prescribed Companies to maintain accounting records and prepare accounts as required under the DIFC Companies Law.
A failure to make required information and documents available to the CSP can attract an administrative fine of up to USD 100,000.
What are the AML/CFT/CPF and financial crime considerations?
The broader international accessibility of the Prescribed Company regime also means that ownership and financial crime risks need to be properly assessed.
Depending on the structure and risk profile, due diligence may involve:
- Identifying individuals who ultimately own or control the company
- Understanding the purpose and rationale for the structure
- Source of wealth and source of funds checks
- Sanctions screening
- Politically exposed person (PEP) screening
- Adverse media checks
- Country and jurisdiction risk
- Industry and activity risk
These checks should not be treated as a one-time incorporation exercise. Ownership, control, activities and other relevant circumstances should be reassessed when material changes occur.
When must existing Prescribed Companies appoint a CSP?
The transitional deadline applies to non-exempt Prescribed Companies incorporated before 24 July 2026.
They have six months from the enactment of the 2026 Regulations to appoint an eligible CSP.
Deadline: 24 January 2027
Existing owners should therefore review their arrangements before the deadline rather than waiting until the final weeks.
A practical review should cover:
- Determine whether the company qualifies as an Exempt PC.
- Document the basis for any exemption.
- Confirm the CSP’s current regulatory status.
- Review corporate and beneficial ownership records.
- Identify missing documents and outstanding filings.
- Confirm that activities remain within the licence scope.
- Review AML/CFT/CPF and sanctions-risk assessments.
- Address inconsistencies or compliance gaps.
- Complete the CSP appointment where required before 24 January 2027.
The six-month transition and 24 January 2027 deadline are expressly reflected in the Regulations.
What happens if a Prescribed Company does not comply?
Non-compliance can have both financial and structural consequences.
| Non-compliance | Potential consequence |
| Failure to appoint a required CSP | Fine of up to USD 20,000 |
| Failure to provide required information/documents to CSP | Fine of up to USD 100,000 |
| Failure by CSP to submit required cessation notice | Fine of up to USD 2,000 |
| Serious or continuing non-compliance | Potential revocation of Prescribed Company status |
The regulations specifically provide for a maximum USD 20,000 fine where a Prescribed Company fails to comply with the CSP appointment requirement and a maximum USD 100,000 fine where it fails to make required documents and information available to its CSP.
The Registrar may also revoke Prescribed Company status where the company fails to comply with the Regulations. Once status is revoked, the company loses the relevant exemptions and concessions available to Prescribed Companies and becomes subject to the applicable requirements for ordinary DIFC entities.
This can increase administrative and operating costs and disrupt structures created for investment holding, financing or succession planning.
What should existing Prescribed Company owners do now?
The most practical approach is to complete a compliance review before the January 2027 deadline.
Start with the following:
| Review area | What to confirm |
| Exemption | Whether the company qualifies as an Exempt PC |
| CSP | Whether appointment is required and whether the provider is eligible |
| Ownership | Directors, shareholders, Controllers and UBO information |
| Records | Corporate and accounting records are complete |
| Filings | Outstanding Registrar filings or notifications |
| Activities | Current activities remain within the licence |
| AML/CFT/CPF | Risk assessments and due diligence remain appropriate |
| Registered office | Current address and CSP arrangements are valid |
| Remediation | Missing information or compliance gaps have an action plan |
The earlier this review begins, the more time there is to resolve ownership-record discrepancies, complete due diligence or replace an unsuitable service provider.
FAQs
What is a DIFC Prescribed Company?
A DIFC Prescribed Company is a specialised DIFC vehicle primarily used for holding and permitted structuring purposes. It is not intended to operate as a conventional active commercial business.
Is a CSP mandatory for every DIFC Prescribed Company?
No. A non-exempt Prescribed Company must appoint and continuously maintain an eligible CSP. An Exempt PC is not subject to the mandatory CSP requirement.
Who can qualify for Exempt PC status?
The Controller must fall within one of the specified categories: a DIFC Registered Person, Authorised Firm, Government Entity or Publicly Listed Entity. The exemption should be properly established and documented.
What is the deadline for existing non-exempt Prescribed Companies?
Prescribed Companies incorporated before 24 July 2026 have six months to appoint an eligible CSP. The resulting deadline is 24 January 2027.
What happens if a Prescribed Company does not appoint an eligible CSP?
It may face a fine of up to USD 20,000. Continued non-compliance can also result in revocation of Prescribed Company status.
Can a Prescribed Company conduct an active business or employ staff?
A Prescribed Company is not intended to operate as an active commercial business and cannot employ employees or other workers. Its licence is restricted to permitted holding-company or qualifying-purpose activities.
Can a Prescribed Company use its CSP’s office as its registered office?
Yes, the 2026 Regulations allow the registered office of an appointed CSP to be used, subject to the applicable requirements and consent.
What records must a Prescribed Company keep updated?
It should maintain appropriate corporate and accounting records, including information relating to directors, shareholders, Controllers, beneficial owners, ownership changes, assets, activities and required regulatory filings.
Does a Prescribed Company need ongoing AML/CFT/CPF and sanctions compliance?
Yes. Applicable AML requirements and other relevant DIFC requirements continue to apply. Due diligence and risk assessments should also be revisited when material circumstances change.
Can a Prescribed Company lose its prescribed status for non-compliance?
Yes. The Registrar may revoke Prescribed Company status where the company fails to comply with the applicable Regulations. Following revocation, the company loses the relevant Prescribed Company exemptions and concessions.
Conclusion
The 2026 DIFC Prescribed Company Regulations have opened the structure to a much broader international audience while introducing stronger ongoing compliance requirements. For non-exempt companies, maintaining an eligible CSP is now a continuing obligation. Existing companies should review exemption status, ownership records, CSP arrangements, licence activities and financial crime controls well before 24 January 2027.
Official references
Top UAE Packages

Related Articles
Top UAE Packages
Get in Touch