
Countries With No Corporate Tax in 2026 | Full List of 0% Corporate Tax Countries
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Facts: Countries with no general corporate tax include the Cayman Islands, Bahamas, BVI, Bermuda, Bahrain and several other jurisdictions. However, 0% corporate tax does not necessarily mean zero overall taxation, and Pillar Two can affect large multinational groups.
Table of contents
- Introduction
- Countries With No Corporate Tax in 2026
- What Does 0% Corporate Tax Actually Mean?
- Full List of Countries and Jurisdictions With No General Corporate Tax
- Countries With Conditional 0% Corporate Tax
- Best Zero Corporate Tax Jurisdictions by Business Type
- Zero Corporate Tax vs Low Corporate Tax
- Do Zero Corporate Tax Countries Really Have No Taxes?
- How Pillar Two Affects Zero Corporate Tax Countries?
- Are Zero Corporate Tax Countries Legal?
- Countries vs Territories: What Is the Difference?
- How to Choose a Zero Corporate Tax Jurisdiction?
- Common Mistakes When Choosing a Zero-Tax Jurisdiction
- FAQs
- Conclusion
Introduction
0% corporate tax doesn’t necessarily mean zero percent tax paid by a company. Some jurisdictions do not have any general corporate income tax; others have a zero rate only for some companies, activities, or income types. The difference is even more significant in 2026 due to international tax provisions like the 15% Pillar Two minimum tax. This is a real-world comparison of jurisdictions that have no general corporate tax, conditional 0% corporate tax regimes, and considerations for businesses before selecting a jurisdiction.
Countries With No Corporate Tax in 2026
The following jurisdictions are generally considered not to have a general corporate income tax: Anguilla, The Bahamas, Bahrain, Belize, Bermuda, the British Virgin Islands, the Cayman Islands, Guernsey, the Isle of Man, Jersey, Saint Barthélemy, Tokelau, Turks and Caicos Islands, Vanuatu, and Wallis and Futuna. But ‘0% ‘ doesn’t necessarily mean that all companies operating there are totally tax-free.
Full list of jurisdictions
| Jurisdiction | General corporate income tax |
| Anguilla | 0% |
| Bahamas | 0% |
| Bahrain | 0% |
| Belize | 0% |
| Bermuda | 0% |
| British Virgin Islands | 0% |
| Cayman Islands | 0% |
| Guernsey | 0% |
| Isle of Man | 0% |
| Jersey | 0% |
| Saint Barthélemy | 0% |
| Tokelau | 0% |
| Turks and Caicos Islands | 0% |
| Vanuatu | 0% |
| Wallis and Futuna | 0% |
Certain sectors, including oil and gas, can be subject to tax. Belize uses different taxes and business regimes, so 0% corporate income tax should not be read as no business taxation.
Bermuda introduced a corporate income tax for certain large multinational groups from 2025.
Some Guernsey companies and activities can be subject to higher rates. Certain Jersey activities are taxed at rates other than 0%.
What Does 0% Corporate Tax Actually Mean?
0% statutory corporate tax
A jurisdiction may have no general corporate income tax imposed on companies. This is the clearest form of a zero-tax corporate regime.
0% qualifying corporate tax
Some jurisdictions apply 0% only when a company meets specific conditions. The rate therefore depends on the business activity, income source or company structure.
0% headline rate vs 15% global minimum tax
A 0% local rate does not necessarily mean a large multinational group will ultimately face a 0% effective tax rate. Pillar Two can bring the effective rate up to 15% for businesses within its scope.
Why “tax-free” doesn’t mean tax-free
A company can still face VAT or GST, withholding taxes, payroll costs, licence fees, customs duties and other government charges.
Full List of Countries and Jurisdictions With No General Corporate Tax
Anguilla
Anguilla has no general corporate income tax, although businesses can still face other government charges and indirect taxes.
Bahamas
The Bahamas does not generally impose corporate income tax. Businesses may instead deal with VAT, business licence fees and other local charges.
Bahrain
Bahrain generally has no broad corporate income tax, although specific industries, particularly hydrocarbons, are treated differently.
Belize
Belize does not operate a conventional broad corporate income tax in the same way as many countries. Businesses should still assess the applicable business tax and other obligations.
Bermuda
Bermuda has traditionally been known for its 0% corporate tax environment, but large multinational groups within the scope of its new corporate income tax rules need separate analysis.
British Virgin Islands
The BVI has no general corporate income tax. Companies still have registration, annual filing and other compliance obligations.
Cayman Islands
The Cayman Islands does not generally impose corporate income tax, making it a major jurisdiction for investment funds, holding structures and SPVs.
Guernsey
Guernsey generally applies a 0% corporate tax rate, although certain businesses and income streams can be taxed at higher rates.
Isle of Man
The Isle of Man generally has a 0% corporate income tax rate, subject to specific exceptions.
Jersey
Jersey generally taxes companies at 0%, with certain financial and regulated activities subject to different rates.
Saint Barthélemy
Saint Barthélemy has a distinct tax regime and can provide favourable treatment depending on the company’s circumstances and tax residence.
Tokelau
Tokelau is among the territories commonly listed as having no general corporate income tax.
Turks and Caicos Islands
The Turks and Caicos Islands generally has no corporate income tax, although businesses remain subject to other local charges.
Vanuatu
Vanuatu does not generally impose corporate income tax. Businesses should still consider VAT, licensing and other operating costs.
Wallis and Futuna
Wallis and Futuna has a distinct local tax framework and is commonly included in lists of jurisdictions without a general corporate income tax.
Countries With Conditional 0% Corporate Tax
UAE Free Zones
The UAE now has a federal Corporate Tax regime. Certain Free Zone businesses can still benefit from a 0% Corporate Tax rate on qualifying income, provided they meet the requirements for a Qualifying Free Zone Person.
Hong Kong offshore profits
Hong Kong follows a territorial approach. Profits that are genuinely sourced outside Hong Kong may receive different treatment, but the rules depend on the source of the income and the facts of the business.
Estonia retained profits
Estonia generally taxes corporate profits when they are distributed rather than simply because they are earned and retained. This makes the system different from a traditional 0% corporate tax model.
Other conditional regimes
Several jurisdictions offer exemptions, special rates or preferential regimes for particular activities. These should not automatically be described as “zero corporate tax countries.”
Best Zero Corporate Tax Jurisdictions by Business Type
There is no single best jurisdiction for every business.
| Business type | Jurisdictions often considered |
| Holding companies | Cayman Islands, BVI, Jersey |
| Investment funds | Cayman Islands, Jersey, Guernsey |
| SPVs | Cayman Islands, BVI |
| Insurance | Bermuda, Cayman Islands |
| GCC businesses | Bahrain, UAE qualifying Free Zones |
| Fintech | Depends heavily on regulation |
| International trading | UAE, Hong Kong and selected offshore jurisdictions |
The right choice depends on substance, banking, regulation, ownership and where the business actually operates.
Zero Corporate Tax vs Low Corporate Tax
A 0% rate is not automatically better than a low-tax regime.
| Corporate tax range | General examples |
| 0% | Cayman Islands, BVI, Bahamas |
| 1–5% | Selected special regimes |
| 6–10% | Various low-tax jurisdictions |
| 10–15% | Several competitive corporate tax systems |
A jurisdiction with a 5% or 10% rate may sometimes offer better banking, tax treaties, substance options or international credibility than a 0% offshore jurisdiction.
Do Zero Corporate Tax Countries Really Have No Taxes?
Not necessarily. Businesses may still pay:
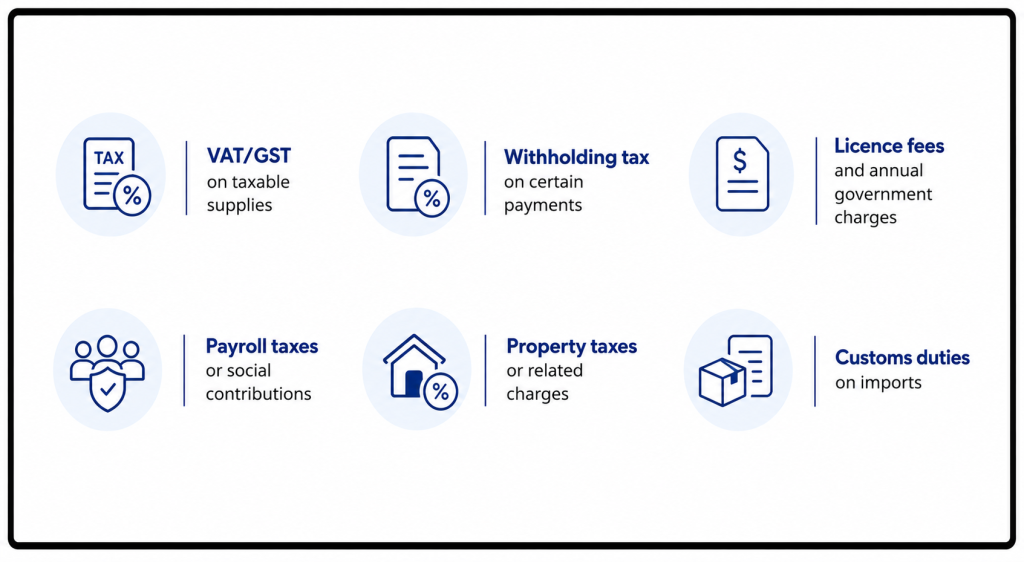
The actual cost of operating a company should therefore be assessed beyond the headline corporate tax rate.
How Pillar Two Affects Zero Corporate Tax Countries?
What is Pillar Two?
Pillar Two is part of the OECD/G20 international tax framework designed to establish a 15% global minimum effective tax rate for large multinational groups.
Who is affected?
It primarily targets multinational enterprise groups that meet the applicable revenue threshold.
The EUR 750 million threshold
The rules generally apply to groups with €750 million or more in consolidated annual revenue, subject to the detailed Pillar Two rules.
QDMTT
A Qualified Domestic Minimum Top-up Tax (QDMTT) allows a jurisdiction to collect additional tax locally where the relevant effective tax rate falls below the minimum.
Why 0% can become 15% for large MNEs
A 0% local corporate tax rate can therefore have a very different outcome for a qualifying multinational group. The group may face a top-up tax to reach the required 15% effective rate.
Are Zero Corporate Tax Countries Legal?
Yes. Using a jurisdiction with a legitimate 0% or low-tax regime is not, by itself, illegal. The issue is whether the structure complies with the tax laws of every relevant country.
Tax avoidance vs tax evasion
Tax evasion involves illegally hiding income or misrepresenting information. Tax planning uses legally available rules to structure a business efficiently.
Economic substance
Some jurisdictions require companies carrying out certain activities to demonstrate appropriate local substance.
CFC rules
A shareholder’s home country may apply Controlled Foreign Company rules, potentially taxing certain foreign company income.
Permanent establishment
Operating a business from another country can create a permanent establishment and local tax exposure even when the company itself is incorporated in a 0% jurisdiction.
Transfer pricing
Related-party transactions may need to follow applicable arm’s-length pricing rules.
Beneficial ownership
Companies may also have beneficial ownership disclosure and reporting obligations.
Countries vs Territories: What Is the Difference?
Not every location on a “zero corporate tax” list is an independent country. Some are overseas territories, dependencies or jurisdictions with their own tax systems. That distinction matters when considering tax treaties, banking, regulation, company law and international reporting.
How to Choose a Zero Corporate Tax Jurisdiction?
Business activity
Start with the activity, because some jurisdictions restrict financial, investment or regulated businesses.
Ownership
Check whether foreign shareholders can own the company and whether local directors are required.
Residence
Consider where the owners and management are tax resident.
Banking
A 0% tax rate is of limited value if opening and maintaining a suitable corporate bank account is difficult.
Substance
Check whether the company needs local offices, employees, directors or other economic substance.
Reputation
A well-regulated jurisdiction may be more practical for investors, banks and commercial partners.
Compliance
Look at annual filings, accounting, beneficial ownership and tax reporting requirements.
Tax treaties
Treaty access can be important for international businesses receiving dividends, interest or royalties.
Common Mistakes When Choosing a Zero-Tax Jurisdiction
The most common mistakes include assuming 0% means no taxes, ignoring CFC rules, choosing a jurisdiction before confirming the business activity, overlooking substance requirements, underestimating banking requirements, relying on outdated tax information, and comparing only incorporation costs instead of the total annual cost.
FAQs
1. What countries have 0 corporate tax?
Several jurisdictions have no general corporate income tax, including the Cayman Islands, BVI, Bahamas, Bermuda, and others listed above.
2. Which country has no corporate tax?
There is no single answer. Cayman Islands, Bahamas, and BVI are well-known examples.
3. Which countries have no income tax?
Examples include the UAE, Bahamas, Bahrain, and Cayman Islands, although the exact meaning of “no income tax” differs by jurisdiction.
4. Which countries have no capital gains tax?
Several jurisdictions do not generally impose capital gains tax, but local rules and the taxpayer’s residence still matter.
5. Which country is tax-free?
No country should automatically be treated as completely tax-free. Businesses and individuals can still face other taxes and government charges.
6. What countries don’t pay taxes?
Businesses and individuals may still have tax obligations even in jurisdictions with 0% corporate or personal income tax.
7. Which countries have low tax rates?
The UAE, Bahrain, Hong Kong and several other jurisdictions are commonly considered competitive, depending on the type of income.
8. What countries have the lowest corporate tax rates?
Some jurisdictions have 0% rates, while others offer rates below 15%. The lowest rate is not necessarily the most suitable.
9. Which countries have zero capital gains tax?
The Cayman Islands, BVI and Bahamas are examples often considered for their treatment of capital gains.
10. What are the best options for a low-tax environment?
The best option depends on the business model, ownership, banking needs, substance and target markets.
11. Which jurisdictions offer strong holding company structures?
Cayman Islands, BVI, Jersey and Guernsey are commonly considered for different holding and investment structures.
12. Are zero-tax jurisdictions legal?
Yes. Incorporating in a 0% jurisdiction is legal when the company and its owners comply with applicable tax and reporting laws.
13. Do zero-tax companies still need accounting?
Yes. Accounting, annual filings, and corporate records may still be required.
14. Can a 0% company avoid tax in my home country?
Not necessarily. Your home country may apply CFC, residency, permanent establishment, or other rules.
15. Does Pillar Two affect every 0% company?
No. Pillar Two primarily applies to large multinational groups meeting the relevant €750 million threshold.
Conclusion
A 0% corporate tax rate can be attractive, but it should never be the only factor in choosing where to establish a business. The better question is whether the jurisdiction fits your business activity, ownership, banking, substance, and long-term tax position. For large multinational groups, Pillar Two also means that a headline 0% rate may not translate into a final 0% effective tax rate. Therefore, Arnifi helps businesses compare jurisdictions, assess business activities, establish companies and manage the practical requirements around incorporation, banking, tax and ongoing compliance.
References:
Top UAE Packages
Related Articles
Top UAE Packages
Get in Touch
