
VAT Deregistration in UAE | What to Check Before Closing Your TRN
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: The FTA charges no government service fee for VAT deregistration. Mandatory applications must be submitted within 30 business days of the obligation arising. The FTA’s current processing estimate is 30 business days for a completed application.
Table of contents
- Introduction
- What Should You Check Before Cancelling Your UAE VAT Registration?
- When Is VAT Deregistration Mandatory, and When Can It Be Voluntary?
- How Do VAT Thresholds Affect Your Deregistration Decision?
- What Is the VAT Deregistration Deadline in the UAE?
- Which Documents Does the FTA Require for VAT Deregistration?
- How Do You Apply for VAT Deregistration Through EmaraTax?
- What Happens to Invoices, Contracts and Business Assets During VAT Deregistration?
- What Must You Do About the Final VAT Return, Tax Payments and Refunds?
- How Much Does VAT Deregistration Cost in the UAE?
- How Long Does VAT Deregistration Take?
- What Should You Do After VAT Deregistration Is Approved?
- What Mistakes Can Delay or Complicate VAT Deregistration?
- How Can Arnifi Help With VAT Deregistration in the UAE?
- FAQs
- Conclusion
- Official References
Introduction
A business may close its doors, change its activities or see its turnover fall, but its VAT registration does not automatically close with it. VAT deregistration in the UAE requires an application to the Federal Tax Authority (FTA), supporting documents and a review of outstanding tax obligations. Before closing your Tax Registration Number (TRN), check your eligibility, deadlines, financial records and final VAT return.
What Should You Check Before Cancelling Your UAE VAT Registration?
Before opening an EmaraTax application, establish why the business needs to deregister. The reason affects the eligibility conditions, documents and application route.
| Situation | What to check |
| Business has permanently stopped trading | Whether taxable supplies have ceased and mandatory deregistration conditions are met |
| Turnover has declined | Whether taxable supplies meet the relevant deregistration conditions |
| Company is being liquidated | Licence cancellation, liquidation documents and outstanding tax obligations |
| Business activities have changed | Whether remaining activities still involve taxable supplies |
| Business has been sold or restructured | Whether the existing registration remains appropriate and who is responsible for outstanding obligations |
| Multiple registrations exist | Whether the issue involves a duplicate TRN, branch or individual establishment registration |
A fall in revenue does not automatically qualify a business for deregistration. Check the applicable rules and document the reason before applying.
When Is VAT Deregistration Mandatory, and When Can It Be Voluntary?
Mandatory deregistration applies when the business meets the relevant legal conditions. This may include ceasing to make taxable supplies without intending to resume them within the relevant period, or falling below the voluntary registration threshold without expecting to exceed it in the next 30 days.
Voluntary deregistration may be available when the business continues making taxable supplies but meets the applicable conditions, including having taxable supplies below the mandatory registration threshold. The FTA must assess the circumstances before approving deregistration.
A business that registered voluntarily generally cannot apply for voluntary deregistration during its first 12 months of registration. The applicable conditions and exceptions should be checked before applying.
Use the FTA’s current VAT deregistration guidance and self-assessment tool to establish which route applies to your business.
How Do VAT Thresholds Affect Your Deregistration Decision?
The UAE has two main VAT registration thresholds:
| Threshold | Amount | Relevance |
| Mandatory VAT registration | ~AED 375,000 | Relevant to mandatory registration and the applicable deregistration assessment |
| Voluntary VAT registration | ~AED 187,500 | Relevant to voluntary registration and certain deregistration conditions |
The assessment depends on the applicable deregistration basis and may consider taxable supplies, imports, taxable expenses and expected future activity. Review the relevant figures and conditions before deciding whether the business qualifies.
What Is the VAT Deregistration Deadline in the UAE?
The FTA’s current service guidance requires mandatory deregistration applications to be submitted within 30 business days from the date the deregistration obligation arises.
Businesses should record the relevant date, such as when taxable supplies ceased or the applicable registration conditions changed. Keep supporting records that explain how the date was determined.
The application deadline is separate from the deadline for the final VAT return. Missing the mandatory application deadline may result in an administrative penalty, so check the applicable requirements as soon as the business becomes eligible or required to deregister.
Which Documents Does the FTA Require for VAT Deregistration?
The FTA’s document requirements depend on the reason selected in the application. Common documents include the following:
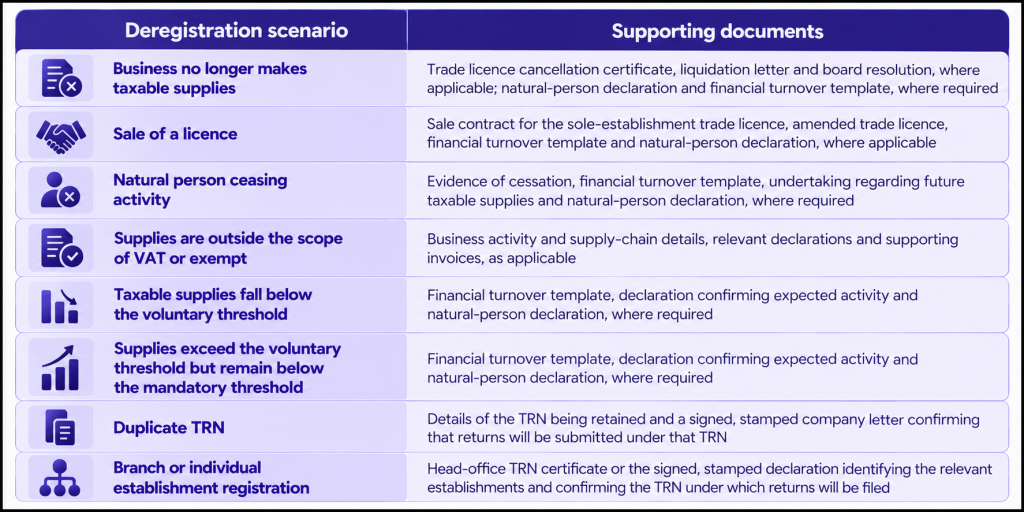
Keep your VAT certificate, latest VAT return, owner or manager identification and relevant financial or liquidation documents available when preparing your records. Not every document applies to every case, and the FTA may request further evidence.
How Do You Apply for VAT Deregistration Through EmaraTax?
The application is submitted through the EmaraTax account associated with the business’s VAT registration.
| Step | Action |
| 1 | Confirm the deregistration reason and eligibility conditions. |
| 2 | Establish the relevant date and submission deadline. |
| 3 | Review outstanding VAT returns, liabilities and penalties. |
| 4 | Prepare the financial information and supporting documents. |
| 5 | Sign in to the relevant EmaraTax account. |
| 6 | Open the taxable person account and select VAT under the available actions. |
| 7 | Choose the deregistration option and complete the application. |
| 8 | Upload the documents and review the application details. |
| 9 | Submit the application and monitor its status. |
| 10 | Respond to information requests and retain the FTA’s decision. |
Submitting an application does not immediately cancel the VAT registration. Incomplete information or missing documents may delay the process.
What Happens to Invoices, Contracts and Business Assets During VAT Deregistration?
Review transactions around the effective deregistration date before closing the VAT account. Open contracts, unpaid invoices, remaining stock and business assets may affect the final VAT position.
Do not stop accounting for VAT simply because the application has been submitted. Check whether remaining assets or stock trigger VAT adjustments or deemed-supply rules, where applicable. Reconcile sales records, purchase records and the VAT control account before filing the final return.
What Must You Do About the Final VAT Return, Tax Payments and Refunds?
The final VAT return closes out the business’s VAT position for the relevant final tax period. The FTA requires the final return to be submitted and payable tax settled no later than 28 days from the effective deregistration date.
Before completing the process:
- Review and file outstanding VAT returns.
- Calculate and settle any outstanding VAT liabilities.
- Check whether administrative penalties remain unpaid.
- Review any VAT refund due and follow the applicable FTA refund process.
- Retain payment confirmations and supporting records.
The FTA makes the digital deregistration certificate available after the application is approved and the relevant final return, tax payment and outstanding liability requirements have been met. Deregistration does not erase liabilities from earlier periods.
How Much Does VAT Deregistration Cost in the UAE?
The FTA’s VAT deregistration application is free of government service fees. Professional assistance is a separate cost.
| Cost component | What it covers |
| FTA application | No government service fee |
| Professional assistance | Application preparation and coordination |
| Financial records | Preparation or finalisation of supporting information, where needed |
| Outstanding tax | VAT payable by the business |
| Administrative penalties | Any applicable unpaid penalties |
| Company closure | Separate liquidation or trade licence cancellation costs, where relevant |
How Long Does VAT Deregistration Take?
The FTA’s current processing estimate is 30 business days from receipt of a completed application. If additional information is required, the FTA may take a further 30 business days to respond after the updated information is submitted.
Incomplete documents, inconsistent financial records and unresolved compliance issues can extend the overall timeline. The estimated processing period is not a guarantee of approval.
What Should You Do After VAT Deregistration Is Approved?
After approval, download and retain the digital deregistration certificate from EmaraTax. Then update your accounting records, invoice templates and internal tax files to reflect the new registration status.
Keep financial records and supporting documents for the applicable retention period. Also check whether Corporate Tax registration, the trade licence or other regulatory registrations need separate action. VAT deregistration does not automatically cancel them.
If the business resumes activities or its taxable turnover changes, reassess whether VAT registration is required.
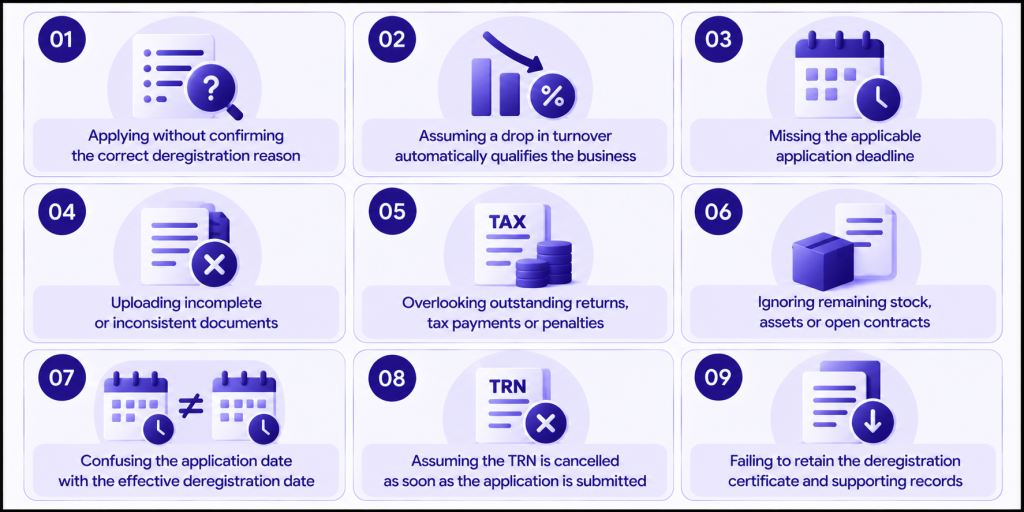
What Mistakes Can Delay or Complicate VAT Deregistration?
Avoid these common mistakes:
How Can Arnifi Help With VAT Deregistration in the UAE?
Closing a VAT registration involves more than submitting an online request. Businesses need to identify the correct deregistration route, organise supporting documents and review outstanding tax obligations. If your business has closed, changed activities or no longer meets the relevant registration conditions, explore Arnifi’s VAT deregistration service.
FAQs
1. When should a business deregister for VAT in the UAE?
A business should assess deregistration when it stops making taxable supplies or meets another applicable mandatory or voluntary deregistration condition.
2. What is the VAT deregistration deadline?
The FTA’s current service guidance requires mandatory applications within 30 business days of the date the deregistration obligation arises.
3. Can a business deregister if its turnover falls below ~AED 187,500?
It may qualify, depending on the applicable conditions and expected activity. Turnover alone should not be treated as confirmation of eligibility.
4. What documents are required for VAT deregistration?
Requirements depend on the reason for deregistration. They may include licence cancellation documents, financial statements, turnover information, declarations and supporting evidence.
5. Does a business need to file a final VAT return?
Yes. The final return must be filed and payable tax settled within the applicable period. The FTA’s service guidance specifies 28 days from the effective deregistration date.
6. How much does VAT deregistration cost?
The FTA application is free of government service fees. Professional assistance and any outstanding tax or penalties may involve separate costs.
7. How long does the FTA take to process a VAT deregistration application?
The current estimate is 30 business days for a completed application. Requests for additional information may extend the timeline.
8. Does VAT deregistration cancel Corporate Tax registration?
No. VAT and Corporate Tax are separate registrations and must be handled independently.
Conclusion
Confirming your eligibility, preparing required records and ensuring proper documentation is of utmost priority before you close your UAE VAT registration. Before submitting the final application through EmaraTax, one should review outstanding returns and tax liabilities along with any open transactions. If you are looking for professional guidance in preparing the documents and coordinating the processes of VAT deregistration, reach out to us at Arnifi today.
Official References
Top UAE Packages
Related Articles
Top UAE Packages
Get in Touch
