
Two CbCR Filings Due 31 October 2026 | UAE Reporting Guide
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: For an eligible UAE-headquartered multinational group with a financial year ending 31 October, the CbCR notification for the year ending 31 October 2026 and the CbC Report for the year ended 31 October 2025 are both due by 31 October 2026.
Table of contents
- Why Are Two CbCR Filings Due on 31 October 2026?
- Which Multinational Groups Must File CbCR in the UAE?
- What Is the UAE CbCR Notification for the Year Ending 31 October 2026?
- What Is the CbC Report for the Financial Year Ended 31 October 2025?
- What Financial Information Must the CbC Report Include?
- What Constituent Entity Details Must Be Reported?
- What Format Must the CbC Report Follow?
- How Should Businesses Prepare for Both CbCR Deadlines?
- What Happens After the 31 October 2026 CbCR Deadline?
- How Can Arnifi Help Businesses With UAE CbCR Compliance?
- FAQs
- Conclusion
Why Are Two CbCR Filings Due on 31 October 2026?
The UAE’s CbCR framework operates under Cabinet Resolution No. 44 of 2020, which regulates reporting by qualifying multinational enterprise (MNE) groups. It separates the notification requirement from the obligation to submit a full CbC Report.
For an eligible UAE-headquartered group with a financial year ending on 31 October, the two obligations fall on the same date because they relate to different reporting periods.
| Filing | Reporting period | Deadline |
| CbCR notification | Financial year ending 31 October 2026 | 31 October 2026 |
| Full CbC Report | Financial year ended 31 October 2025 | 31 October 2026 |
The notification identifies the entity responsible for reporting for the current financial year. The full report provides financial and operational information about the group’s activities across tax jurisdictions for the preceding year.
These are separate submissions. Completing one does not replace the other.
Which Multinational Groups Must File CbCR in the UAE?
CbCR requirements apply to qualifying multinational groups that meet the conditions under the UAE framework. The relevant threshold is consolidated group revenue of AED 3.15 billion or more during the fiscal year immediately preceding the reporting fiscal year.
A group must first meet the definition of an MNE group. This generally includes a group with:
- Two or more entities that are tax-resident in different jurisdictions
- One entity that conducts business through a permanent establishment in another jurisdiction
For the UAE-headquartered reporting framework, the relevant conditions include the following:
- The group meets the MNE group definition
- Consolidated group revenue meets or exceeds AED 3.15 billion for the preceding fiscal year
- The Ultimate Parent Entity (UPE) is tax-resident in the UAE
- The UAE UPE is the Reporting Entity under the applicable framework
Meeting the revenue threshold alone does not automatically create a filing obligation. The group structure, tax residency and other applicable conditions must also be assessed.
The UAE framework identifies the qualifying UAE UPE as the Reporting Entity. Groups should confirm their reporting position against Cabinet Resolution No. 44 of 2020 and the Ministry of Finance’s current guidance before submitting a filing.
What Is the UAE CbCR Notification for the Year Ending 31 October 2026?
The CbCR notification informs the UAE Ministry of Finance about the Reporting Entity responsible for submitting the group’s CbC Report.
For an eligible UAE-headquartered group, the notification confirms that the UAE UPE is the Reporting Entity under the applicable framework.
The notification is different from the full report. It does not contain the complete jurisdiction-by-jurisdiction financial information required in the CbC Report.
For a group whose financial year ends on 31 October, the notification for the financial year ending 31 October 2026 is due by that date.
Businesses should prepare the notification before year-end and submit it through the Ministry of Finance’s designated reporting system. Leaving it until after the financial year closes may result in a missed deadline.
What Is the CbC Report for the Financial Year Ended 31 October 2025?
The CbC Report provides a consolidated view of a multinational group’s financial and economic activities across the tax jurisdictions in which it operates.
Under the UAE framework, the report includes information intended to help tax authorities assess how a group’s income, taxes and economic activities are distributed across jurisdictions.
For the financial year ended 31 October 2025, the report must be submitted by 31 October 2026.
The report covers information such as:
- Revenue and profit or loss before income tax
- Income tax paid and income tax accrued
- Stated capital and accumulated earnings
- Employee numbers and tangible assets
- The group’s constituent entities and their principal business activities
The figures must be organised by tax jurisdiction, with the relevant entity-level details included in the prescribed reporting format.
What Financial Information Must the CbC Report Include?
Article 3 of Cabinet Resolution No. 44 of 2020 sets out the information required in the CbC Report. The group must compile the relevant figures for each tax jurisdiction in which it operates.
| Financial information | What must be reported |
| Related-party revenue | Revenue from transactions with related parties |
| Unrelated-party revenue | Revenue from transactions with unrelated parties |
| Total revenue | Combined revenue from related and unrelated parties |
| Profit or loss before income tax | The jurisdiction’s aggregate profit or loss before income tax |
| Income tax paid | Income tax paid on a cash basis |
| Income tax accrued | Income tax accrued for the current fiscal year |
| Stated capital | Aggregate stated capital |
| Accumulated earnings | Aggregate accumulated earnings |
| Number of employees | Employee count for the relevant jurisdiction |
| Tangible assets | Tangible assets, excluding cash and cash equivalents |
The information should be consistent with the group’s underlying financial records and reporting data. Businesses may need to coordinate with finance, accounting and tax teams in several jurisdictions to collect complete figures.
Before submission, review the figures for completeness and consistency. Any differences between source records and the consolidated report should be investigated and documented.
What Constituent Entity Details Must Be Reported?
The CbC Report also identifies the constituent entities within the multinational group and describes their activities.
The report should include:
- The name of each constituent entity, grouped by tax jurisdiction
- The jurisdiction where each entity is tax-resident
- The jurisdiction under whose laws each entity was organised, where different
- The principal business activity or activities of each entity
The business activity descriptions should accurately reflect the role of each entity within the group. Examples include:
- Research and development
- Holding or managing intellectual property
- Purchasing
- Manufacturing
- Sales and distribution
- Administrative or support services
- Financing
- Insurance
- Holding shares or other equity instruments
A group should review its legal entity register and confirm that all relevant entities are included. Entity names, tax residency details and activity classifications should be checked before the report is finalised.
What Format Must the CbC Report Follow?
The report must follow the prescribed standard template under the UAE CbCR framework, based on Annex III to Chapter V of the OECD Transfer Pricing Guidelines, including applicable amendments.
The template contains three main tables.
| Table | Purpose |
| Table 1 | Reports jurisdiction-by-jurisdiction financial and economic figures |
| Table 2 | Lists constituent entities, their tax jurisdictions and business activities |
| Table 3 | Provides additional information or explanations needed to understand the report |
Using the prescribed structure helps ensure that the information is presented consistently. Businesses should organise their financial and entity-level data in the required format before submission rather than attempting to compile the report at the last minute.
The UAE Ministry of Finance provides the relevant CbCR guidance and reporting access through its official channels.
How Should Businesses Prepare for Both CbCR Deadlines?
Eligible groups should manage the notification and the full report as separate compliance tasks, with clear ownership and internal review dates.
A practical preparation checklist includes:
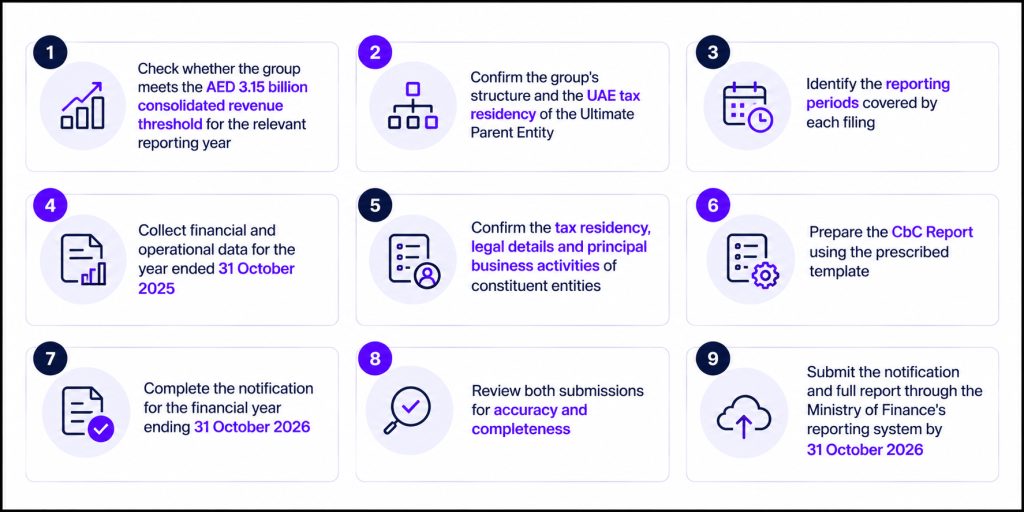
The official UAE Ministry of Finance CbCR notification and reporting portal provides access to the notification process. Businesses should use the relevant Ministry of Finance reporting channel for the full report and follow the current submission instructions.
What Happens After the 31 October 2026 CbCR Deadline?
For an eligible group that continues to have a 31 October financial year-end, the next reporting cycle follows the same general annual pattern.
| Filing | Reporting period | Deadline |
| CbCR notification | Financial year ending 31 October 2027 | 31 October 2027 |
| Full CbC Report | Financial year ended 31 October 2026 | 31 October 2027 |
The notification is due by the end of the current reporting fiscal year, while the full report is due within 12 months after the end of the financial year to which it relates.
Groups should confirm the applicable requirements each year, particularly if their financial year-end, group structure or reporting status changes.
How Can Arnifi Help Businesses With UAE CbCR Compliance?
CbCR compliance requires coordination across finance, tax and legal teams, particularly when a multinational group operates in several jurisdictions.
Arnifi can support businesses with corporate and tax compliance requirements within the scope of its services. For groups reviewing their UAE reporting obligations, professional support can help organise the compliance process and identify the information that needs to be reviewed before filing.
Businesses should confirm the group’s eligibility, reporting entity and applicable financial year before preparing a submission. Where specialist CbCR preparation or tax advice is required, the group should work with a qualified tax professional who can assess its circumstances against the UAE framework.
FAQs
Why are two CbCR filings due on 31 October 2026?
Eligible UAE-headquartered groups with a 31 October year-end may need to submit the notification for the year ending 31 October 2026 and the full CbC Report for the year ended 31 October 2025 by the same date.
Which UAE companies must file a CbCR notification?
The obligation depends on the applicable UAE CbCR rules, including the group structure, the UAE tax residency of the Ultimate Parent Entity and the consolidated revenue threshold. Businesses should confirm their eligibility under Cabinet Resolution No. 44 of 2020.
What is the UAE CbCR revenue threshold?
The threshold is consolidated group revenue of AED 3.15 billion or more in the fiscal year immediately preceding the relevant reporting fiscal year, subject to the other applicable conditions.
What information must a CbC Report contain?
The report includes jurisdiction-by-jurisdiction financial information, such as revenue, profit or loss before income tax, income tax paid and accrued, capital, accumulated earnings, employee numbers and tangible assets. It also identifies constituent entities and their business activities.
When is the CbCR notification due?
For an eligible group with a 31 October financial year-end, the notification is due on the last day of that financial year. The notification for the year ending 31 October 2026 is due by 31 October 2026.
When is the full CbC Report due?
The full report is due within 12 months after the end of the relevant financial year. For the year ended 31 October 2025, the deadline is 31 October 2026.
What are the deadlines for the next reporting cycle?
For an eligible group with a 31 October year-end, the notification for the year ending 31 October 2027 and the full CbC Report for the year ended 31 October 2026 are both due by 31 October 2027.
Conclusion
The UAE CbCR filing deadline of 31 October 2026 is significant for eligible UAE-headquartered multinational groups with a 31 October financial year-end. Two separate submissions may be required: the notification for the year ending 31 October 2026 and the full CbC Report for the year ended 31 October 2025.
Businesses should confirm the group’s eligibility, establish the correct Reporting Entity and prepare complete financial and constituent entity information well before the deadline. Planning for the next reporting cycle is equally important, with both the notification and full report deadlines falling on 31 October 2027 for groups that retain the same year-end.
Review the applicable UAE CbCR legislation and Ministry of Finance guidance before filing, and seek qualified tax advice where the group’s reporting obligations are uncertain.
Official References
Top UAE Packages
Related Articles
Top UAE Packages
Get in Touch
