
Bank NOC vs Developer NOC in Dubai | Requirements and Differences
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Table of contents
- What Is a Bank NOC in Dubai?
- What Is a Developer NOC in Dubai?
- Bank NOC vs Developer NOC | What Are the Main Differences?
- When Do You Need a Bank NOC or a Developer NOC?
- What Documents Are Required for Each NOC?
- How Do You Apply for a Bank NOC and a Developer NOC?
- How Much Do Bank NOCs and Developer NOCs Cost?
- How Long Do the NOC Processes Take?
- How Can Arnifi Help?
- FAQs
- Conclusion
- Official references
Key Fact: A Developer NOC may be required for an eligible property sale or transfer, while bank clearance or a mortgage release letter may be necessary when a property is financed. Requirements depend on the property’s registration status, mortgage arrangements and transaction type.
Table of contents
- What Is a Bank NOC in Dubai?
- What Is a Developer NOC in Dubai?
- Bank NOC vs Developer NOC | What Are the Main Differences?
- When Do You Need a Bank NOC or a Developer NOC?
- What Documents Are Required for Each NOC?
- How Do You Apply for a Bank NOC and a Developer NOC?
- How Much Do Bank NOCs and Developer NOCs Cost?
- How Long Do the NOC Processes Take?
- How Can Arnifi Help?
- FAQs
- Conclusion
- Official references
What Is a Bank NOC in Dubai?
A Bank No Objection Certificate (NOC) is a document issued by a bank or mortgage lender to confirm its consent or clearance for a specific property transaction. The exact document required depends on the property’s financing status and the transaction being carried out.
For a mortgaged property, the lender may need to confirm the outstanding liability, approve a mortgage transfer or provide documentation for releasing the registered mortgage. A mortgage release letter is particularly important when the existing mortgage must be removed as part of a sale.
Common situations include:
- Selling a property with an outstanding mortgage
- Transferring a mortgage from one bank to another
- Releasing a mortgage after the loan has been settled
- Completing a transaction that requires the lender’s consent
A Bank NOC does not replace the property registration process. The applicable mortgage release, sale or transfer must still be completed through the relevant Dubai Land Department (DLD) procedure.
What Is a Developer NOC in Dubai?
A Developer NOC is issued by the property developer to confirm that the applicable developer-side requirements for a transaction have been satisfied. It may be required when selling or transferring a property, including certain resales of off-plan units before final registration.
The developer may check property records, outstanding service charges, contractual obligations and other requirements connected with the unit. The exact checks depend on the developer, project and transaction.
A Developer NOC may be relevant when:
- Selling a completed property in a development where the NOC is required
- Reselling an off-plan property before final registration
- Transferring rights under a provisional sale agreement
- Completing a property transaction that requires developer clearance
A Developer NOC is not a title deed or proof of ownership. It addresses the developer’s requirements, while the official ownership record is handled through the applicable registration process.
Bank NOC vs Developer NOC | What Are the Main Differences?
The main difference is who issues the document and what it clears. A bank deals with financing and mortgage-related requirements, while a developer deals with requirements connected to the property and its development.
| Comparison point | Bank NOC | Developer NOC |
| Issuing party | Bank or mortgage lender | Property developer |
| Main purpose | Confirms relevant lender consent or clearance | Confirms applicable developer requirements have been met |
| Common situation | Mortgage release, transfer or mortgaged property sale | Property sale, transfer or eligible off-plan resale |
| Main checks | Loan status, outstanding liability and mortgage requirements | Property records, contractual obligations and applicable dues |
| Documents | Loan details, identification and transaction documents as required | Ownership or sale records, identification and developer-specific documents |
| Fees | Depend on the lender and transaction | Depend on the developer and transaction |
| Role in transfer | Addresses lender-related requirements | Addresses developer-related requirements |
Neither document automatically replaces the other. If a transaction requires both lender clearance and developer approval, obtaining one does not remove the need to obtain the other.
When Do You Need a Bank NOC or a Developer NOC?
The documents required for a property transaction depend on whether the property is mortgaged, fully registered or still under an off-plan arrangement.
| Property transaction | Documents or clearance to check |
| Selling a mortgaged property | Bank liability details and mortgage release documentation, plus Developer NOC if required |
| Selling a property without an outstanding mortgage | Developer NOC where required, along with the applicable transfer documents |
| Reselling an off-plan property | Developer NOC and relevant provisional sale registration documents, as applicable |
| Transferring a mortgage to another bank | Previous lender’s NOC and the new lender’s mortgage documents, with developer e-NOC where applicable |
| Completing an ownership transfer | Applicable DLD requirements, including developer clearance where required |
For example, a seller with an outstanding home loan may need to settle the lender’s liability and obtain a mortgage release letter before the transfer can be completed. A separate Developer NOC may also be needed for the property transaction.
The DLD has specific procedures for mortgaged property sales, mortgage releases and mortgage transfers. Confirm the requirements for your particular transaction rather than assuming that every sale follows the same process.
What Documents Are Required for Each NOC?
Document checklists vary by lender, developer and transaction type. Prepare the core property and identification records first, then request the exact checklist from each issuing entity.
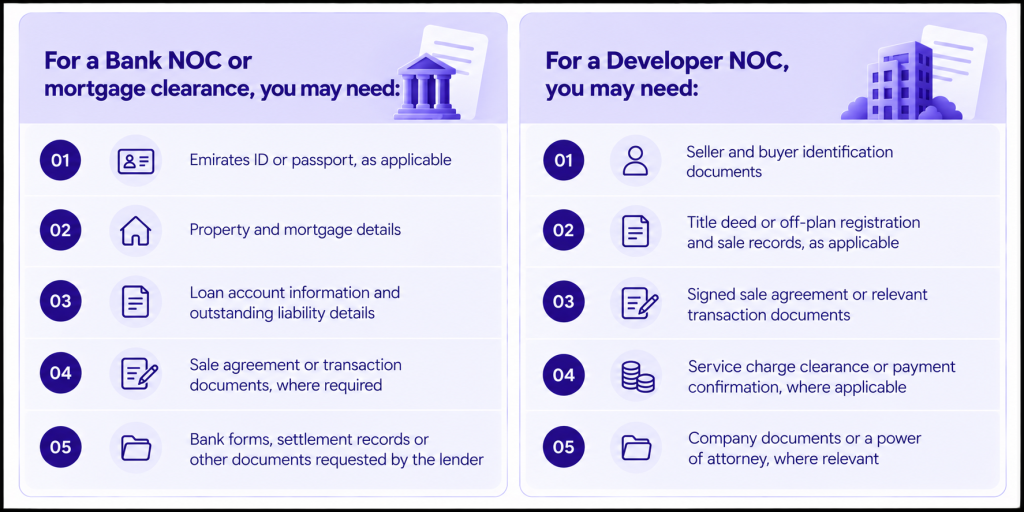
Do not rely on a generic checklist alone. The issuing bank or developer should confirm which documents are required for the property’s current status and the intended transaction.
How Do You Apply for a Bank NOC and a Developer NOC?
The applications are usually handled separately because the bank and developer perform different checks.
Bank NOC process
- Contact the lender and confirm whether you need a Bank NOC, liability letter or mortgage release document
- Submit the requested property, loan and transaction details
- Settle outstanding liabilities or meet the lender’s conditions, where applicable
- Complete the bank’s verification process and obtain the required documentation
Developer NOC process
- Contact the developer or use its designated customer service channel
- Submit the ownership, buyer, seller and transaction documents requested
- Clear applicable service charges or other outstanding amounts
- Complete the developer’s checks and obtain the NOC
For some completed properties, management company or service charge clearance may also be relevant. Once the necessary documents are available, the parties must follow the applicable DLD registration procedure to complete the sale or transfer.
How Much Do Bank NOCs and Developer NOCs Cost?
There is no single fee that applies to every Bank NOC or Developer NOC in Dubai. Charges depend on the issuing entity, property and transaction.
| Cost factor | What to confirm |
| Bank charges | Administrative fees and any charges linked to mortgage release or transfer |
| Mortgage settlement | Outstanding loan balance and any applicable settlement conditions |
| Developer charges | Current NOC fee and any outstanding service charges |
| Registration costs | Applicable DLD, trustee and other transaction fees |
NOC charges are separate from DLD registration fees, trustee fees and any outstanding mortgage balance. Request current, itemised fee details from the relevant bank and developer before budgeting for the transaction.
How Long Do the NOC Processes Take?
Processing times vary according to the issuing entity, the completeness of the application and the complexity of the transaction. A straightforward request may progress quickly, while mortgage settlement or unresolved property records can take longer.
Common causes of delay include:
- Missing identification or transaction documents
- Outstanding service charges or other dues
- Unsettled loan liabilities or mortgage release requirements
- Differences between property records and submitted documents
- Additional checks required by the bank or developer
Apply early and coordinate with the bank, developer and other transaction parties to reduce the risk of last-minute delays. Confirm the expected timeline directly with each issuing entity.
How Can Arnifi Help?
Arnifi supports businesses with company formation and corporate administrative requirements. Where relevant to a client’s requirements, its team can help clarify documentation needs and identify which administrative steps may need attention.
For property transactions, the issuing bank, developer and relevant property authorities remain responsible for their respective clearances, approvals and decisions. Mortgage advice, legal interpretation and representation should be handled by appropriately qualified professionals where required.
Contact Arnifi to discuss your UAE business setup and corporate service requirements and identify the support appropriate to your situation.
FAQs
1. Is a Bank NOC the Same as a Developer NOC?
No. A Bank NOC addresses lender-related consent or clearance, while a Developer NOC addresses the developer’s requirements for a property transaction. They serve different purposes.
2. Do I Need Both a Bank NOC and a Developer NOC to Sell a Property in Dubai?
You may need both if the property is mortgaged and the transaction also requires developer clearance. The exact requirements depend on the property status and the applicable DLD procedure.
3. Can I Sell a Property Without a Bank NOC?
If no mortgage or lender consent requirement applies, a Bank NOC may not be necessary. If a mortgage remains registered, the lender’s liability and mortgage release requirements must be addressed as part of the relevant process.
4. Who Pays for the Developer NOC?
The payment responsibility depends on the transaction arrangements and the developer’s requirements. Confirm the current fee and agree who will pay it before proceeding.
5. What Happens If an NOC Application Is Delayed?
Contact the issuing bank or developer to identify missing documents, outstanding payments or unresolved requirements. If the transaction involves a mortgage, coordinate with the lender and the other parties to understand how the delay affects the transfer.
Conclusion
Understanding Bank NOC vs Developer NOC in Dubai helps property owners prepare for the correct clearance process before a sale or transfer. Bank documentation addresses financing and mortgage requirements, while a Developer NOC covers applicable developer-side conditions. Confirm the documents, fees and timelines with the relevant entities before arranging the transfer.
For support with your UAE company setup and corporate administrative requirements, contact Arnifi to discuss the services available for your needs.
Official references
Top UAE Packages
Related Articles
Top UAE Packages
Get in Touch
