
Complete Guide to VAT Exemption in the UAE: 2026 Rules
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: The VAT exemption in the UAE enables businesses to be exempted from charging 5% VAT on certain supplies; however, the inability to recover the input VAT will increase the costs of operations by 5-10%. Hence, the accurate apportionment of input VAT and compliance will become essential with the introduction of FTA amendments in 2026.
Table of contents
- Introduction
- Understanding VAT Exemption in the UAE
- Eligible Sectors for VAT Exemption
- VAT Treatment of Cross-Border Services
- New 2026 Input-Tax Apportionment Rules
- UAE National Housing Refund Scheme and VAT Treatment
- How to Avoid VAT Fines and Penalties?
- The Process of Qualifying for VAT Exemption
- VAT Compliance for Exempt Businesses
- Frequently Asked Questions (FAQ)
- Conclusion
- References
Introduction
Comprehending the VAT exemption in the UAE goes way beyond identifying the list of goods and/or services that do not bear the regular 5% tax. As for standard supplies, VAT should be collected, whereas for zero-rated supplies, there will be a possibility of recovering the input VAT on the entire operation costs. Exempt supplies stand out as the third category of goods/services that have their own distinctive features.
Most of the current guides concentrate only on presenting the list of the exempt supplies, which include such areas as financial services, residential real estate, education, and healthcare. In order to deal with VAT exemption in the UAE, a more detailed overview of the input-tax recovery process, mixed supply apportionment, and the impact of Cabinet Decision No. 149 of 2026 will become relevant.
Understanding VAT Exemption in the UAE
Meaning of VAT Exemption
As per UAE VAT laws (Federal Decree-Law No. 8 of 2017), VAT exemptions in the UAE include specific non-taxable supplies intended to ease the financial burden for basic consumer sectors. In contrast to taxable supplies, exempt supplies are not subject to the normal 5% VAT rate; hence, no VAT is charged.
Registration Thresholds & Compliance Reality
- Standard VAT Rate: 5% across standard-rated goods and services.
- Mandatory Registration Threshold: AED 367,000 in annual taxable turnover/supplies.
- Voluntary Registration Threshold: AED 187,500 in annual taxable turnover or expenses.
Important: Note that being exempted from VAT in the UAE doesn’t mean complete freedom from the process of VAT compliance. Businesses that supply goods or services that qualify for VAT exemption still need to file their returns periodically, keep their books of account audited, and be audited by the FTA.
VAT Exemption vs. Zero-Rated vs. Standard-Rated Supplies
| Feature | Standard-Rated Supplies | Zero-Rated Supplies | Exempt Supplies |
| VAT Rate Charged | 5% | 0% | No VAT charged |
| Input VAT Recovery | Fully recoverable (subject to normal rules) | Fully recoverable (subject to normal rules) | Generally unrecoverable |
| Impact on Costs | Neutral (tax passed to consumer) | Favorable (cash flow refund) | Increases expenses by 5–10% |
| VAT Return Treatment | Reported as taxable supply with 5% VAT | Reported as zero-rated supply | Reported as exempt supply in Box 10 |
Eligible Sectors for VAT Exemption
1. Financial Services
- Exempt: Financial services where the payment is done through spread or margin (no fee or commission is being paid explicitly), the issuance and/or transfer of debt/equity securities, life insurance, and reinsurance.
- Standard 5%: Financial services where payment is made explicitly as a fee, commission, commercial discount, or rebate.
2. Real Estate
- Zero-Rated: The first supply (whether sale or rental) of residential property within 3 years from the completion of construction.
- Exempt: All other sales and rentals of residential properties after the said three-year period, and all bare lands.
- Standard 5%: Commercial real estate transactions (sales or leases) remain standard-rated.
3. Education
Education and specified educational services (and goods and services of similar nature provided by registered institutions) enjoy special VAT treatment to maintain lower cost of education. Nevertheless, support services, such as school uniforms, catering, etc., can be standard-rated.
4. Healthcare
Healthcare and medical services offered by registered healthcare institutions or providers qualify for exemption or zero-rating depending on strict criteria set by the FTA. Cosmetology is standard-rated at 5%.
5. Other Exempt Categories
There are certain international financial products, local transportation services for passengers, and certain public services that fall under exempt categories based on strict administrative criteria. There are no entire corporate sectors exempt from taxation.
VAT Treatment of Cross-Border Services
Businesses offering their services internationally will need to tell apart zero-rating and VAT exemption in the UAE:
- Services to Recipients Outside the GCC: The exported services can be exempted and zero-rated; the latter is preferable since the UAE business will get back its input VAT.
- Intra-GCC Transactions: In case of the supply of goods and services to the VAT-registered companies in other implementing GCC countries, the RCM will apply.
- Strategic Impact: Considering a cross-border supply to be exempted instead of zero-rated means that the company cannot get its input VAT back.
New 2026 Input-Tax Apportionment Rules
What Changed in 2026? (Cabinet Decision No. 149)
Cabinet Decision No. 149 published in 2026 contains major amendments to the rules on apportionment of input tax. The changes affect taxpayers engaged in making both taxable (standard/zero-rated) and exempt supplies.
Input VAT incurred in relation to mixed supplies shall be categorized into three groups:
- Direct Taxable Input VAT: 100% recoverable for expenses directly linked to standard or zero-rated supplies.
- Direct Exempt Input VAT: 0% recoverable (fully blocked) for expenses directly tied to exempt supplies.
- Residual Overhead Input VAT: Shared costs (like rent or utilities) that must be allocated using the updated statutory apportionment formula.
Residual Input-Tax Method
In relation to common costs (e.g., company rent, utility charges, ICT network), there can be no direct allocation of input VAT to one particular class of supplies.
- Updated Methodology: Businesses will have to compute their residual input VAT recoverable by taking into account the ratio of taxable income to total income during the tax period.
- Effective Date: Mandatory for tax periods commencing after 1 October 2027, although early implementation and reviews should be considered from 2026.
Cash-Payment Recovery Limits
In order to address untraceable transactions, stricter administrative limitations apply to input VAT recovery in cases of expenses paid through cash payments. Payments above certain limits not supported by complete documentation regarding banking records are automatically ineligible for input VAT refund.
Employee-Related Expenses
There are limitations on input VAT recovery of discretionary employee benefits, entertainment services, and personal goods. Input VAT is barred except in case of an obligation or term set out under statute or contract that is business necessary.
UAE National Housing Refund Scheme and VAT Treatment
What is the Scheme?
The United Arab Emirates’ National Housing Refund Scheme enables UAE residents to reclaim input VAT incurred from construction of residential property for personal use.
Interaction with Residential Property VAT Rules
| Property Context | Tax Classification | VAT Treatment | Input VAT Impact |
| Commercial Developer (First Sale <3 years) | Zero-Rated | Charged at 0% | Full input VAT recovery by developer |
| Commercial Developer (Subsequent Sale/Lease) | Exempt | No VAT charged | Input VAT is non-recoverable |
| Individual UAE Citizen (Personal Home) | Standard (5% paid to builder) | Refundable via VATGRH1 | Recovered via special FTA refund scheme |
Key Takeaway: An exempt enterprise providing leasing services for residential accommodation functions within the exempt VAT regime; therefore, it is unable to claim any general VAT refund. Meanwhile, individual residents who construct a personal house utilize the VATGRH1 Housing Refund Process independently.
How to Avoid VAT Fines and Penalties?
FTA conducts thorough audits of exempt enterprises as well. Typical mistakes that lead to audits are related to misclassification of supplies, incorrect claiming of input taxes, lack of VAT invoices, and so forth.
Penalties for Non-Compliance
| Non-Compliance Type | First Offense | Repeat Offense |
| Failure to maintain proper records | AED 10,000 | AED 50,000 |
| Late submission of VAT returns | AED 1,000 | AED 2,000 (within 24 months) |
| Incorrect tax return filings | AED 1,000 fixed fee | Percentage penalty up to 50% of unpaid tax |
| Failure to issue tax invoices/credit notes | AED 2,500 per document | AED 2,500 per document |
The Process of Qualifying for VAT Exemption
The official process of obtaining a VAT exemption certificate in the UAE involves verification of the activity classifications through the FTA portal. Below is the workflow:
- Review Activity Classification: Identify whether your particular supplies are exempt, zero-rated, or standard-rated under Federal Decree-Law No. 8 of 2017.
- Review FTA Guidelines: Verify whether there are any sector-specific guidelines provided by the Federal Tax Authority.
- Gather Required Documentation:
- Valid Trade License
- Authorised Signatory Passport/Emirates ID
- Bank Verification Letter & Financial Statements
- Sector-specific operating licenses (e.g., Central Bank, DHA/MOHAP, ADEK/KHDA)
- Submit via FTA Portal: Go to your FTA portal account and submit the relevant documentation.
- FTA Audit Review: The FTA will go through your documentation and may raise RFIs for clarifications.
- Application Outcome: Approval, classification change, or confirmation of VAT exemption status.
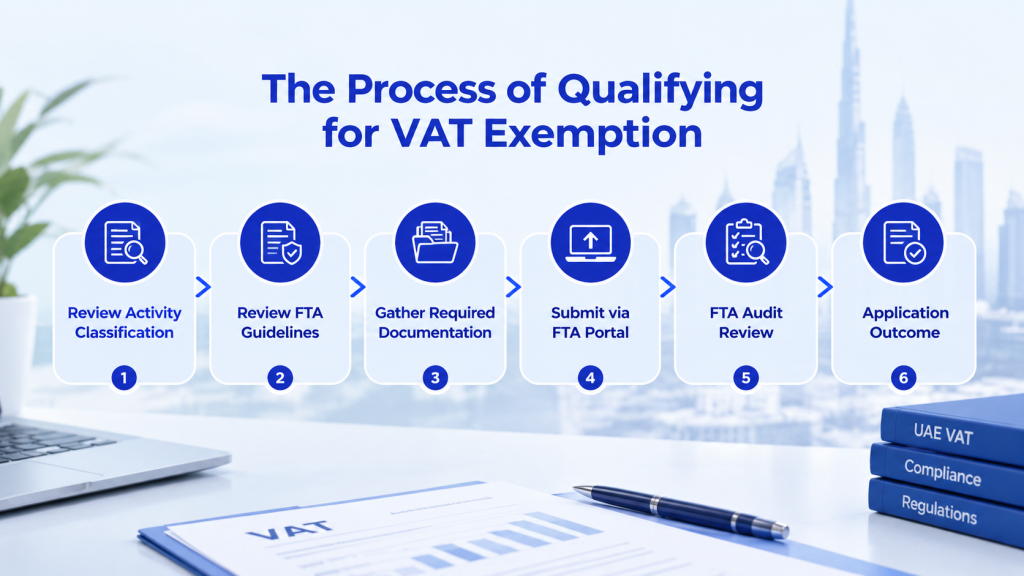
Processing Timeline: Standard time frame of 25 working days starting from the receipt of full documentation.
VAT Compliance for Exempt Businesses
Do Exempt Businesses Need to File VAT Returns?
Yes. If your business meets the mandatory registration threshold, you must file periodic VAT returns. Exempt sales must be reported under Box 10 of the UAE VAT return form.
Filing Frequencies
- Annual revenues AED 150 Million: Monthly return filings.
- Annual revenues < AED 150 Million: Quarterly return filings.
Comprehensive Compliance Checklist
- Validate the exact nature of your supplies (Exempt, Zero-Rated, or Standard).
- Ensure you meet the VAT registration threshold (AED 367,000).
- Keep audited accounting records, sales register, and purchase register for 5 years or more.
- Create an invoice without collecting VAT on Exempt supplies (and use mandatory TRN).
- Implement 2026 regulations concerning cash payment restrictions and non-deductible staff expenses.
- Submit your VAT returns monthly/quarterly before the prescribed deadline (28th day after the tax period).
Frequently Asked Questions (FAQ)
What is VAT exemption in the UAE?
In the UAE, VAT Exemption means that there is no charge of 5% VAT on the sale of some particular goods and services (for example, margin-based financial services and residential property rentals after three years). But the company will not be able to claim back any input VAT paid on any related expense.
What is the VAT exemption threshold in the UAE?
This is similar to the VAT registration threshold of AED 367,000 in taxable supplies and expenses.
What is a VAT exemption certificate in the UAE?
VAT Exemption Certificate in the UAE refers to the official administrative document issued by the Federal Tax Authority (FTA) confirming that your company is eligible for exemptions as per UAE tax laws.
Which services are exempt from VAT in the UAE?
Some common examples of exempt services are margin-based financial services, life insurance, subsequent sale/leasing of residential property, bare land, and passenger transportation.
What is the difference between VAT exempt and zero-rated in the UAE?
Zero-rated supplies attract VAT at 0%, and businesses may claim back the input VAT incurred. For exempt supplies, VAT is not charged, and businesses cannot claim back the input VAT.
Can exempt businesses recover input VAT?
No. Input VAT charged on expenses that are attributable to exempt supplies is non-recoverable and will increase the operational costs by about 5% – 10%.
Are financial services exempt from VAT in the UAE?
Financial services where the remuneration is derived through implicit margins or spreads are VAT exempt. Where there is an explicit charge for the financial service in question, VAT is charged at 5%.
Is residential property exempt from VAT in the UAE?
The first supply of the residential property within three years of the completion of construction is zero-rated. The subsequent supplies are exempt.
Is the first sale of a residential property zero-rated in the UAE?
Yes, provided that it is sold or leased within 3 years of the completion date of the construction.
How does VAT apply to mixed taxable and exempt supplies?
Those supplying mixed supplies shall employ input tax apportionment rules to claim VAT for taxable supplies while barring input VAT related to exempt supplies.
What changed under Cabinet Decision No. 149 of 2026?
This decision introduced residual input tax apportionment, limited input tax recovery in cash sales, and toughened input tax recovery criteria for employee expenditures.
When do the new UAE input-tax apportionment rules take effect?
These rules apply for the tax years commencing after 1 October 2027; meanwhile, businesses need to examine their policies during 2026.
What is the National Housing Refund Scheme?
It is the FTA scheme that allows UAE nationals to reclaim input VAT incurred while constructing their houses.
What is VATGRH1?
It is the FTA official application form used by UAE citizens to make a VAT refund request.
Do VAT-exempt businesses need to file VAT returns?
Yes. Registered businesses must report their exempt sales under Box 10 of their regular VAT return.
How long does an FTA VAT application take?
Standard processing takes a minimum of 25 working days after submitting complete documentation.
What records must VAT-exempt businesses maintain?
Businesses must maintain tax invoices, credit notes, financial ledgers, bank statements, and input VAT logs for at least 5 years.
How can businesses avoid VAT penalties in the UAE?
By accurately classifying supplies, maintaining complete documentation, filing returns on time, and properly calculating input-tax apportionment ratios.
Conclusion
Comprehending VAT exemption in the UAE does not only require knowing the sources of income that are not taxable but also actively managing input VAT refunds, making mixed supply assessments, and maintaining proper FTA records. The changes made to the UAE VAT system from 2026, in accordance with Cabinet Decision No. 149, put more stress on residual input-tax allocation, proper documentation for cash transactions, and keeping track of expenses of employees.
With the help of proper accounting methods, VAT audits, and FTA guidelines, businesses can achieve compliance.
References
- Federal Tax Authority (FTA) Official Portal: https://tax.gov.ae/
- UAE Cabinet Decision & Legislation Center: https://uaelegislation.gov.ae/
- Ministry of Finance (MoF) – UAE Tax Framework: https://mof.gov.ae/
Top UAE Packages
Related Articles
Top UAE Packages
Get in Touch
