
India-Mauritius Tax Treaty Explained | A New Chapter for Foreign Investors
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: The Delhi High Court held that capital gains arising from sales of units in Indian equity mutual funds were exempt from tax in India under the India-Mauritius tax treaty, thereby safeguarding ₹593.48 crore worth of gains for Mauritius residents.
Table of contents
- Introduction
- Understanding the Delhi High Court’s Mauritius Treaty Ruling
- Mutual Fund Units vs. Company Shares: The Key Tax Distinction
- What the Ruling Means for Foreign Investors and Fund Managers
- Why Mauritius Remains Relevant for Cross-Border Fund Structuring
- Structuring and Compliance Considerations for Mauritius-Based Funds
- Conclusion
- Frequently Asked Questions (FAQs)
- References
Introduction
India-Mauritius tax treaty is a bilateral treaty that serves to eliminate double taxation and lays down capital gains provisions for international investments. International capital investment forms an integral part of generating liquidity and growth in India’s fast-growing financial sector. Recently, a key judgment has been delivered by the Delhi High Court regarding the capital gains accruing to Mauritius residents through investments in Indian mutual fund units. This landmark decision helps define the interpretation of the India-Mauritius DTAA.
Understanding the Delhi High Court’s Mauritius Treaty Ruling
One of the most important tax cases was based on testing the legal limits of the India-Mauritius tax treaty.
The Dispute and Judicial Outcome
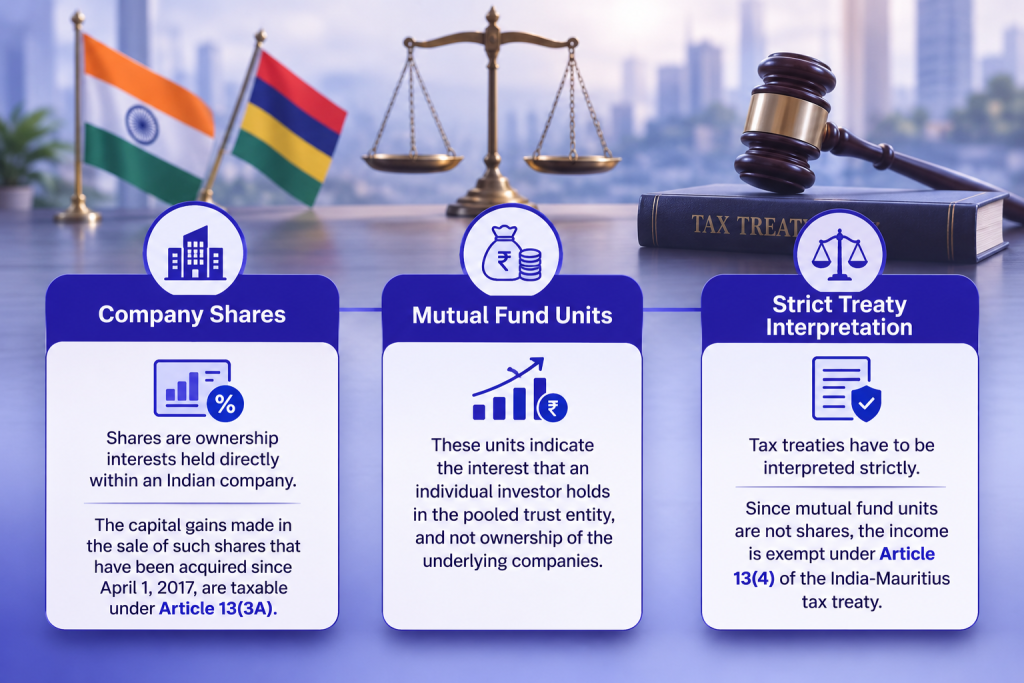
Emerging India Focus Funds realised ₹593.48 crore capital gain from the sale of Indian equity-oriented mutual fund units in AY 2022–23. The tax department of India wanted to impose taxes on 65% of the gains, amounting to ₹385.76 crore. In June 2025, the ITAT gave a decision in favour of the foreign investor. The Delhi High Court confirmed this judgment as well. The courts relied entirely on the actual wording of Article 13(3A) of the India-Mauritius tax treaty and did not want to stretch this share taxation provision to mutual fund units.
Mutual Fund Units vs. Company Shares: The Key Tax Distinction
The Delhi High Court made a legal distinction between direct shares of an equity and pooled mutual fund units.
Legal Differences Under the Treaty
What the Ruling Means for Foreign Investors and Fund Managers
This clarity of law affects cross-border investment strategies in view of the India-Mauritius tax treaty.
Three Major Market Implications
- Greater Tax Certainty: Now there is clarity as far as tax treatment is concerned, with respect to the redemption of Indian equity-oriented mutual fund units by qualifying Mauritius funds.
- Stronger Investor Confidence: Clarity of judicial precedents avoids the possibility of litigation and unexpected tax assessment by Indian authorities.
- Increased Capital Flows: International fund managers can invest capital in Indian mutual funds with more certainty.
However, this decision is limited to the facts of the case and the provisions of the relevant treaty. It is not a general tax exemption applicable to every type of Mauritius investment structure.
Why Mauritius Remains Relevant for Cross-Border Fund Structuring
Mauritius remains a preferred jurisdiction for attracting international capital into India.
Strategic Advantages of the Jurisdiction
Mauritius offers a developed regulatory framework, experienced financial professionals, and a large network of DTAs. From 2000 to 2025, Mauritius represented about 24% of India’s cumulative foreign direct investment inflows. Even though fund managers consider Singapore, the Cayman Islands, and BVI, Mauritius still competes strongly in India-oriented strategies. Learn more about Mauritius company formation via Arnifi.
Structuring and Compliance Considerations for Mauritius-Based Funds
Fund managers should align suitable provisions in the India-Mauritius tax treaty with high levels of operational compliance.
Key Operational Requirements
- Fund Incorporation: Choose a suitable corporate or trust vehicle based on your investor demographic and investment strategy.
- Regulatory Compliance: Ensure that you have obtained proper authorization from the Financial Services Commission (FSC) of Mauritius.
- Tax Documentation: Ensure that you have a valid Tax Residency Certificate (TRC), proper transaction documentation, and governance documentation.
- Ongoing Obligations: Meet statutory requirements, local accounting standards, and economic substance requirements.
Work with Arnifi for smooth international fund establishment and comprehensive compliance management.
Conclusion
The case of the Delhi High Court enhances certainty regarding the India-Mauritius tax treaty. By distinguishing mutual fund units from company shares, the court enhanced the confidence of foreign investors in cross-border financial transactions. However, foreign investors should ensure that they back treaty provisions with suitable entity formation and governance. Establish your cross-border business now with Arnifi or schedule a consultation with Arnifi’s global expansion consultants to create an international fund.
Frequently Asked Questions (FAQs)
1. What is the India-Mauritius tax treaty?
DTAA between India and Mauritius is a bilateral treaty signed in 1982, which avoids double taxation and regulates the taxing rights of capital gains.
2. What did the Delhi High Court decide regarding mutual fund units?
The court held that capital gains on the sale of Indian equity mutual fund units will not be taxable in India as per Article 13(4).
3. How much tax was disputed in the Emerging India Focus Funds case?
Indian Tax department sought to tax Rs.385.76 crore in capital gains out of total capital gains of Rs.593.48 crore.
4. Why are mutual fund units taxed differently from company shares?
The Mutual Fund unit represents the interest of a trustee, whereas a company share represents the equity of the shareholder.
5. Does Article 13(3A) of the treaty apply to mutual fund units?
No. Article 13(3A) applies only to the transfers of shares of companies obtained on or after April 1, 2017.
6. Does this ruling exempt all Mauritius investments from Indian tax?
No. This decision applies only to gains from eligible mutual fund units and requires valid tax residency and commercial substance.
7. Which regulator oversees investment funds in Mauritius?
In Mauritius, investment funds are regulated by the Financial Services Commission (FSC).
8. What documents prove tax residency for Mauritius funds?
Funds need to have a Tax Residency Certificate (TRC) along with other documents that confirm management, control, and substance.
References
- Income Tax Department, Government of India: incometaxindia.gov.in
- Securities and Exchange Board of India (SEBI): sebi.gov.in
- Financial Services Commission (FSC) Mauritius: fscmauritius.org
- High Court of Delhi Official Portal: delhihighcourt.nic.in
Top UAE Packages
Related Articles
Top UAE Packages
Planning Your Next Business Move?
