
Employee Benefit Trust (EBT) UK: Comprehensive Guide to Structure, and Tax
Zahira Shaik
SEO Content Writer
Zahira Shaik is an SEO Content Writer and Published Author specializing in research-based content. She excels at analyzing market trends, regulations, and industry developments… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact
The Employee Benefit Trust (EBT) refers to a discretionary trust created by the employer to place assets, including shares and cash of the company, in a trust for employees, directors and their dependants for the purposes of providing incentive schemes and succession planning.
Table of contents
- Introduction
- What is an Employee Benefit Trust?
- How Does an Employee Benefit Trust Work?
- Why Do Companies Set Up an Employee Benefit Trust?
- Who Can Benefit From an Employee Benefit Trust?
- Employee Benefit Trusts in Cross-Border and Hybrid Ownership Structures
- How Do EBTs Interact With Local End-of-Service Schemes?
- What Are the Tax Implications of an Employee Benefit Trust?
- When Should a Business Consider Setting Up an EBT?
- How to Structure an Employee Benefit Trust
- Tech-Enabled EBT Setup and Ongoing Compliance
- What Are the Key Governance Considerations for an EBT?
- How Can Arnifi Help Businesses Establish an Employee Benefit Trust?
- Frequently Asked Questions
- Conclusion
Introduction
EBTs have become common vehicles used by many organizations to manage their share ownership, incentive schemes and succession planning. Nevertheless, forming an EBT requires much more than just placing the assets (such as shares or funds) in a trust. There is a lot that needs to be considered when drafting the trust deed, ensuring independence of the trustees, defining beneficiaries, taking into account taxation, and having the international workforce in mind.
What is an Employee Benefit Trust?
Employee Benefit Trust (EBT) refers to a discretionary trust that is set up by the employer for the benefit of present or past employees, directors, or the dependent relatives of such people.
- Discretionary Trust Structure: In a discretionary trust model, the trustees have legal ownership of the assets, and they use their discretion in making distributions based on the trust deed.
- Employer-Established Trust: The employer establishes this type of trust and funds it initially with some assets, though he does not manage the trust assets afterwards.
- Assets Held in Trust: EBTs generally consist of company stocks, money, or other types of financial assets that may be used for incentivizing employees.
- Role of the Trust Deed: The trust deed serves as the governing legal document, outlining trustee powers, eligible beneficiary classes, and rules for asset distribution.
How Does an Employee Benefit Trust Work?
An EBT operates through a five-step lifecycle:
Step 1: Trust Establishment
The trust is established by having the employer execute the trust deed. In this legal document, the purposes of the trust, powers of the trustees, and eligibility criteria to become a beneficiary will be stated.
Step 2: Trustee Appointment
Trustees independent of the employer will be appointed to manage the trust. Trustees have to fulfill their fiduciary duty, which requires them to act in good faith in handling the assets of the beneficiaries.
Step 3: Asset Funding
Cash, shares, and other allowed forms of assets will be transferred to the trust by the company. If funding with company shares, the EBT can acquire existing shares or subscribe to new shares issued by the company.
Step 4: Asset Management
The trustees will independently manage the trust assets. The company can give advice or recommendations regarding how to use the assets; however, the final decision is only up to the trustees based on the trust deed.
Step 5: Distribution
Distribution of shares, bonuses, or other benefits to the beneficiaries will be made on the basis of certain milestones achieved or predetermined criteria in the trust deed.
Why Do Companies Set Up an Employee Benefit Trust?
EBTs are formed by companies to meet their business objectives:
- Employee Retention and Motivation: The LTIPs formed with EBTs help in motivating and retaining the best talent in the organization.
- Employee Share Ownership: EBTs can be used as the most flexible tool for holding company shares and facilitating schemes of employee shareholding and share liquidity.
- Long-Term Incentive Plans: It helps in forming performance-based reward schemes and deferred payment schemes.
- Succession Planning: EBTs help privately-owned companies to carry out succession planning by transferring ownership to the management or employees of the company.
- Flexible Reward Structures: EBTs offer centralized management of reward schemes for employees.
Who Can Benefit From an Employee Benefit Trust?
Eligibility will depend on the particular terms contained within the trust deed:
- Current Employees: The main beneficiary group, involved in performance or share schemes.
- Former Employees: These individuals can still be eligible for deferred benefits or incentive payments after retirement from the organization.
- Directors and Company Officers: These groups can be considered as beneficiaries, where allowed by the trust deed and company laws of the local jurisdiction.
- Dependants of Employees: Spouses, children, or other financially dependent family members can also qualify as beneficiaries depending on certain terms within the trust deed.
Employee Benefit Trusts in Cross-Border and Hybrid Ownership Structures
Where the company is multinational or works with remote employees, the EBT structure needs to be able to cater to more than one jurisdiction:
- Multi-Jurisdictional Beneficiaries: Employees or directors who live in other countries would be taxed differently after getting the money from the trust.
- Cross-Border Share Holdings: The issuance and possession of the shares of the company need to comply with international securities and currency laws and the laws regarding trusts in their respective locations.
- Governance & Regulatory Alignment: The trustees shall see to it that the trust deed takes into account the regulations of other countries but retains an independent form of governance regardless of the operating territories of the entity.
How Do EBTs Interact With Local End-of-Service Schemes?
An Employment Benefit Trust is a system that is voluntary and exists separately from any statutory or mandatory employment benefits:
- Separation from Statutory Benefits: EBT incentive payments cannot automatically replace the statutory severance, pensions, and mandatory end-of-service payments.
- Specific Overseas Schemes (e.g., DIFC DEWS): In areas where there is a mandatory system of workplace savings, like the Dubai International Financial Centre Employee Workplace Savings (DEWS), the benefits in the EBT system should work alongside the mandatory system.
- Avoiding Conflicts: There must be clear contractual drafting to separate EBT payments from statutory end-of-service payments.
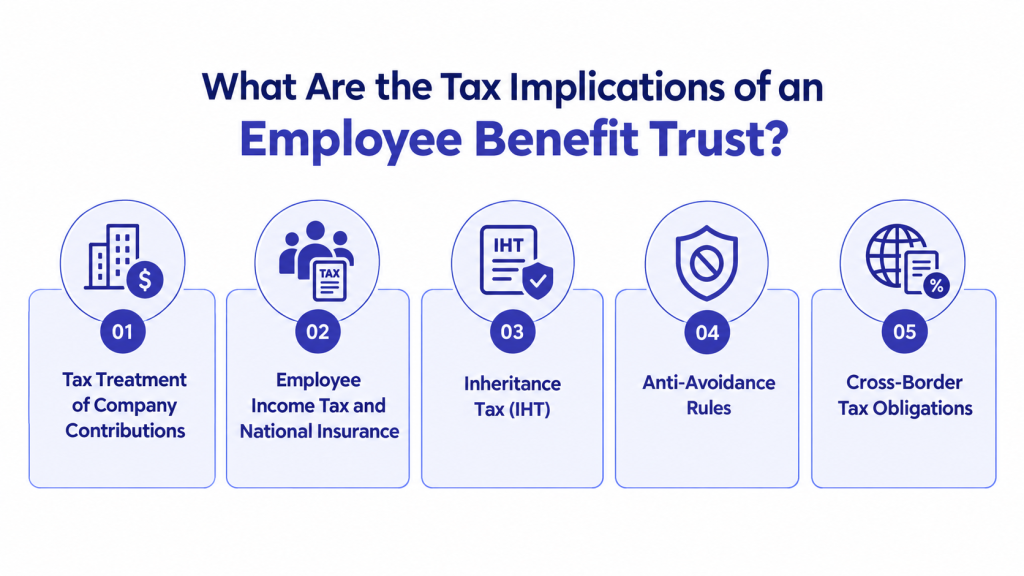
What Are the Tax Implications of an Employee Benefit Trust?
Taxation is determined by the trust structure, transaction type, and statutory requirements in the applicable jurisdiction:
- Tax Treatment of Company Contributions: While corporate tax relief can be obtained for the employer’s contributions to the EBT, such relief would not apply unless the benefits have been paid out to the beneficiaries or the statutory requirements are met in the jurisdiction of the UK.
- Employee Income Tax and National Insurance: Payments to the beneficiaries from the EBT, including cash payments and payments of shares or benefits, are normally taxed under Income Tax and National Insurance Contributions (NICs) through PAYE.
- Inheritance Tax (IHT): Employee trusts qualifying for statutory requirements (such as Section 86 of the Inheritance Tax Act 1984 in the UK) can obtain relief from IHT charges.
- Anti-Avoidance Rules: Special rules have been implemented to prevent EBTs from being used as disguised remuneration schemes, where unapproved loan schemes and tax avoidance are penalized severely.
- Cross-Border Tax Obligations: Withholding tax liabilities arise if the beneficiary of the trust scheme is resident in another country.
When Should a Business Consider Setting Up an EBT?
An EBT is worth considering when a company aims to:
- Implement Employee Share Ownership: Establish a formal pool of shares.
- Retain Key Talent: Provide long-term incentives to key management personnel and essential employees.
- Facilitate Business Succession: Plan an efficient transfer of ownership to management or employees.
- Manage International Workforces: Centralize employee incentive administration across multiple countries.
How to Structure an Employee Benefit Trust
| Stage | Action Item | Key Focus |
| Step 1 | Define Business Objective | Identify whether the primary goal is retention, share ownership, or succession. |
| Step 2 | Determine Beneficiary Class | Explicitly define eligibility for employees, officers, and dependants. |
| Step 3 | Draft the Trust Deed | Establish trustee powers, distribution rules, and governing laws. |
| Step 4 | Appoint Independent Trustees | Ensure trustee independence and clear corporate governance. |
| Step 5 | Fund the Trust | Transfer cash, shares, or permitted assets into the trust account. |
| Step 6 | Establish Ongoing Governance | Set up records, AML/KYC checks, compliance tracking, and tax reporting. |
Tech-Enabled EBT Setup and Ongoing Compliance
Managing an EBT across time and multiple regions requires streamlined compliance tools:
- Digital Organograms: Helping map the ownership hierarchy and beneficiaries.
- Automated AML & Identity Checks: Making trustee and beneficiary onboarding easy.
- Cost Calculators & Scenario Planning: Facilitating calculations of share dilution, contribution expenses, and taxes.
- Centralized Compliance Records: Keeping audit trails, trust deeds, and other documents for distribution purposes for regulators.
What Are the Key Governance Considerations for an EBT?
- Trustee Independence: Helping to avoid any undue influence from employers.
- Clear Trust Deed Terms: Eliminating ambiguity in relation to beneficiaries and their limits of distribution.
- Regulatory & Anti-Money Laundering (AML) Compliance: Fitting into the national trust registry and identity checking requirements.
- Documented Distributions: Keeping official documentation of decisions made by trustees.
How Can Arnifi Help Businesses Establish an Employee Benefit Trust?
An EBT is founded on comprehensive coordination involving legal, governance, and tax matters. Arnifi helps its clients with:
- EBT Structuring & Advisory: Supporting the design of trusts from inception to completion, based on their corporate objectives.
- Cross-Border Expertise: Handling international trusts and workforce incentivization programs.
- Governance & Regulatory Alignment: Ensuring that they adhere to trust laws, tax regulations, and corporate governance.
- Tech-Enabled Solutions: Offering technological solutions for document management, organogram management, record-keeping, and cost projections.
Frequently Asked Questions
What is an Employee Benefit Trust?
Employee Benefit Trust (EBT) refers to a discretionary trust established by an employer for holding assets like stocks and cash for the benefit of the employees, ex-employees, and dependents.
How does an Employee Benefit Trust work in the UK?
The EBT is formed through a trust deed in which the independent trustees are appointed by the employer in the UK. The company contributes the assets in the form of cash and stocks, and then the benefits are distributed by the trustees to the employees in accordance with the terms of the trust deed and the tax rules in the UK.
Who can benefit from an Employee Benefit Trust?
Current employees, ex-employees, directors, and sometimes even the dependents of the employees, as mentioned in the trust deed, may become the beneficiaries.
Can directors be beneficiaries of an Employee Benefit Trust?
Yes, directors and officers of the firm can be included as beneficiaries, if allowed by the trust deed and proper corporate governance and taxation issues are sorted out.
Can an Employee Benefit Trust hold company shares?
Yes. Possession of company shares in order to facilitate a share options scheme, long-term incentive plan, or succession planning is one of the main purposes of an EBT.
What are the tax implications of an Employee Benefit Trust?
The tax consequences depend on the way the EBT is funded and benefit payments are made. The payment of benefits is taxable for Income Tax and National Insurance. The employer’s contributions may be tax-allowable in accordance with specific statutory provisions.
Are Employee Benefit Trust contributions tax deductible?
Deductions from Corporation Tax are usually allowed when the contribution is paid out as qualifying benefits to the employees.
Can an Employee Benefit Trust be used for succession planning?
Yes. EBTs are commonly used in succession planning to hold the shares on behalf of employees in order to effect gradual ownership change without immediate need to sell the shares to any third party.
Can an Employee Benefit Trust operate across multiple countries?
Yes, EBTs may be set up to cater for a multinational workforce, but careful planning will be needed to take into account the international tax, reporting, and local employment law issues.
How does an EBT interact with end-of-service benefits?
The EBT is a discretionary scheme of benefits different from mandatory statutory end-of-service payments or gratuity. It is not intended to replace statutory benefits unless designed and permitted to do so.
What is the difference between an EBT and an employee share scheme?
EBT is a trust structure, while the employee share scheme refers to the scheme itself under which employees are granted shares or share options through various schemes like EMI, CSOP. An EBT is often used to hold and distribute the shares under an employee share scheme.
What are the governance requirements for an Employee Benefit Trust?
The governance considerations entail the appointment of independent trustees, proper trust deeds, distribution records, compliance with anti-money laundering regulations, and adherence to anti-avoidance tax regulations.
Can an Employee Benefit Trust be used by a multinational company?
It is common for multinational companies to have an Employee Benefit Trust for their foreign branches.
What documents are required to establish an Employee Benefit Trust?
The following are some of the documents needed to set up an Employee Benefit Trust: trust deed, trust resolution, board resolutions, and onboarding of beneficiaries/Anti-Money Laundering documentation.
Conclusion
An Employee Benefit Trust (EBT) can be seen as a highly flexible tool in companies, which can be used for retaining employees, ownership of shares, incentive planning, and business succession. Using the five-stage lifecycle of EBTs and having independent trustees to manage it, it becomes possible to ensure that employee performance is linked to the company’s development. Given the complexity of tax requirements, an EBT requires professional assistance in its setup and management.
References & Credible Resources
- HM Revenue & Customs (HMRC): Employment Income Manual – Employee Benefit Trusts
- UK Legislation: Inheritance Tax Act 1984 (Section 86 – Trusts for benefit of employees)
- The Law Society (UK): Trusts and Estate Planning Guidance
Top UAE Packages


Related Articles
Top UAE Packages
Get in Touch