
UAE E-Invoicing Regulatory Framework Guide
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: The UAE is introducing a nationwide e-invoicing framework to strengthen tax transparency and digital compliance. The rollout began with a pilot in July 2026, followed by phased mandatory implementation during 2027. Businesses need to prepare their technology, invoice data, Accredited Service Provider (ASP), internal controls and teams ahead of their applicable deadline. The system is based on structured electronic invoice data rather than PDFs, Word documents, images, scans or emails.
Table of contents
- Introduction
- Why This Change Matters for Businesses
- What Is UAE E-Invoicing and How Does It Work?
- Who Needs to Prepare for UAE E-Invoicing?
- UAE E-Invoicing Timeline | 2026 – 2027
- Five Steps to Prepare for UAE E-Invoicing
- What Businesses Need to Change in Their ERP and Accounting Systems
- Risks of Delaying E-Invoicing Preparation
- UAE E-Invoicing Penalties Businesses Should Know
- Invoice Data, Record-Keeping and System Failures
- Free Zones and Cross-Border Transactions
- What Businesses Should Do Now
- How Arnifi Helps With UAE E-Invoicing Preparation
- FAQs
- Conclusion
- Official References
Introduction
UAE e-invoicing changes how businesses create, share, report and keep invoice information. Rather than viewing an invoice as a document that’s only generated and delivered to a customer, the new framework leans on structured data that can be exchanged electronically and then reported to the Federal Tax Authority (FTA).
This system sits inside the UAE’s broader digital transformation efforts and tax-compliance priorities. It also builds on what already exists for VAT invoicing and tax-record obligations, while still bringing in a more structured way of exchanging and reporting invoice details.
The rollout kicked off in 2026, and mandatory adoption will continue in phases during 2027. So businesses should prepare ahead of their applicable deadline. Companies might need compatible ERP or accounting systems, standardised invoice data, an ASP, stronger internal controls, and trained teams.
Why This Change Matters for Businesses
Businesses subject to VAT already have invoicing obligations under Federal Decree-Law No. 8 of 2017 on VAT. They must also maintain accurate, traceable and verifiable tax records under Federal Decree-Law No. 28 of 2022 on Tax Procedures.
The e-invoicing framework builds on these requirements by moving invoice information into a structured digital format that supports electronic validation, exchange and reporting.
Structured data can improve reporting accuracy, reduce manual intervention and make transaction information easier to process and trace. The FTA and Ministry of Finance also identify digitalisation, efficiency, security and minimising VAT leakage among the objectives of the programme.
For businesses, this makes the ERP or accounting system a central part of tax compliance. A system that only creates a PDF invoice may not be sufficient for the new framework.
What Is UAE E-Invoicing and How Does It Work?
An e-invoice is structured invoice data issued and exchanged electronically between a supplier and buyer and reported electronically to the FTA.
A PDF, Word file, image, scanned copy or invoice sent by email does not qualify as an e-invoice under the UAE framework. These may be digital documents, but they do not provide the structured data required by the system.
The UAE framework is based on OpenPeppol and uses a decentralised five-corner model involving businesses, ASPs and the FTA.
ASPs support the validation and electronic exchange of invoice data, while relevant tax data is reported to the FTA through the applicable system.
Who Needs to Prepare for UAE E-Invoicing?
The framework applies to persons carrying out business in the UAE in respect of transactions within scope, subject to applicable exclusions.
The mandatory rollout is phased according to annual revenue. Businesses with annual revenue of AED 50 million or more fall into the first mandatory implementation group, while businesses below AED 50 million follow a later phase.
Transactions exclusively involving B2C supplies are currently outside the system until otherwise determined by the Minister.
Businesses can also voluntarily implement e-invoicing from 1 July 2026, subject to the applicable technical requirements.
The framework is UAE-wide, so businesses should not view it as a Dubai-only requirement.
UAE E-Invoicing Timeline | 2026 – 2027
| Date | Requirement |
| 1 July 2026 | Pilot programme begins with selected taxpayers |
| 1 July 2026 | Voluntary e-invoicing becomes available |
| 30 October 2026 | Businesses with annual revenue of AED 50 million or more must appoint an ASP |
| 1 January 2027 | Mandatory implementation for businesses with annual revenue of AED 50 million or more |
| 31 March 2027 | Businesses below AED 50 million must appoint an ASP |
| 1 July 2027 | Mandatory implementation for businesses below AED 50 million |
| 31 March 2027 | Government entities must appoint an ASP |
| 1 October 2027 | Mandatory implementation for government entities |
The original 31 July 2026 ASP appointment deadline for persons with annual revenue of AED 50 million or more was extended to 30 October 2026 by Ministerial Decision No. 66 of 2026. The 1 January 2027 mandatory implementation deadline remains unchanged.
Five Steps to Prepare for UAE E-Invoicing
1. Assess technology readiness
Review whether the existing ERP or accounting system can generate and process structured e-invoices.
Check compatibility with the UAE’s Peppol-based five-corner model and identify gaps in invoice generation, data exchange, reporting and system integration.
2. Select an Accredited Service Provider
Businesses subject to the ASP requirement should select an approved provider within the applicable deadline.
An ASP supports system integration, secure invoice exchange and the electronic reporting process. Businesses should review the Ministry of Finance’s current accredited or pre-approved ASP list before making their selection.
3. Standardize invoice data
Review and clean key information, including:
- TRN and VAT information
- Customer and supplier details
- Transaction records
- Invoice fields
- Branch information
- Legal-entity information
Consistent master data across systems can reduce validation and transmission problems.
4. Strengthen internal controls
Businesses should establish clear invoice approval and record-management procedures.
This can include approval workflows, supporting documentation, audit trails, data validation and reliable record retention. Finance, operations and IT teams should also have clearly defined responsibilities.
5. Train teams and plan implementation
E-invoicing affects finance, accounting, operations and technical teams.
Businesses should create a transition roadmap, test system integrations and use the early implementation period to identify technical and operational issues before mandatory implementation.
What Businesses Need to Change in Their ERP and Accounting Systems
ERP and accounting systems will become central to e-invoicing compliance. Businesses may need to review:

This is why e-invoicing should be treated as a finance, technology and compliance project rather than simply a change in invoice format.
Risks of Delaying E-Invoicing Preparation
Waiting until the mandatory date can create unnecessary pressure. Businesses may face:
- Non-compliance with applicable VAT invoicing requirements
- Weak or incomplete tax records
- Failure to meet ASP or implementation deadlines
- ERP or accounting-system incompatibility
- Invoice-data errors
- Failed transmissions
- Disruption to finance operations
- Higher implementation costs from rushed upgrades and training
Data cleanup, system integration and employee training can take time. Starting early gives businesses room to identify and resolve these issues before they affect normal invoicing.
UAE E-Invoicing Penalties Businesses Should Know
Cabinet Decision No. 173 of 2026 establishes the administrative penalties applicable to violations of UAE e-invoicing requirements. The framework covers failures to implement the system, late invoice and credit-note transmission, and delays in notifying an Accredited Service Provider of changes to registered data. It also introduces a cap on implementation penalties and clarifies how penalties apply when the same person acts as both Issuer and Recipient.
| Violation | Administrative Penalty |
|---|---|
| Failure by an Issuer or Recipient to implement the Electronic Invoicing System, including failure to appoint an ASP within the prescribed timeframe | AED 5,000 for the initial violation, followed by AED 5,000 for each month or part thereof during which non-compliance continues, capped at AED 50,000 within any 12 consecutive months |
| Failure to issue and transmit an electronic invoice within the prescribed timeframe | AED 100 per invoice, capped at AED 5,000 per calendar month |
| Failure to issue and transmit an electronic credit note within the prescribed timeframe | AED 100 per credit note, capped at AED 5,000 per calendar month |
| Failure to notify the appointed ASP of changes to registered data within the prescribed timeframe | AED 250 per day or part thereof, capped at AED 5,000 per calendar month |
How Are E-Invoicing Penalties Applied?
The penalty framework applies to persons required to implement the Electronic Invoicing System under the applicable legislation.
Where the same Person acts as an Issuer, Recipient or both in relation to the same violation, only one administrative penalty is imposed for that violation.
Persons implementing e-invoicing voluntarily remain excluded from these penalties until they become mandatorily subject to the system.
Businesses should review their implementation deadlines, invoice transmission procedures and ASP notification processes to minimise compliance risks.
Invoice Data, Record-Keeping and System Failures
Accurate invoice and master data will become increasingly important. Businesses should maintain reliable TRN, VAT, customer, supplier, transaction, branch and legal-entity information.
They should also maintain supporting documents, audit trails, backups and appropriate record-management procedures.
Businesses should maintain a documented process for handling technical disruptions. This can include identifying system issues, recording affected transactions, preserving invoice data, maintaining backup procedures and coordinating with the appointed Accredited Service Provider to restore normal operations.
The revised e-invoicing penalty framework does not impose a separate administrative penalty for failure to notify the FTA of a system failure. Businesses should nevertheless maintain appropriate technical controls and follow applicable operational requirements.
Free Zones and Cross-Border Transactions
E-invoicing is a UAE-wide framework rather than a Dubai mainland-only requirement. Free-zone businesses should assess their transactions against the applicable scope and exclusions.
The OpenPeppol framework is also relevant to businesses involved in international transactions because it supports interoperability and electronic document exchange across participating networks.
However, this does not mean every cross-border transaction is automatically subject to UAE e-invoicing. Businesses should assess each transaction under the applicable rules.
What Businesses Should Do Now
Businesses can begin with a practical readiness review:
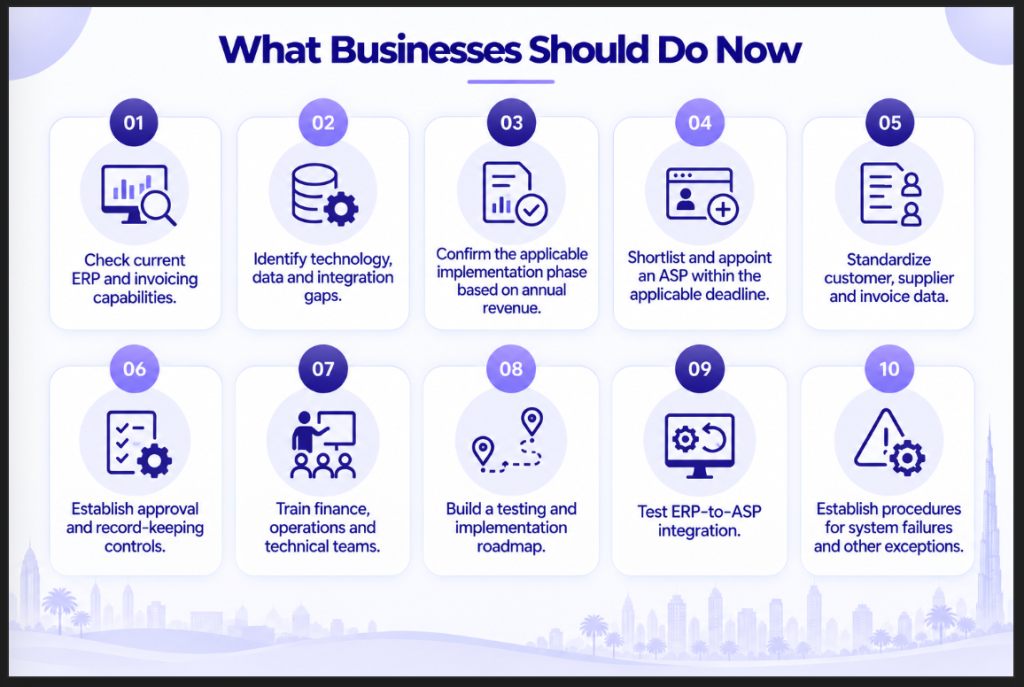
Starting early gives businesses more time to resolve compatibility and data issues before mandatory implementation.
How Arnifi Helps With UAE E-Invoicing Preparation
Arnifi can support businesses preparing for the transition through:
- E-invoicing readiness assessments
- ERP and accounting-workflow reviews
- Invoice-data and field mapping
- Master-data reviews
- ASP evaluation and integration planning
- Implementation roadmaps
- System testing
- Internal process alignment
- Finance and operations preparation
The goal is to help businesses understand what needs to change and prepare their systems and teams before their applicable deadline.
FAQs
1. What is e-invoicing in the UAE?
It is the electronic issuance and exchange of structured invoice data between suppliers and buyers, with relevant data reported electronically to the FTA. PDFs, Word documents, images, scans and emails do not qualify as e-invoices.
2. When will UAE e-invoicing become mandatory?
Businesses with annual revenue of AED 50 million or more are scheduled for mandatory implementation from 1 January 2027. Businesses below AED 50 million are scheduled for 1 July 2027, while in-scope government entities have a 1 October 2027 implementation date.
3. Who needs to appoint an Accredited Service Provider?
Businesses with annual revenue of AED 50 million or more must appoint an ASP by 30 October 2026. Businesses below AED 50 million must appoint one by 31 March 2027, subject to the applicable rules.
4. Is a PDF invoice considered an e-invoice in the UAE?
No. The UAE framework is based on structured invoice data, so a PDF, Word document, image, scanned copy or email does not qualify.
5. What are the penalties for failing to comply with UAE e-invoicing requirements?
Cabinet Decision No. 173 of 2026 establishes UAE e-invoicing penalties. Implementation failures attract AED 5,000 initially and monthly thereafter, capped at AED 50,000 within 12 consecutive months. Late invoice transmission attracts AED 100 per document, capped at AED 5,000 monthly. ASP data-change notification failures attract AED 250 daily, capped at AED 5,000 monthly.
6. How can a business prepare its ERP system for UAE e-invoicing?
Review structured invoice generation, mandatory fields, tax codes, invoice numbering, customer and supplier master data, approval workflows, audit trails, backups and integration with the selected ASP.
Conclusion
UAE e-invoicing moves businesses towards structured invoice data that can be electronically exchanged and reported, building on existing VAT and tax-record requirements. With implementation phased through 2027, businesses should assess their ERP systems, select an ASP, standardise invoice data, strengthen internal controls and train their teams early. This can help reduce compatibility issues, operational disruption and compliance risk.
Official References
- UAE Ministry of Finance – UAE eInvoicing Programme
- UAE Ministry of Finance – Cabinet Decision No. 173 of 2026 on Violations and Administrative Penalties
- UAE Ministry of Finance – Updated Administrative Penalties Related to the UAE eInvoicing System
- UAE Ministry of Finance – UAE Electronic Invoicing Guidelines
Top UAE Packages
Related Articles

Top UAE Packages
Planning Your Next Business Move?
