
Corporate Tax in the British Virgin Islands vs. Singapore | Key Differences
Anushka
Content Writer
Anushka Basu is a business content writer specialised in global business market insights. She aims to simplify complex regulatory, financial, and business concepts into… Read more
Tulika Saxena
AVP, Sales & Marketing | IIM Nagpur
Tulika Saxena specializes in business finance, sales strategy, and market positioning. Leads growth and partnerships, ensuring seamless business setup experiences and client success across… Read more


Key Fact: The BVI does not levy corporate income or capital gains tax on companies, while Singapore taxes companies at 17% of chargeable income, subject to exemptions, rebates and applicable foreign-income reliefs.
Table of contents
- Why compare corporate tax in BVI and Singapore?
- What is the corporate tax system in the British Virgin Islands?
- How does corporate tax work in Singapore?
- How do BVI and Singapore compare for corporate tax?
- How is foreign-sourced income treated in Singapore?
- What compliance obligations apply to a BVI company?
- What compliance obligations apply to a Singapore company?
- Does tax residency matter in a BVI vs Singapore structure?
- How do BVI and Singapore differ for international businesses?
- What are the main advantages and considerations of BVI and Singapore?
- What should businesses consider before choosing BVI or Singapore?
- What are the common mistakes when comparing BVI and Singapore tax?
- How can Arnifi help with BVI and Singapore business setup?
- FAQs
- Conclusion
Why compare corporate tax in BVI and Singapore?
The British Virgin Islands (BVI) and Singapore are both used in international business structures, but their corporate tax systems operate differently.
The BVI does not impose corporate income or capital gains tax on companies. Singapore, by contrast, applies a 17% corporate income tax rate to chargeable income, alongside exemptions, deductions, rebates and specific relief mechanisms.
However, comparing corporate tax rates alone can produce an incomplete picture. Businesses should also consider where operations take place, where management and control are exercised, how foreign income is treated, substance requirements, regulatory obligations and the tax position of the wider group.
The place of incorporation does not, by itself, determine the final tax position of a business or its owners.
What is the corporate tax system in the British Virgin Islands?
The BVI does not levy corporate income tax or capital gains tax on companies.
This means that a BVI company does not generally face a BVI corporate income tax charge on its profits in the same way a Singapore company does.
However, this should not be interpreted as meaning that BVI companies have no obligations or costs. Companies remain subject to corporate and regulatory requirements, including registered-agent arrangements, beneficial ownership filings and applicable financial-return obligations.
BVI Business Companies can undertake a broad range of business activities and transactions under the BVI Business Companies Act framework.
The distinction is therefore important: the absence of corporate income and capital gains tax does not eliminate corporate administration, regulatory compliance or tax obligations that may arise outside the BVI.
How does corporate tax work in Singapore?
Singapore applies a headline corporate income tax rate of 17% on chargeable income for both local and foreign companies.
Chargeable income is determined after applying the relevant tax rules, including allowable deductions and applicable tax adjustments. Singapore companies may also qualify for tax exemptions and rebates depending on their circumstances.
Two important mechanisms are:
- Partial tax exemption for qualifying companies
- Tax exemption for qualifying new start-up companies during their first three consecutive Years of Assessment
For qualifying start-ups, the current exemption can cover 75% of the first S$100,000 of normal chargeable income and 50% of the next S$100,000 for the first three consecutive YAs, subject to the eligibility conditions.
Singapore also provides a current-year corporate tax rebate. For YA 2026, Singapore provides a 50% CIT rebate on corporate tax payable, capped at S$40,000 and reduced by the S$2,000 CIT Rebate Cash Grant where applicable.
Therefore, the 17% headline rate does not necessarily represent the final tax payable by every Singapore company.
How do BVI and Singapore compare for corporate tax?
| Factor | British Virgin Islands | Singapore |
| Corporate income tax | No corporate income tax | 17% headline rate |
| Corporate capital gains tax | No corporate capital gains tax | Treatment depends on the nature of the gain and applicable rules |
| Tax exemptions | No corporate income tax exemption system of the same type | Partial and start-up exemptions may apply |
| Foreign income | Requires analysis of the relevant BVI and international rules | Foreign-sourced income received in Singapore can be taxable, subject to applicable exemptions and foreign-tax reliefs |
| Corporate compliance | Registered agent, corporate records, BO and applicable filings | Corporate tax returns, accounting records and statutory obligations |
| Tax residency | Relevant to cross-border analysis | Can affect treaty access and foreign-income treatment |
| Operating structure | Often used for international corporate structures | Established operating and regional business environment |
The comparison should be viewed as a starting point rather than a determination of which jurisdiction is appropriate for a particular business.
How is foreign-sourced income treated in Singapore?
Singapore’s treatment of foreign income is more nuanced than simply describing the country as having a “territorial tax system.”
Foreign income that does not arise from a trade or business carried on in Singapore can fall within Singapore’s foreign-sourced income rules when received in Singapore. Certain specified foreign-sourced income can qualify for exemption where the statutory conditions are satisfied.
The three specified categories include:
- Foreign-sourced dividends
- Foreign branch profits
- Foreign-sourced service income
For the Section 13(9) exemption, the relevant conditions include:
- The foreign income has been subject to tax in the foreign jurisdiction.
- The highest corporate income tax rate in that jurisdiction is at least 15% when the income is received in Singapore.
- The exemption is considered beneficial to the Singapore tax-resident company.
Foreign tax credits can also be relevant where income has been taxed in another jurisdiction. The availability and amount of relief depend on the applicable rules and circumstances.
What compliance obligations apply to a BVI company?
The absence of corporate income tax does not remove BVI corporate compliance requirements.
BVI companies generally need to maintain a registered office and registered agent and comply with applicable corporate record requirements.
Beneficial ownership filing requirements also apply. Since January 2025, BVI Business Companies and Limited Partnerships have been required to file beneficial ownership information through the VIRRGIN system, subject to the applicable framework and exemptions.
BVI Business Companies are also subject to annual-return requirements. The annual return generally needs to be filed with the registered agent within nine months after the end of the relevant financial year, subject to the statutory exceptions.
Economic substance requirements may also apply where a company carries on a relevant activity. These can include activities such as holding, fund management, finance and leasing, headquarters, intellectual property, insurance and distribution and service-centre business.
What compliance obligations apply to a Singapore company?
Singapore companies have a broader corporate tax compliance framework because corporate income tax applies to chargeable income.
Depending on the company’s circumstances, compliance can include:
- Estimated Chargeable Income (ECI) filing
- Corporate income tax returns
- Tax computations
- Accounting and record-keeping
- GST registration and compliance where applicable
- Transfer-pricing documentation where applicable
- Corporate tax residency analysis
- Foreign-income documentation
- Supporting documentation for deductions and tax reliefs
ECI is an estimate of a company’s taxable profits after tax-allowable expenses. Companies generally need to file ECI within three months from the end of their financial year unless a filing waiver or other exception applies.
Singapore companies must also file their annual corporate income tax return within the applicable deadline. For YA 2026, the general filing deadline is 30 November 2026.
Does tax residency matter in a BVI vs Singapore structure?
Yes. Incorporation and tax residency are separate questions.
A company may be incorporated in one jurisdiction while its management, control or business activities create tax considerations in another jurisdiction.
Tax residency can affect:
- Access to tax treaties
- Foreign-income treatment
- Foreign tax credits
- Permanent-establishment analysis
- Corporate tax obligations in other jurisdictions
- Substance requirements
This is particularly important for a BVI company that is managed or operated from another country. The BVI incorporation itself should not be treated as a guarantee that profits will remain outside the tax net of every other jurisdiction.
Similarly, establishing a Singapore company does not mean that every item of foreign income will automatically receive the same Singapore tax treatment.
How do BVI and Singapore differ for international businesses?
The two jurisdictions can serve different structural and commercial purposes.
BVI structures can be relevant for international holding companies, investment structures and other cross-border corporate arrangements. Singapore, meanwhile, is also an established location for regional headquarters and operating businesses.
The decision can depend on:
- Whether the entity will hold investments or conduct active operations
- Where management will take place
- Where customers and suppliers are located
- Source of revenue
- Banking requirements
- Investor expectations
- Substance requirements
- Foreign-income treatment
- Applicable tax treaties
- Regulatory requirements
The tax position should therefore be considered alongside the commercial function of the entity.
What are the main advantages and considerations of BVI and Singapore?
| Consideration | BVI | Singapore |
| Corporate income tax | No corporate income tax | 17% headline CIT |
| International structuring | Established international corporate-structuring jurisdiction | Established operating and regional business hub |
| Tax incentives | No conventional corporate income tax regime | Exemptions, rebates and other incentives may apply |
| Foreign-income planning | Requires analysis of BVI and other relevant jurisdictions | Specific foreign-income exemptions and foreign tax credits may be available |
| Substance and compliance | Corporate, beneficial ownership and economic-substance obligations may apply | Extensive tax, accounting and corporate compliance framework |
| Business operations | Depends on the structure and activities | Developed ecosystem for regional and operating businesses |
Neither column should be treated as a universal recommendation. The appropriate structure depends on the company’s actual circumstances.
What should businesses consider before choosing BVI or Singapore?
Businesses should assess the complete operating and ownership structure before incorporating. Important considerations include:
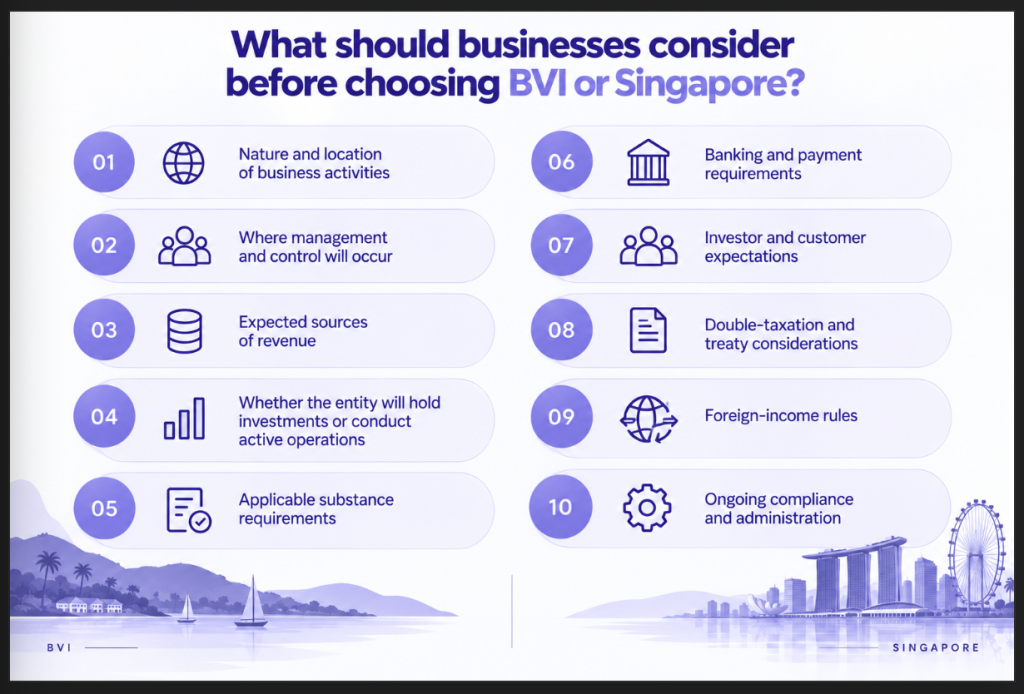
A side-by-side tax and operational assessment can help identify the relevant implications before the company is established.
What are the common mistakes when comparing BVI and Singapore tax?
Several assumptions can lead to an inaccurate comparison:
- Assuming BVI means “no taxes anywhere”
- Treating Singapore’s 17% rate as the effective tax rate for every company
- Ignoring foreign-income rules
- Confusing incorporation with tax residency
- Overlooking substance and management requirements
- Ignoring corporate and beneficial ownership filings
- Choosing a jurisdiction before defining the company’s actual activities
A tax comparison should therefore begin with the proposed structure and business model rather than the headline corporate tax rate alone.
How can Arnifi help with BVI and Singapore business setup?
Arnifi can help businesses assess their intended business model and ownership structure before choosing between BVI and Singapore.
Support can include company formation, documentation, coordination of corporate compliance requirements and assistance with ongoing administration.
For cross-border structures, the focus can be on understanding the interaction between incorporation, tax residency, business activities and international tax considerations rather than promising a particular tax outcome.
FAQs
Is there corporate tax in the British Virgin Islands?
The BVI does not levy corporate income tax or corporate capital gains tax on companies.
What is the corporate tax rate in Singapore?
Singapore’s headline corporate income tax rate is 17% of chargeable income for local and foreign companies.
Is BVI completely tax-free for companies?
No. While there is no corporate income or capital gains tax, other taxes, fees, regulatory obligations and foreign-country tax exposures can apply.
Does Singapore tax foreign-sourced income?
Foreign-sourced income received in Singapore can be taxable, although specific exemptions and foreign tax reliefs may apply.
Is Singapore corporate tax applicable to foreign companies?
Yes. Singapore’s 17% corporate income tax rate applies to both local and foreign companies on relevant chargeable income.
Does BVI have capital gains tax?
The BVI does not levy corporate capital gains tax on companies.
Does incorporation in BVI automatically make a company tax-free?
No. Tax exposure can arise in other jurisdictions based on management, activities, residence and the company’s overall structure.
Which factors should businesses compare before choosing BVI or Singapore?
Businesses should compare tax, residency, substance, operations, foreign-income rules, banking, compliance and commercial requirements.
Do BVI companies have annual compliance requirements?
Yes. BVI companies can have annual return, beneficial ownership, corporate record, and other regulatory filing obligations.
Can a Singapore company claim foreign tax credits?
Singapore provides foreign tax credit mechanisms subject to the applicable rules and conditions. The treatment depends on the income and relevant foreign jurisdiction.
Conclusion
BVI and Singapore have fundamentally different corporate tax frameworks. The BVI does not levy corporate income or capital gains tax on companies, while Singapore applies a 17% headline corporate income tax rate alongside exemptions, rebates and foreign-income relief mechanisms. The appropriate jurisdiction depends on the company’s activities, management, income sources, substance, compliance requirements and wider cross-border tax position. A complete structural assessment should be carried out before incorporation.
Official references
- BVI Financial Services Commission – Tax Structure in the BVI
- BVI Financial Services Commission – Corporate Structures
- BVI Financial Services Commission – Beneficial Ownership Regulations
- IRAS – Corporate Income Tax Rate, Rebates & Tax Exemption Schemes
- IRAS – Companies Receiving Foreign Income
- IRAS – Estimated Chargeable Income Filing
Top British Virgin Island Packages

Related Articles
BVI vs Cayman Company Formation (2026) | Entity Ty...
Key Fact Both jurisdictions provide English common law frameworks for international business. BVI offers cost-efficient corporate management for private asset...
Top British Virgin Island Packages
Get in Touch